


Tutor Perini (TPC) is back in focus after reporting record operating cash flow of US$334.1 million for the first half of 2026, along with record quarterly revenue and a near record US$19.9b backlog.
The share price tells a different part of the story. Tutor Perini’s stock has eased 6.6% over the past month after a strong run. However, the 90 day share price return of 9.9% and very large 3 year total shareholder return of roughly 10x point to momentum that has been building rather than fading.
Scan other construction and infrastructure plays that show similar cash flow strength and multiyear work visibility with our curated 29 high quality undervalued stocks.
So, with Tutor Perini trading below both intrinsic value estimates and analyst targets after a strong multi year run, is the market prudently discounting risk, or is it simply underpricing what is already in plain sight?
Most Popular Narrative: 24% Undervalued
Tutor Perini’s most followed valuation narrative places fair value at $113.25, ahead of the last close at $85.67, which frames the recent pullback as a pricing gap rather than a broken story.
Record backlog growth, now at an all-time high of $21.1 billion (up 102% YoY), provides strong visibility and multi-year revenue predictability, as a series of major projects ramp up over the next several years.
Sustained federal and state infrastructure funding, particularly for large-scale transit and civil projects (Midtown Bus Terminal, Sepulveda Transit Corridor, Indo-Pacific Defense contracts), is fueling robust project pipeline expansion, favorably impacting both future revenue and long-term earnings growth.
See why 22 investors see Tutor Perini as 24% undervalued.
Result: Fair Value of $113.25 (UNDERVALUED)
Still, the Tutor Perini narrative leans heavily on a handful of mega public projects. As a result, delays, funding changes or fresh cost disputes could quickly unsettle that fair value story.
Find out about the key risks to this Tutor Perini narrative.
Another View: Tutor Perini Through The P/E Lens
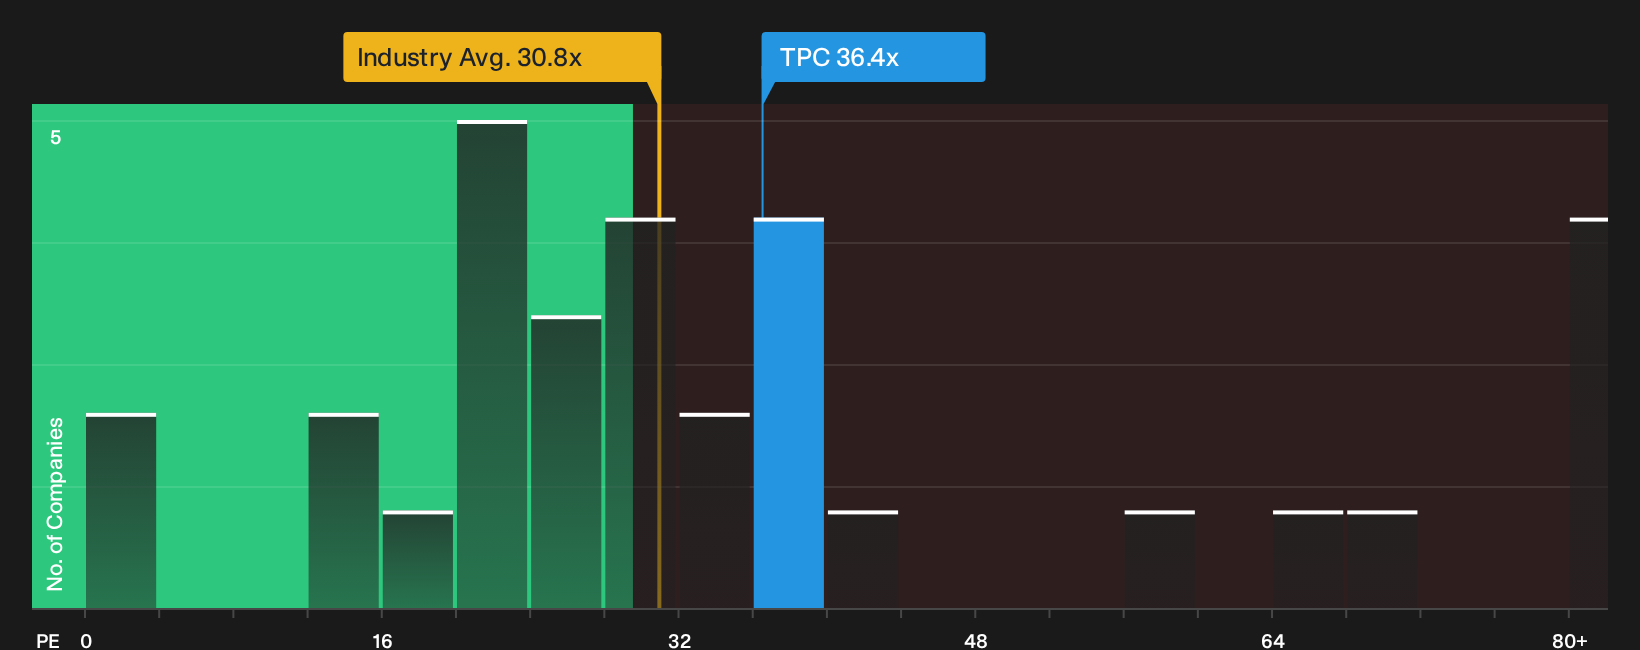
There is a different read on Tutor Perini once the focus shifts from fair value estimates to the current P/E ratio. At 36.3x, the shares trade richer than both peers at 28.1x and the US Construction group at 30.8x, even though the fair ratio sits higher at 50.2x.
This mix of a premium P/E against sector and peer averages, and a fair ratio that suggests more headroom, leaves a simple question for investors. Is the real risk that expectations are already crowded into the price, or that the market is still underestimating how the story could evolve from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel uncomfortable, especially when Tutor Perini carries both clear concerns and appealing upsides. Consider acting promptly, review the underlying metrics yourself, then weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Tutor Perini?
If you stop with Tutor Perini, you only see one angle. Broaden your watchlist with fresh ideas that match how you actually like to invest.
- Target value first and hunt for stocks where quality and price combine using our curated 29 high quality undervalued stocks.
- Prioritize resilience and focus on companies with sturdy finances by checking the list of solid balance sheet and fundamentals (23 results).
- Aim for stability and lower volatility by scanning the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com