


A new wave of potential mega-IPOs around AI and space is turning equity capital markets into front-page news again, and you do not need to be an investment banker to care. Big offerings can reshape fee pools, deal pipelines and investor attention, which can reward some listed intermediaries more than others. This article walks through 3 stocks exposed to that IPO story and explains why each might deserve a closer look now.
The three stocks below are just a sample, and the full screen surfaced 39 more listed intermediaries with equally detailed and potentially interesting IPO-linked narratives that are not covered here. To go straight to the source and identify, analyze, and refine your highest-conviction ideas, head into the Global Equity Capital Markets and IPO Beneficiaries screener.
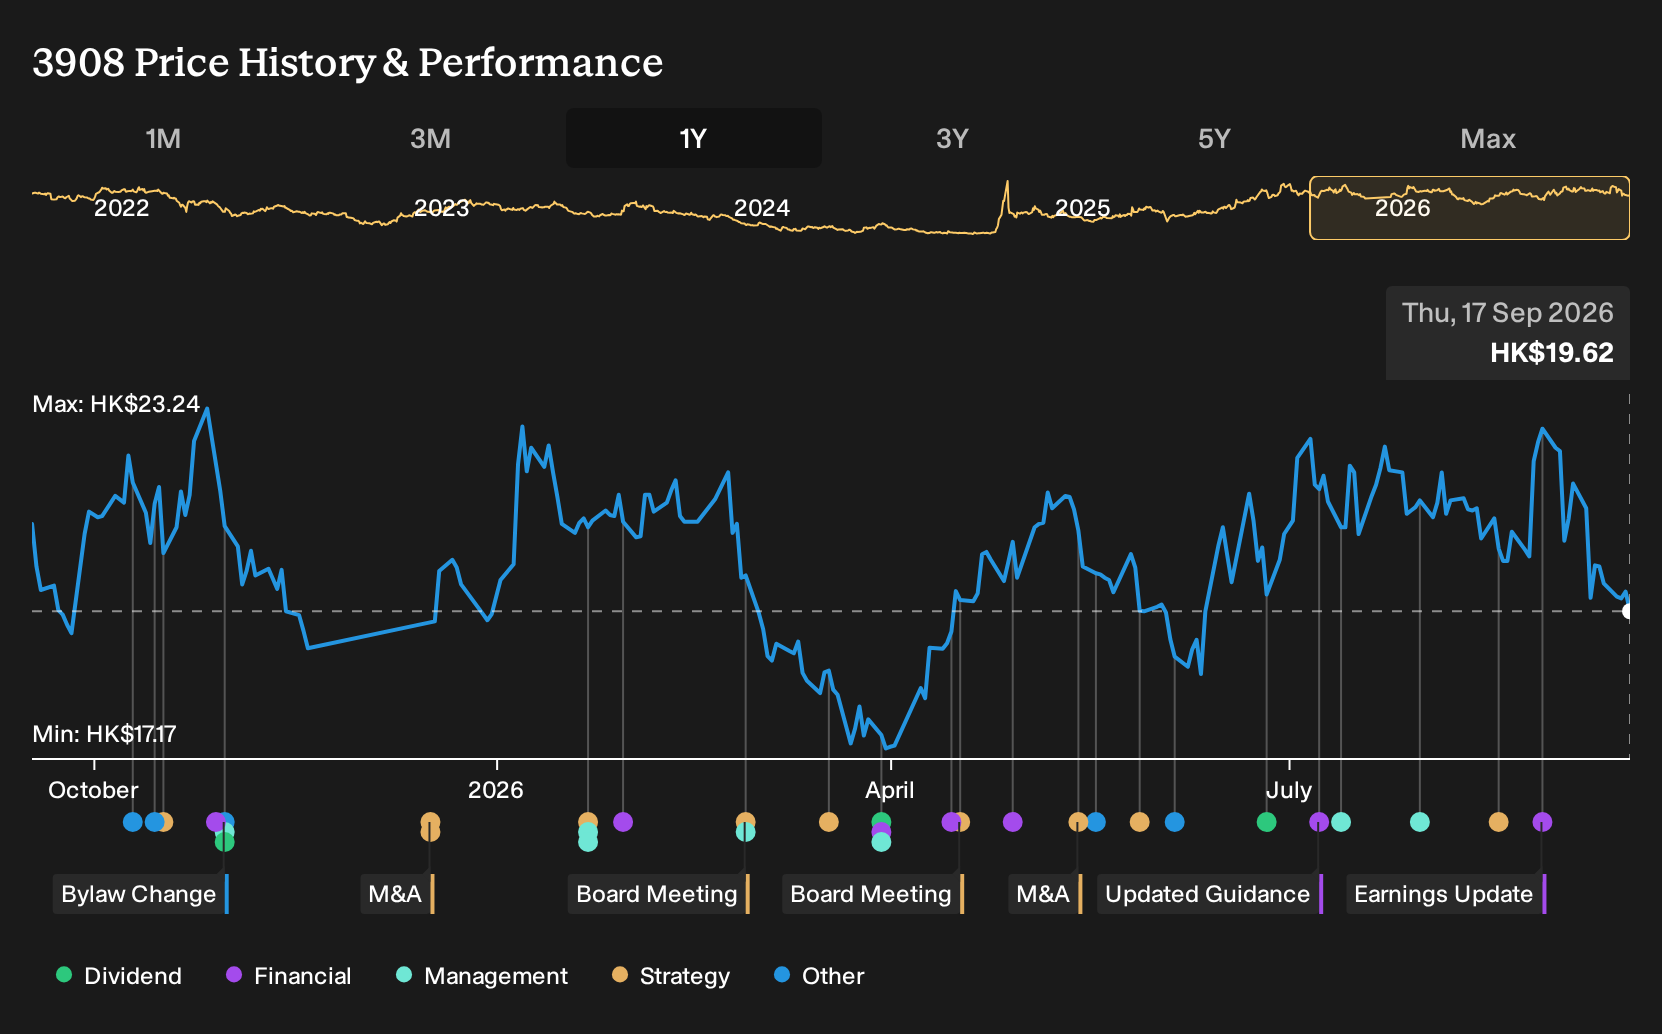
China International Capital (SEHK:3908)
Overview: China International Capital is a Beijing based investment bank focused on underwriting, equity capital markets, trading and wealth management for Chinese and global clients.
Operations: Revenue is concentrated in wealth management at about CN¥12.2b, with sizeable contributions from equities at CN¥9.5b and investment banking at CN¥6.6b.
Market Cap: HK$146.1b
China International Capital provides exposure to China focused equity capital markets, combining an IPO and underwriting franchise with trading and wealth channels that serve technology and space related issuers. The stock is linked to equity capital markets fee pools, and future returns may depend on how underlying pressures influence issuance quality and pricing power.
Those pressures on issuance quality raise the real question. Step into the China International Capital financial health report to see how China International Capital’s balance sheet frames that upside.
CSC Financial (SEHK:6066)
Overview: CSC Financial is a Beijing based securities firm that focuses on investment banking, IPO and equity underwriting, brokerage, and asset management.
Operations: CSC Financial generates about CN¥13.9b from transaction and institutional client services, CN¥9.1b from wealth management, and CN¥3.1b from investment banking, with smaller contributions from asset management and other activities.
Market Cap: HK$190.3b
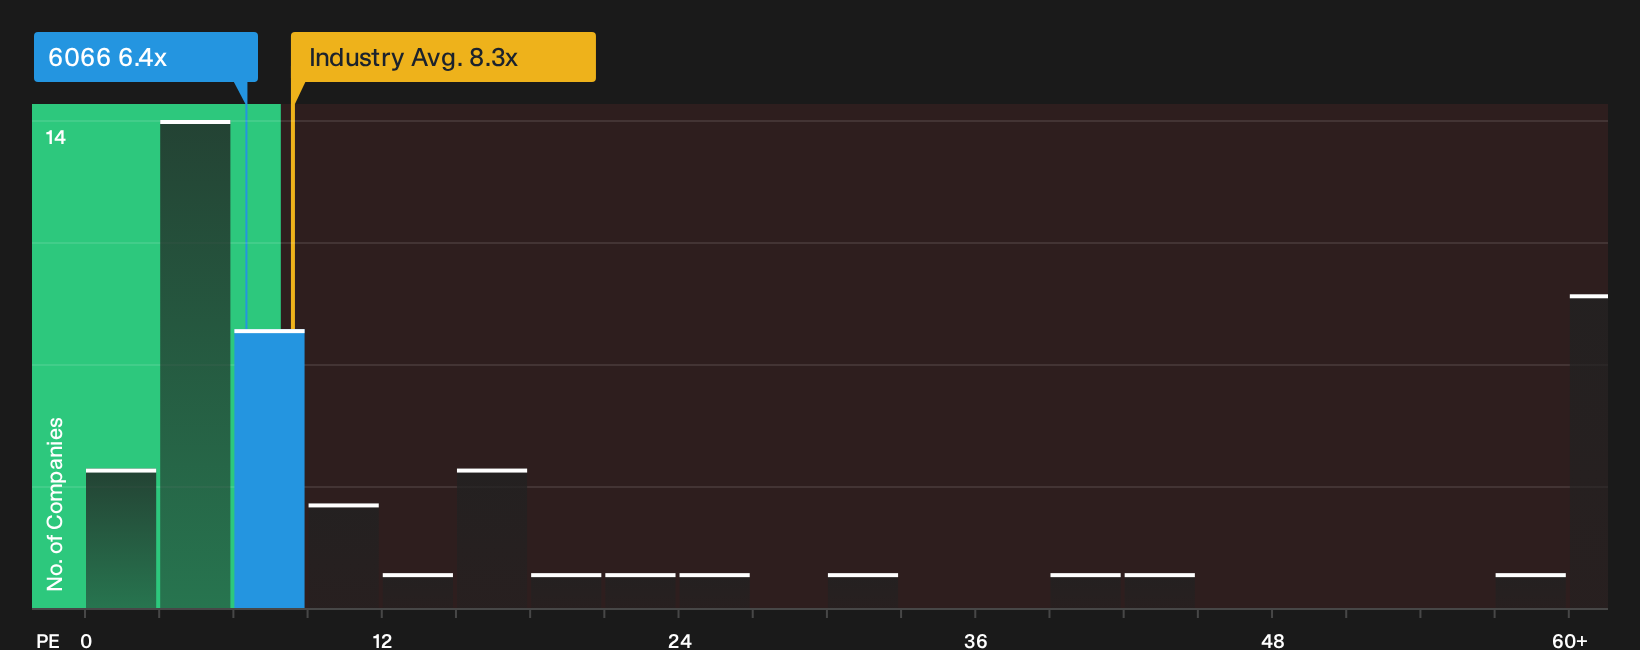
CSC Financial is closely aligned with the Global Equity Capital Markets and IPO Beneficiaries theme. Its core investment banking, ECM and IPO underwriting operations in Mainland China and Hong Kong link its earnings to large listing activity. Recent profit guidance and a P/E around 6.4x give investors exposure to that issuance cycle, depending on how one unseen pressure shapes future deal quality and fee margins.
That unseen pressure is exactly what the market is trying to price in, so head straight to the 4 key rewards and 1 important warning sign to see how the fee story could be shifting.
Daiwa Securities Group (TSE:8601)
Overview: Daiwa Securities Group is a Tokyo headquartered securities group providing wealth management, asset management, and global investment banking with equity underwriting.
Operations: Daiwa Securities Group generates about ¥321.1b from Wealth Management, ¥284.1b from Global Markets & Investment Banking, and ¥119.2b from Asset Management, with smaller contributions elsewhere.
Market Cap: ¥2,539.6b
For the Global Equity Capital Markets and IPO Beneficiaries theme, Daiwa Securities Group brings a mix of Japanese wealth clients and global underwriting that can link fee income to large tech and AI listings without relying solely on one region or deal type.
"Acceleration of asset-based, recurring revenues as wrap accounts, fund wraps and total asset consulting steadily gain net inflows."
The key consideration is how a shift toward higher margin fee business, compared with traditional deal driven income, may shape Daiwa Securities Group’s earnings power.
That shift in earnings mix is exactly what the full narrative for Daiwa Securities Group unpacks, highlighting where recurring fees, underwriting cycles, and risk controls may be quietly decoupling for Daiwa Securities Group.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Do not get caught dropping in late, act now.
- Spot sturdy cash generators early by tracking the list of solid balance sheet and fundamentals (196 results), which filters for resilient businesses before wider momentum starts to build.
- Follow structural demand in critical materials with the curated 29 top copper producer stocks before copper producers experience pricing pressure on every earnings call.
- Target durable income streams using the hand picked 158 dividend fortresses while dividend yields and payout strength remain aligned with your objectives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com