


Minth Group (SEHK:425) has drawn fresh attention after recent trading left the share price around HK$24. Returns over the past month and past 3 months have both shown double digit declines.
The recent drop has left Minth Group with a 30-day share price return down 15.6% and a 90-day share price return down 18.7%, while the year-to-date share price return is down 28.7% and the 1-year total shareholder return is down 30.7%. However, the 3-year total shareholder return remains positive at 23.3%, which signals fading near term momentum against an earlier recovery for longer term holders.
Scan how Minth Group compares with other auto and manufacturing plays under pressure right now by reviewing the curated 105 resilient stocks with low risk scores that still screen well on resilience and fundamentals.
Minth Group’s slide has sparked a simple tension. Are investors finally pricing in something about the underlying auto parts business, or has sentiment run ahead of what the current valuation numbers actually say?
Price-to-Earnings of 8.4x: Is it justified?
Minth Group now trades at HK$24, which lines up with a P/E of 8.4x that screens as cheap against both its peer set and the broader Asian auto components industry.
The P/E ratio compares what investors are paying today for each unit of earnings. For an auto parts supplier with established manufacturing operations and a wide geographic footprint, this measure often becomes a quick shorthand for how the market is weighing current profitability against future expectations.
For Minth Group, earnings growth over the past year of 12.7% and a 5-year pace of 14.4% per year sit alongside forecasts that call for revenue growth of 13.5% per year and earnings growth of 13.4% per year. That combination of current and projected profit trends, alongside high quality earnings, supports the idea that an 8.4x multiple implies the market is applying a relatively cautious lens to those numbers rather than paying up for growth.
Compared to the Asian Auto Components industry average P/E of 16.9x and a peer average of 12.7x, Minth Group trades on a meaningfully lower multiple. The estimated fair P/E of 10.9x is also higher than the current 8.4x level, which points to room for the valuation multiple to move closer to that reference point if the investment case holds together.
Explore the SWS fair ratio for Minth Group.
Result: Price-to-Earnings of 8.4x (UNDERVALUED)
Still, the investment case around Minth Group can weaken quickly if global auto demand softens further, or if large customers push through tougher pricing and contract terms.
Find out about the key risks to this Minth Group narrative.
Another view on Minth Group’s value
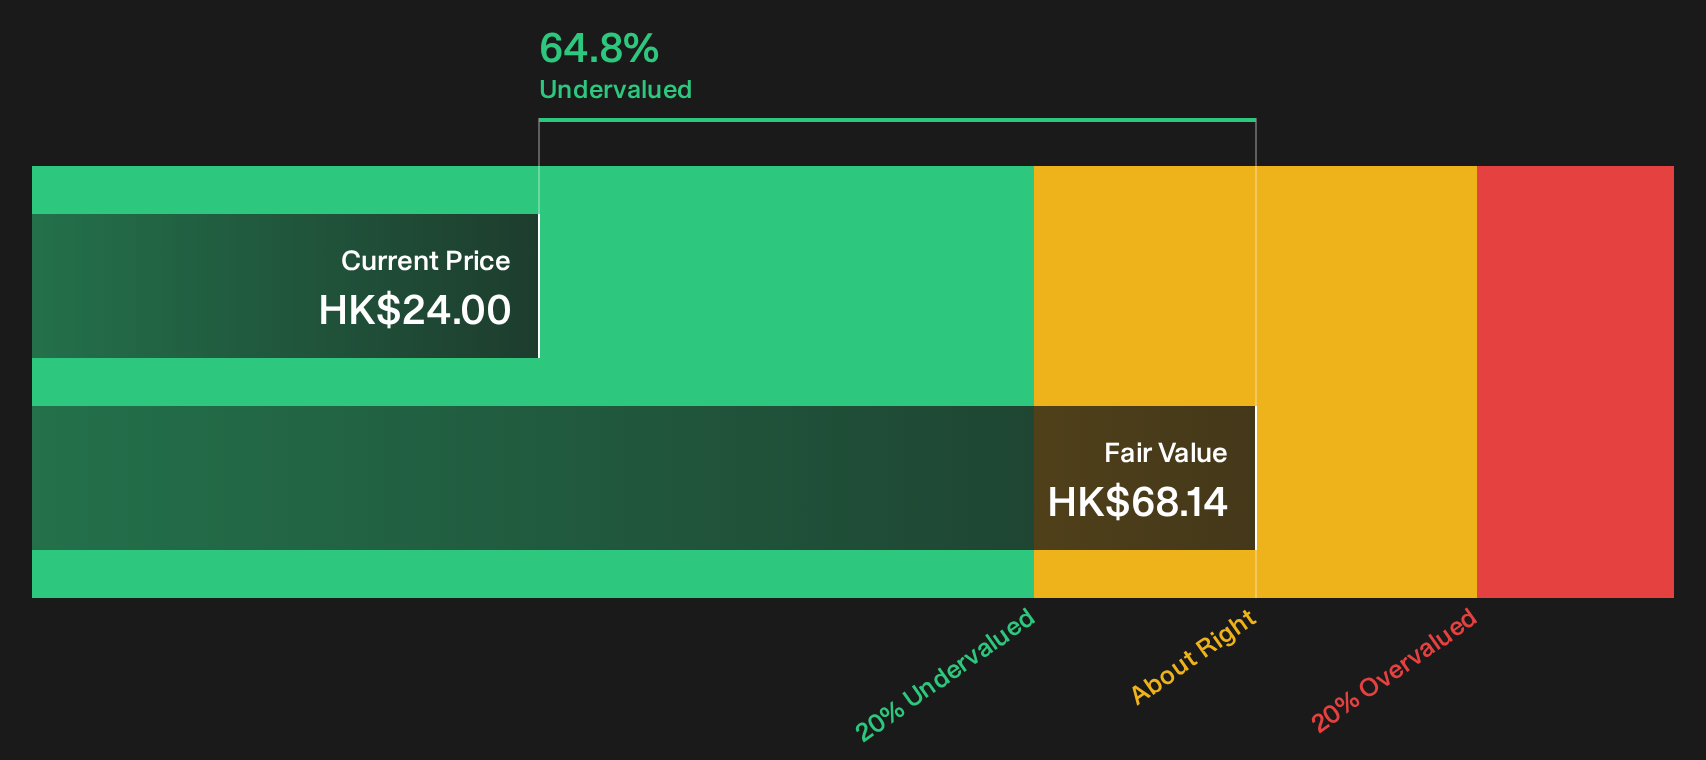
On a P/E of 8.4x, Minth Group already looks inexpensive, yet our DCF model sketches an even starker picture. The shares trade at HK$24 while the future cash flow value sits at HK$68.14, which implies a wide gap that investors need to judge carefully.
Before relying too heavily on any single approach, it is worth seeing how the SWS DCF model is built and what is driving that HK$68.14 figure in the first place. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Minth Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Minth Group can feel confusing, so treat this as a prompt to move fast, review the numbers yourself, and weigh both sides of the story. To help frame that view, start with the balance of 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Minth Group?
If Minth Group has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with other ideas that might fit your plan.
- Target value opportunities that combine strong fundamentals with attractive pricing by scanning the curated 173 high quality undervalued stocks.
- Strengthen your portfolio’s foundation by reviewing a list of solid balance sheet and fundamentals (196 results) that can withstand tougher conditions without stretching finances.
- Hunt for potential future leaders before they are widely followed by checking a focused set of 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com