


Newmark Group has given shareholders a bumpy ride, with a sharp 3 year surge in returns followed by more recent weakness, which naturally pushes the focus back onto what its current earnings really justify at today’s share price. With the stock closing at US$13.84, the key issue for you is whether that figure still lines up with what the business is actually earning.
- Over the past 3 years the stock has delivered a return of 120.4%, which puts a lot of weight on the question of how firmly its earnings can support that kind of gain.
- Newmark Group’s valuation story now hinges on how efficiently it can convert its real estate services into consistent profits, since the durability and quality of those earnings drive what investors may be willing to pay for each dollar of income.
- The analysts covering Newmark Group have run their own numbers. See what analysts think Newmark Group's shares could be worth.
The stock’s next move may depend on whether Newmark Group’s current earnings are strong and reliable enough to make today’s price look sensible.
If you want more context on whether Newmark Group’s recent upswing and pullback still leave room for value based on its earnings, it can help to line it up against 29 high quality undervalued stocks.
Is Newmark Group Still Cheap on Earnings?
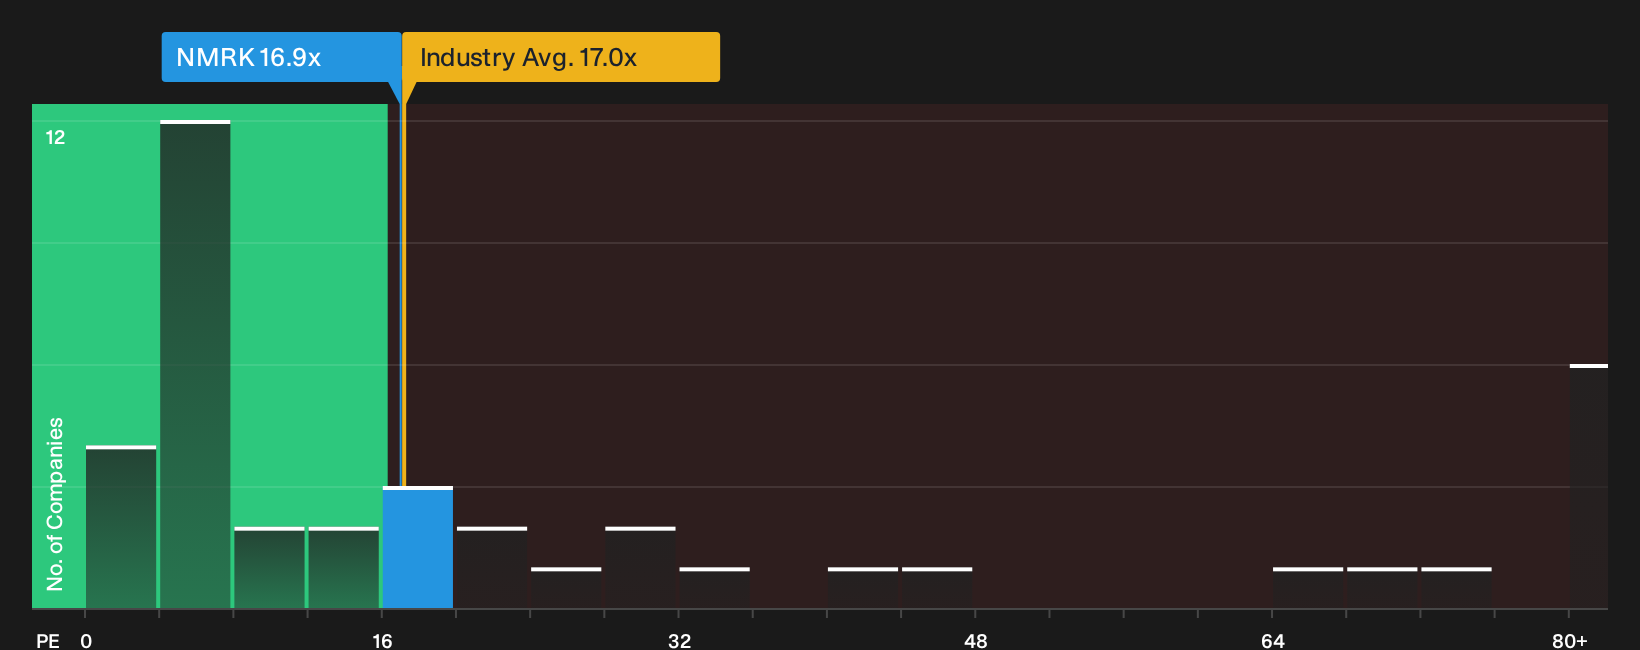
The P/E ratio suits Newmark Group because earnings remain a central yardstick for a fee based real estate services business. On this measure, the stock trades on about 16.9x earnings, which sits very close to the wider real estate sector on roughly 17.0x. That puts the share price in the same general ballpark as the industry, rather than flagging an obvious premium or discount purely on headline multiple.
The fair P/E that would typically be expected for Newmark Group, based on its own mix of growth drivers, profitability and risk profile, screens higher than where the shares change hands today. That gap suggests the current 16.9x earnings leaves some room between what investors are paying and what this framework implies might be justified if the business delivers in line with those assumptions. Peer stocks on average trade on a much richer 111.5x, so the relative setup is quite different once you look beyond the sector level. Explore the numbers behind Newmark Group's P/E valuation.
The Newmark Group Narrative: What Would Justify Today's Price?
Narratives for Newmark Group pick up where the P/E discussion leaves off by explaining which paths for growth, margins and earnings would need to occur for the stock to appear meaningfully mispriced against today’s US$13.84. Each one presents fair value as a clear thesis about how Newmark Group’s business could develop over time, so you can monitor whether those underlying assumptions hold up or break down on Simply Wall St’s Community page.
One of the top community narratives on Newmark Group: 21% undervalued
"Diversified global expansion, growing high-value verticals, and focus on recurring revenues and technology position Newmark for stable, long-term earnings..."
Discover why this Narrative puts Newmark Group at 21% undervalued.
One more angle on Newmark Group that could shift how you see the stock
Everything so far has focused on what Newmark Group looks like today, but professional coverage also sketches where the business might be a few years from now. This gives you a different reference point to compare with the current multiple. Explore where analysts expect Newmark Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com