


Warner Bros. Discovery (WBD) just leaned further into the Harry Potter universe, pairing a fresh PowerA licensing deal for gaming accessories with plans for three new wizarding lands at Warner Bros. World Abu Dhabi.
The share price reaction has been steady rather than explosive, with a 90-day share price return of 7.79% and a small 1-day move of 0.61% up to US$28.24. Meanwhile, the 1-year total shareholder return of 51.02% and 3-year total shareholder return of 145.35% point to a longer pattern of investors warming to Warner Bros. Discovery, as new IP driven projects, like the Harry Potter gaming accessories and Abu Dhabi expansion, hint at both fresh revenue streams and a shifting view of the company’s risk profile.
Seize this Harry Potter momentum at Warner Bros. Discovery and scan for other media and entertainment plays riding powerful fan franchises with our curated 16 high quality undiscovered gems.So is Warner Bros. Discovery’s recent climb a clear reflection of improving fundamentals, or mostly a sentiment reset around its IP and deals like Harry Potter, which the current valuation now needs to justify?
Most Popular Narrative: 55% Overvalued
Warner Bros. Discovery last closed at $28.24, while the most followed narrative pegs fair value closer to $18.17, so the market price sits well above that reference point and puts extra weight on how investors view deals like the Paramount transaction and Harry Potter initiatives.
A Multivariable Risk Equation For investors, the central question became not simply whether the merger made business sense but whether the probability-weighted return justified the growing uncertainty surrounding execution. Without greater clarity from regulators and WBD’s board, the transaction would have likely continued to trade as a high-volatility, event-driven story. This and other factors incentivized Netflix and WBD to reconsider whether the deal was worth it and to move forward with Paramount instead, a move that investors across the board hailed as the right call.
See why 13 investors see Warner Bros. Discovery as 55% overvalued.
Result: Fair Value of $18.17 (OVERVALUED)
Still, the narrative can flip fast if Warner Bros. Discovery’s loss of US$3.17b persists, or if the Paramount transaction hits fresh regulatory or financing snags.
Find out about the key risks to this Warner Bros. Discovery narrative.
Another View: Warner Bros. Discovery Through A Sales Lens
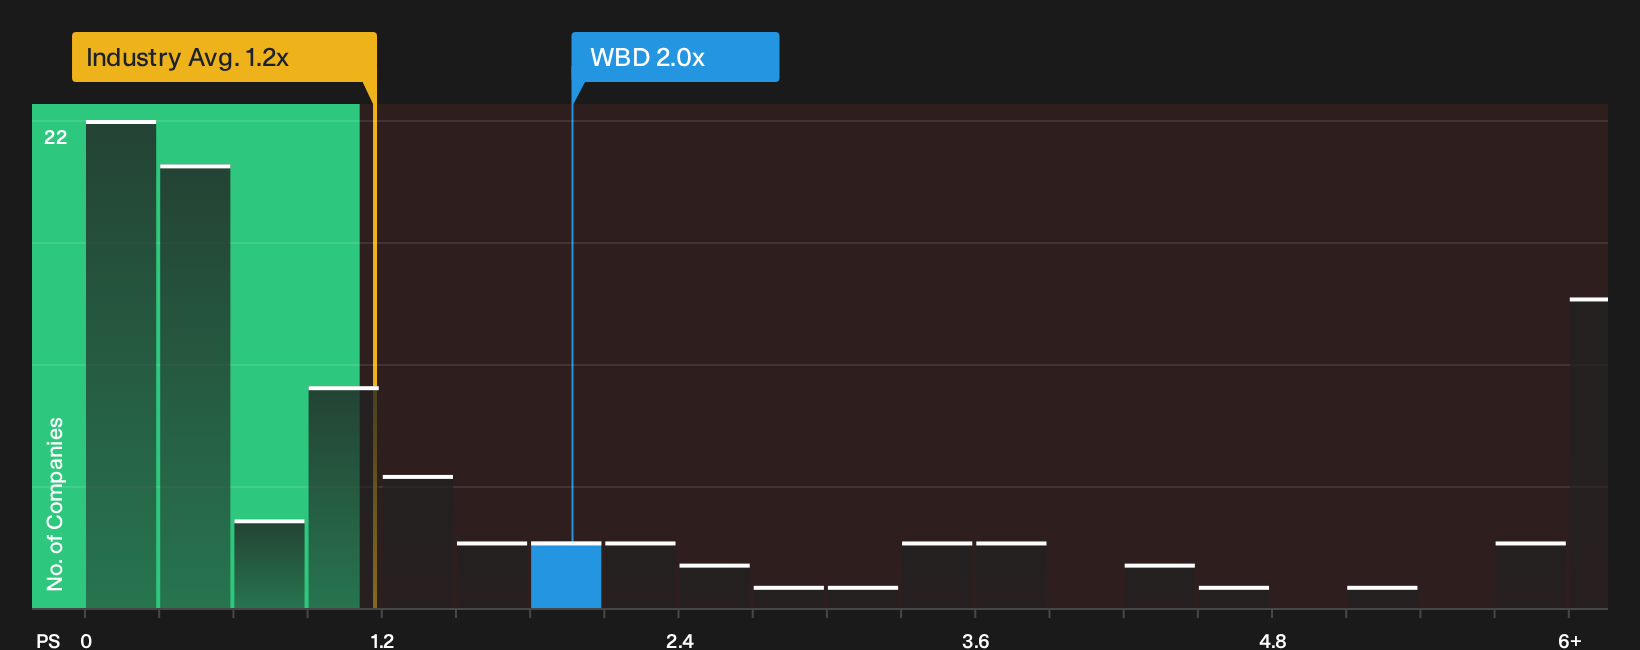
The first narrative leans on a fair value of $18.17, which implies Warner Bros. Discovery trades rich. Yet on a P/S basis the picture is mixed. WBD trades at 2x sales versus a fair ratio of 2.6x, below the peer average of 2.8x, but above the US Entertainment industry at 1.2x. That split suggests valuation risk if sector sentiment cools, but also some room for re-rating if peers remain more expensive. Which crowd do you think the market leans toward over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Warner Bros. Discovery can either sharpen your thinking or blur it. Move quickly, pressure test the key numbers, and weigh both the downside and upside using the 2 key rewards and 1 important warning sign.
Looking for more Warner Bros. Discovery style ideas?
If you like the Harry Potter momentum at Warner Bros. Discovery, do not stop here. Broaden your watchlist so one story does not control your portfolio.
- Target deep value opportunities by scanning our universe of companies that screen as mispriced on quality and cash flow using the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with resilient finances through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed potential where strong fundamentals have not yet attracted broad attention by checking the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com