


CareTrust REIT has treated long term holders to a powerful run over the past few years, which naturally raises a question for anyone looking at the stock today. With the price now around recent highs and fresh deal activity reshaping the portfolio, investors are asking whether CareTrust REIT's current valuation is adequately supported by its earnings power.
- Over the past 5 years the share price has delivered roughly 127%, which puts real pressure on the question of how much earnings strength is already reflected in the current market value.
- The recent US$400 million skilled nursing acquisition and US$600 million investment pipeline may support higher rental income and more stable earnings, but they also commit the business to deploying significant capital that needs to be justified by future returns.
- Your read on CareTrust REIT is one view; the desks covering it have another. See what analysts think CareTrust REIT's shares could be worth.
For investors, the debate is whether CareTrust REIT's current share price is appropriately aligned with what its earnings can justify today and over time.
If you are weighing whether CareTrust REIT's recent acquisition spree justifies its current earnings-based valuation, a focused stock screen of other real estate names with similar traits can help. You can start with 29 high quality undervalued stocks.
Does CareTrust REIT Look Undervalued on Earnings?
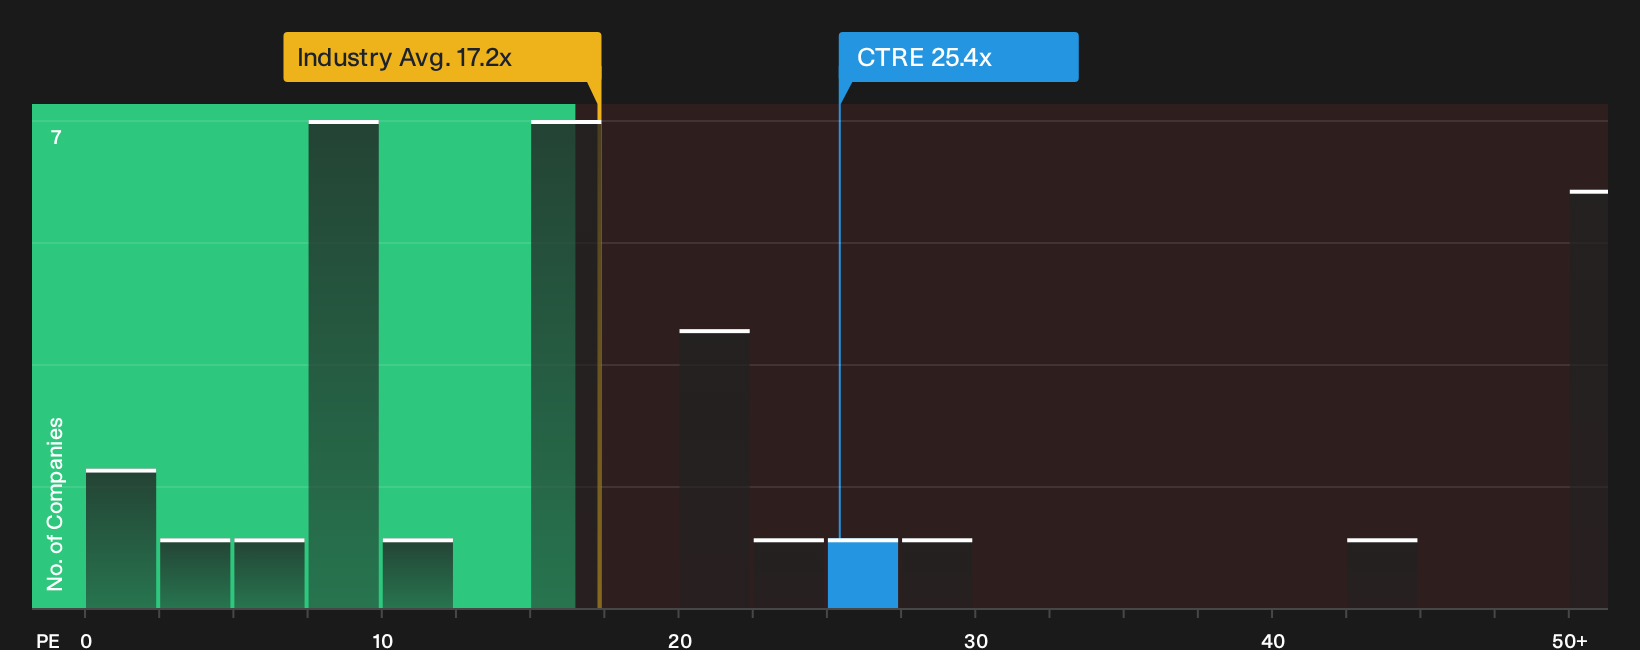
The P/E ratio works well for CareTrust REIT because earnings are a key driver for how investors judge income-focused real estate companies. On this metric, the stock trades on about 25.4x earnings, which is above the Health Care REITs industry average of roughly 17.2x and well below the peer group around 63.9x.
The fair-value framework, which weighs CareTrust REIT's size, sector, profitability and risk, points to a higher multiple than where the shares trade now. As a result, the current 25.4x screens as undervalued on that basis. Because the recent US$400 million skilled nursing acquisition and US$600 million pipeline are already public, the fact that the P/E still comes in below this tailored benchmark suggests the current price is not demanding relative to what the market usually pays for similar earnings profiles. Explore the numbers behind CareTrust REIT's P/E valuation.
The CareTrust REIT Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question on CareTrust REIT leaves off by spelling out which paths for growth, margins and earnings would need to play out for the shares to look meaningfully cheap or expensive versus today. Each scenario links a fair value estimate to a clear storyline about CareTrust REIT's potential catalysts and pressure points, so you can watch over time which version of events is actually unfolding on the Community page.
One of the top community narratives on CareTrust REIT: 16% undervalued
"The recent acquisition of Care REIT and entry into the U.K. care home market significantly diversifies the asset, operator, and geographic mix..."
Discover why this Narrative puts CareTrust REIT at 16% undervalued.
One big question on CareTrust REIT still sits with who is steering it
For a real estate income vehicle like CareTrust REIT, the people allocating capital and the way their pay is structured can matter as much as any P/E multiple. Yet that piece of the puzzle is still unchecked here. See who runs CareTrust REIT and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com