


Piper Sandler Companies (PIPR) has expanded its equities trading footprint into Europe, launching operations through Piper Sandler Europe after securing regulatory approval in France and opening a new office in Paris.
The European move comes at a tricky moment for Piper Sandler Companies shareholders. The share price is US$72.09, with the 7 day and 90 day share price returns down 5.28% and 11.87%. However, the 3 year total shareholder return is up 111.56%, suggesting stronger longer term performance despite more recent weakness.
Compare Piper Sandler Companies' European push with other financials launching fresh growth initiatives by scanning our curated list of 16 high quality undiscovered gems for potential under-the-radar opportunities.
Piper Sandler Companies is pushing into Europe just as its share price has come under pressure, so the real issue now is whether that recent weakness already reflects the risks or still tips the balance away from buyers.
Most Popular Narrative: 18% Undervalued
The most followed valuation story pegs Piper Sandler Companies’ fair value at $88.13, comfortably above the last close at $72.09. This puts the current pullback in a different light for anyone weighing the new European build out.
Growth in private credit and sponsor activity is expanding the opportunity set for debt capital markets advisory, private capital advisory and restructuring work. This can affect advisory revenues and support operating leverage as more of the fee pool shifts to these higher value services.
See why 1 investors see Piper Sandler Companies as 18% undervalued.
Result: Fair Value of $88.13 (UNDERVALUED)
Still, the Piper Sandler Companies story can shift quickly if equity issuance or bank M&A pipelines dry up, or if tech and defense hiring outpaces fee momentum and compresses margins.
Find out about the key risks to this Piper Sandler Companies narrative.
Another View on Piper Sandler Companies’ Valuation
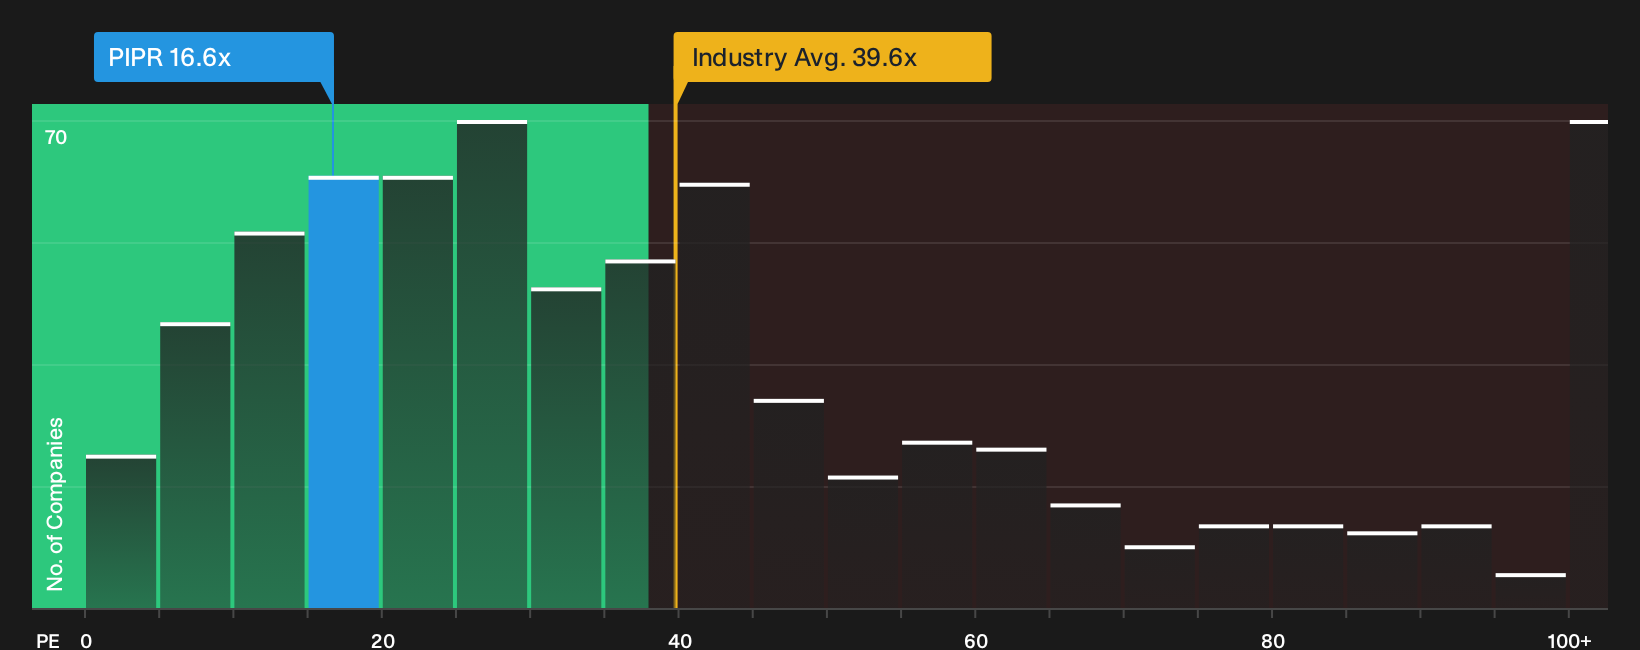
The first story around Piper Sandler Companies centers on a fair value of $88.13, based on analyst forecasts. A second lens offers a different perspective. On a P/E of 16.6x, the shares trade below the US Capital Markets industry at 39.6x and below peers at 20.7x, yet above a fair ratio of 13.9x.
That gap suggests the market already assigns Piper Sandler Companies some premium versus its own history, even while it trades at a discount to sector and peer averages. The question is whether earnings quality and growth justify remaining above that 13.9x fair ratio, or if the multiple could move closer to it.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Piper Sandler Companies can feel confusing. Give yourself an edge by checking the underlying data and weighing both sides of the story. To see the balance of potential upsides and flagged issues in one place, review the 4 key rewards and 1 important warning sign.
Looking for more Piper Sandler Companies investment ideas?
If you stop your research with Piper Sandler Companies, you risk missing other opportunities that fit your style and could round out your portfolio.
- Target potential upside by scanning a curated set of high quality undervalued opportunities through the 29 high quality undervalued stocks.
- Prioritise resilience and sleep-at-night holdings by reviewing a 30 resilient stocks with low risk scores that aims to keep downside in focus.
- Hunt for off-the-radar potential by checking a 7 elite penny stocks with strong financials that screens for stronger financial underpinnings than the usual microcap crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com