


Constellation Brands has seen its share price fall over several timeframes, and that pullback puts fresh focus on whether the current valuation still lines up with the earnings investors are paying for. With the stock drifting lower, the key issue is what the recent price now implies about the strength and durability of its profit base.
- Over the past 3 years the share price has declined 49.0%, which raises the question of whether the market is reassessing what its earnings are worth.
- The business still leans heavily on branded alcoholic beverages, so long term earnings power may depend on how consistently it can convert that franchise strength into cash flow after marketing, production, and distribution costs.
- The analysts covering Constellation Brands have run their own numbers. See what analysts think Constellation Brands's shares could be worth.
For investors, the debate is whether Constellation Brands' current share price around US$122.45 is adequately supported by the earnings the company is generating today.
If you want context on whether Constellation Brands' earnings multiple still stacks up, it can help to line it up against a wider set of 29 high quality undervalued stocks
Does Constellation Brands Look Undervalued on Earnings?
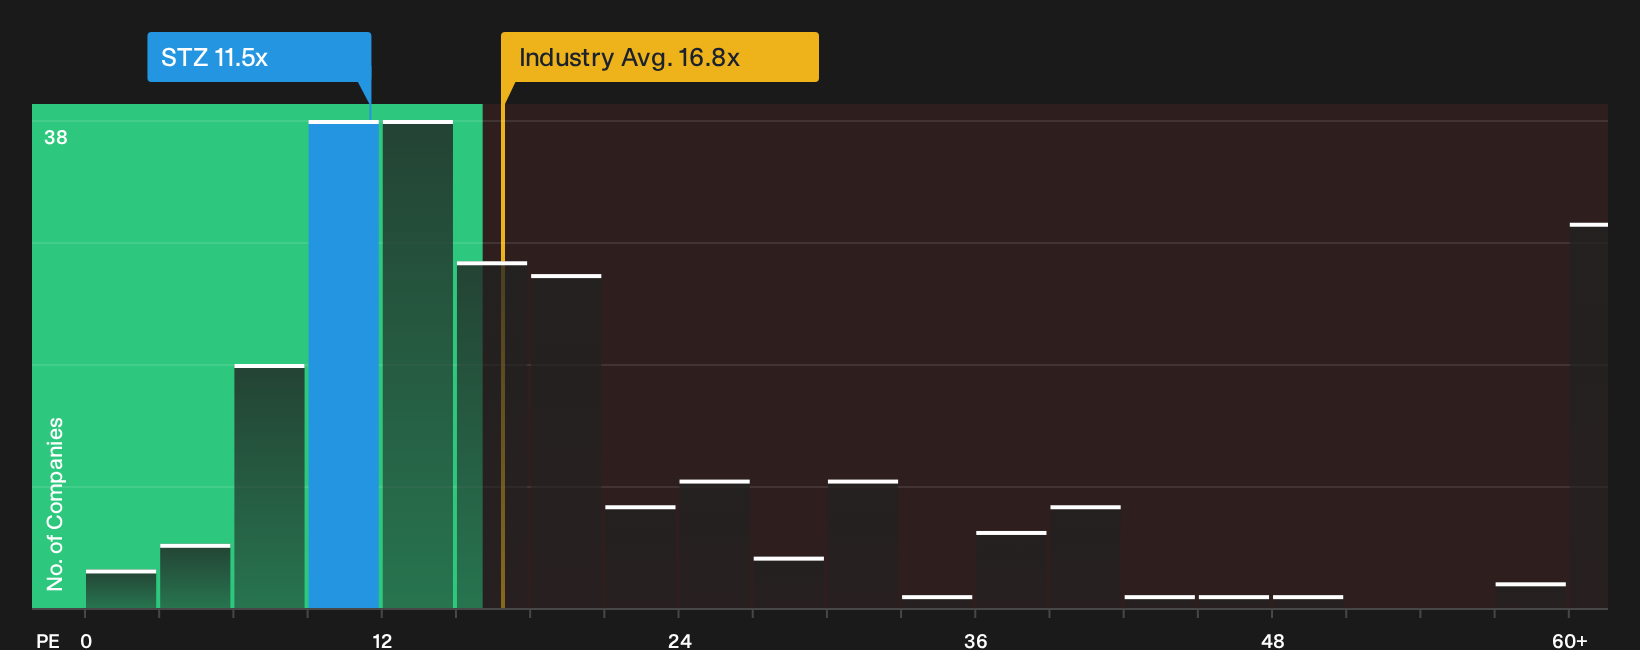
The P/E ratio suits Constellation Brands because earnings remain the main anchor for how investors value the business today. On this measure, the stock trades on a P/E of 11.5x, which is lower than both the broader beverage industry at 16.8x and the peer group average of 22.4x. For a company still driven by branded alcoholic drinks, that gap indicates the market is not paying the same headline earnings multiple as it does for many competitors.
The fair P/E that would be expected once factors such as margins, scale, industry position and risk are accounted for sits above the current 11.5x level. This suggests the shares screen as undervalued on this specific framework. Any assessment still needs to weigh how durable Constellation Brands' earnings base is, how much reinvestment is needed to support the brand portfolio, and how sensitive profits are to shifts in consumer demand. Explore the numbers behind Constellation Brands's P/E valuation.
The Constellation Brands Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Constellation Brands valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price, and each one presents fair value as a clear thesis about the business that you can revisit over time as new information comes through.
One of the top community narratives on Constellation Brands: 28% undervalued
"The company plans to generate approximately $9 billion in operating cash flow and $6 billion in free cash flow from fiscal '26 to fiscal '28..."
Discover why this Narrative puts Constellation Brands at 28% undervalued.
One more question on Constellation Brands that could shift how you see it
Valuation tells you what investors pay, but the people setting priorities and the way their pay packets are structured often explain why the business runs the way it does. See who runs Constellation Brands and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com