


- Portland General Electric has submitted a temporary shoring and roof demolition package to the Federal Energy Regulatory Commission for the River Mill powerhouse. The filing covers planned work through March 2027 following a prior generator incident at the Clackamas River Hydroelectric Project.
- The filing highlights near term operational and construction risks, because timely federal approval is needed for winter weatherproofing and to support the safe progression of the roof remediation program at a key hydro asset.
- This development may affect how Portland General Electric's investment narrative is viewed in light of the FERC reviewed roof remediation plan.
Compare Portland General Electric's hydro-focused profile with a curated 37 power grid technology and infrastructure stocks that could also be sensitive to regulatory approvals and infrastructure upgrade timelines.
Portland General Electric Investment Narrative Recap
For Portland General Electric, the long term belief is that Oregon's electrification plans and industrial and data center demand keep its integrated utility model relevant while it pours capital into generation, grid upgrades, and clean energy projects. The River Mill roof remediation fits into that picture as maintenance on a key hydro asset rather than a new growth lever.
In the near term, the main catalyst is still execution on grid modernization, renewables procurement, and business transformation that analysts expect to support earnings and revenue expansion. The biggest risk remains heavy capital needs and regulatory cost recovery limits. The River Mill plan looks operationally important but not financially defining unless delays or overruns compound broader project pressures.
With no other fresh announcements tied directly to this incident, the most relevant reference point is the broader clean energy and grid investment plan already in motion for Portland General Electric. Those programs rely on constructive regulation and timely approvals. The expedited FERC review request for River Mill shows how tightly project timing and regulatory processes are linked.
For you as a shareholder, the link is simple. Any slowdown in approvals or unplanned hydro remediation costs would sit on top of existing execution risks around renewables integration, storage, and large capital programs. The Clackamas work therefore slots into the same bucket as wider project delivery, rate case outcomes, and maintenance of financial flexibility.
Portland General Electric's narrative projects $4.3b revenue and $515.2 million earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about $264 million from $251.0 million today.
Uncover why Portland General Electric's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
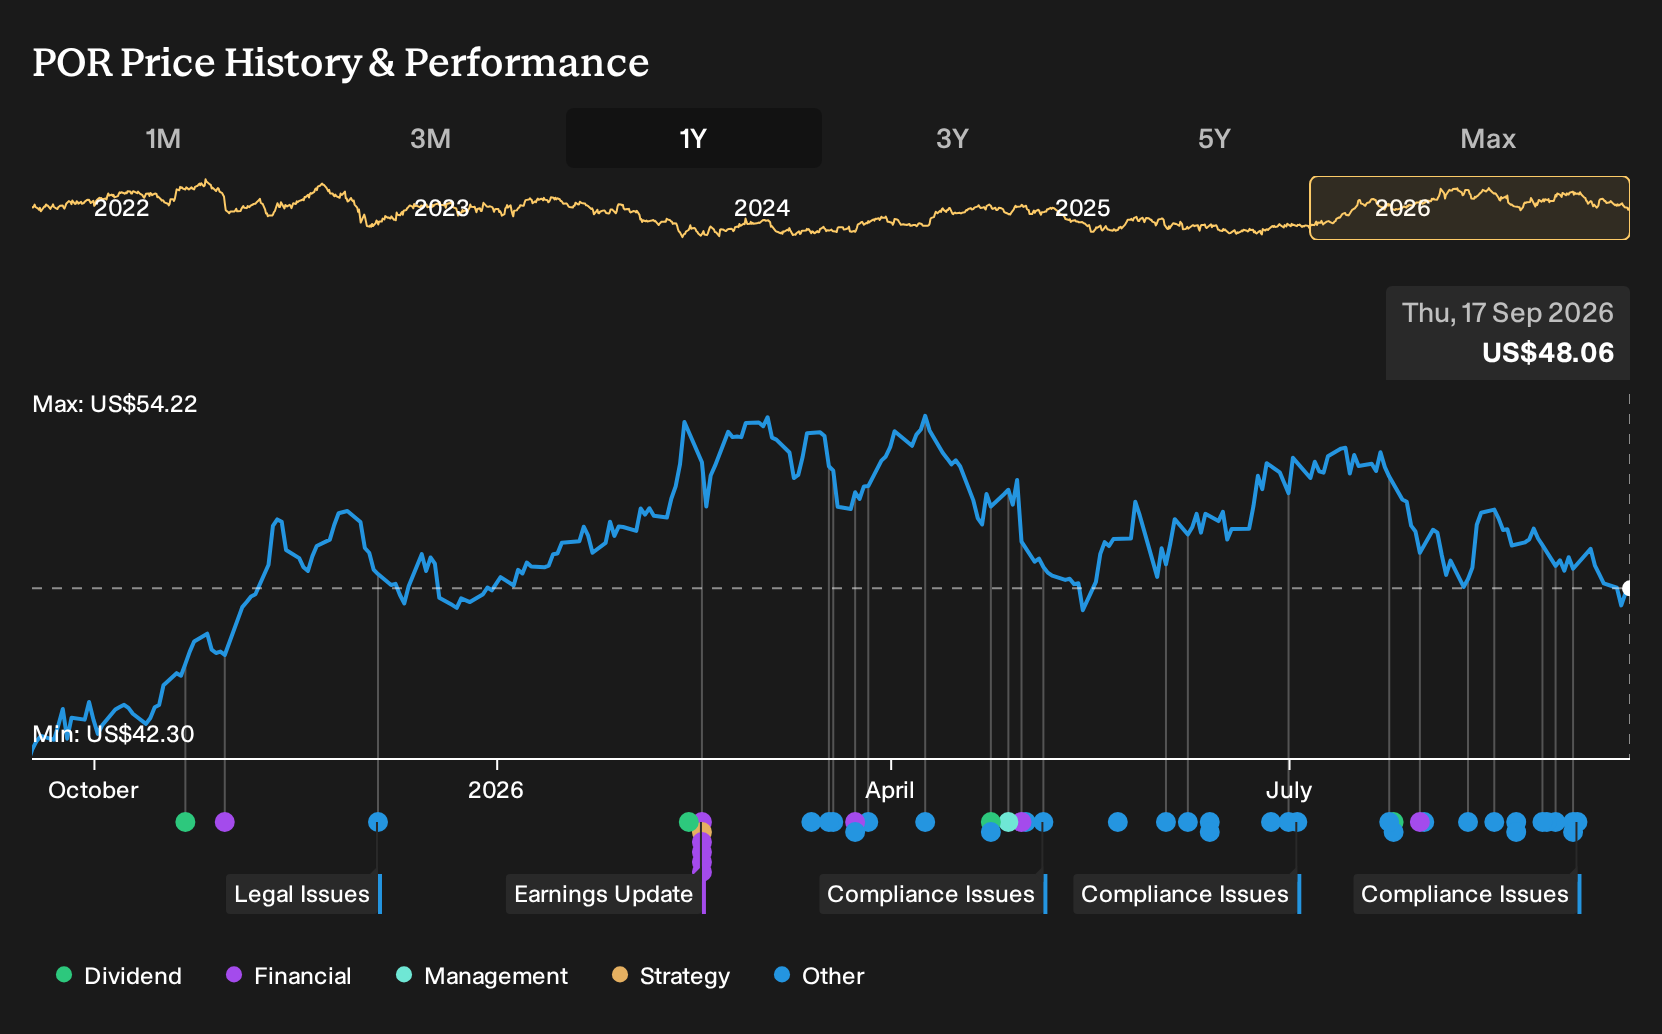
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between $39.14 and $54.07, which already shows how far retail views on Portland General Electric can spread. Set that against the fresh FERC roof remediation filing, where timing, cost control, and regulatory follow through could all shift how you and other investors reassess those prior forecasts.
Explore 3 other Portland General Electric fair value estimates, including one that suggests potential upside of up to 13% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider forming your own view.
- A great starting point for your Portland General Electric research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Portland General Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Portland General Electric's overall financial position at a glance.
Looking For More Ideas Beyond Portland General Electric?
If you want to cross check Portland General Electric against other potential opportunities, the Simply Wall St Screener can help you widen your watchlist without losing focus on quality or risk.
- If capital preservation is your priority, consider a group of resilient businesses by scanning through the 30 resilient stocks with low risk scores in a single pass.
- For investors hunting for quality at a reasonable price, it can be useful to line up companies on a 29 high quality undervalued stocks based on both fundamentals and cash flows.
- Income focused readers who care about stability and yield may want to compare Portland General Electric with a curated 6 dividend fortresses that screens for payout strength and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com