


- Everest Medicines announced that its subsidiary Everest Medicines China signed a Strategic Cooperation Framework Agreement with Hasten Biopharmaceutical covering supply, distribution, manufacturing and commercialization of multiple products in the PRC through to at least 2028.
- The framework sets sizeable annual transaction caps, introduces several commercial and manufacturing models, and aims to use Everest Medicines' planned GSP distribution platform to work with Hasten's product portfolio across China.
- This agreement may influence how investors view Everest Medicines' overall investment narrative in connection with its China distribution and manufacturing framework.
Scan other China-focused distributors and contract partners moving on similar themes with our hand picked list of solid balance sheet and fundamentals (196 results) that may support scaled supply and commercialization plans.
Everest Medicines Investment Narrative Recap
To own Everest Medicines, you need to buy into a China and Asia focused commercial roll out for NEFECON, VELSIPITY and a broader late stage pipeline, while the group is still loss making and investing heavily. The Hasten framework mainly speaks to execution, not a new product story, so it does not replace regulatory or uptake milestones as near term drivers.
The more immediate swing factor remains whether current launches can scale fast enough to cover R&D and commercial spend before further equity funding is needed. The biggest operational risk still sits in pricing and reimbursement pressure in China, plus concentration around NEFECON performance and any product specific setbacks.
The new framework with Hasten links most directly to Everest Medicines’ push to localize manufacturing, widen hospital reach and use its planned GSP platform to support multiple therapies. It connects to the same thesis as NRDL coverage and hospital expansion for NEFECON and future approvals for VELSIPITY, which are important to building recurring revenue from marketed drugs.
Hasten’s role across commercialization services, distribution and potential manufacturing adds another layer of execution to track. Investors will likely watch whether annual caps translate into meaningful throughput without squeezing margins through pricing, and whether these models reduce operational risk or simply increase complexity while the business remains unprofitable and reliant on capital markets.
Everest Medicines' current earnings are a loss of CN¥297.8 million, and consensus forecasts point to earnings of CN¥878.3 million by 2029. This implies an earnings swing of about CN¥1.18 billion, alongside analyst assumptions for 48.8% yearly revenue growth and projected 2029 revenues of CN¥5.6 billion.
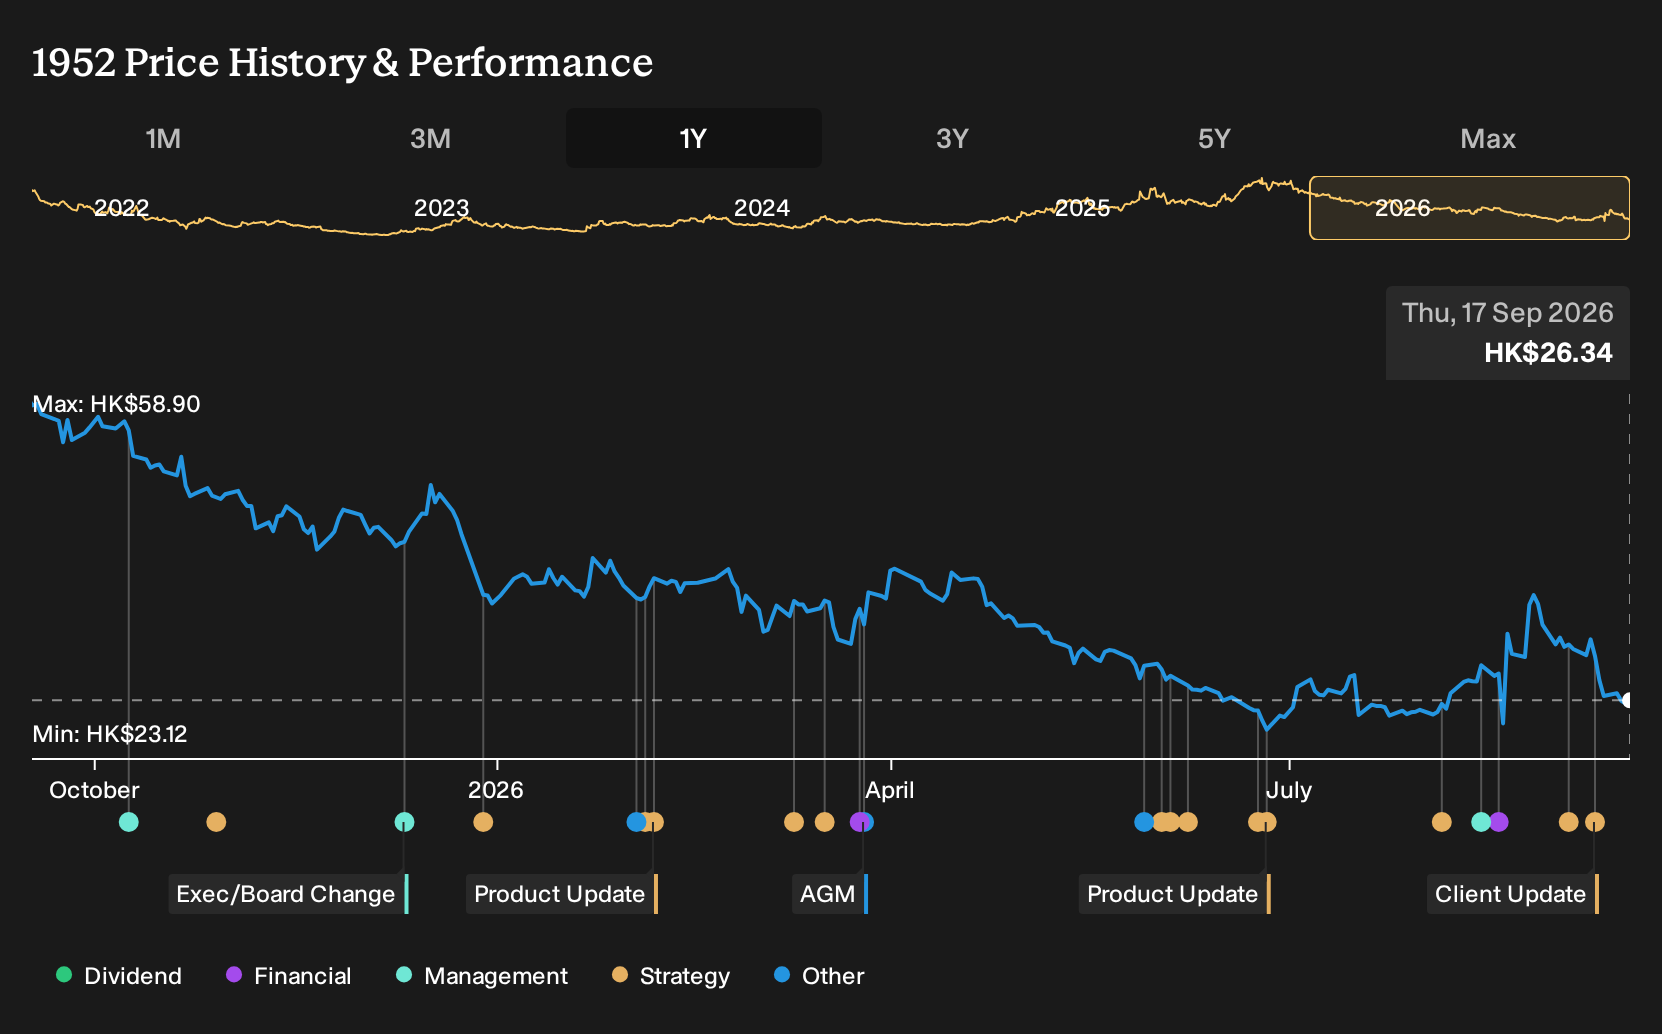
Uncover why Everest Medicines' fair value indicates a 60% potential upside to its current price, a gap Everest Medicines investors may see close sooner than expected.
Exploring Other Perspectives
One alternate view on Everest Medicines leans hard into the upside from faster profitability. The most optimistic analysts were already modelling revenue of CN¥8.2b and earnings of CN¥1.3b by 2029, versus the more cautious CN¥5.6b and CN¥878.3m. This new Hasten agreement could nudge those narratives in very different directions, so it is worth exploring both.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Everest Medicines research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Everest Medicines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everest Medicines' overall financial health at a glance.
Looking For More Investment Ideas Beyond Everest Medicines?
If the Everest Medicines story has you thinking about portfolio balance and fresh opportunities, it can help to line it up against other businesses with different risk and return profiles.
The Simply Wall St Screener lets you scan a wide universe of stocks through clear, fundamentals driven filters, so you can quickly shortlist ideas that actually fit your goals instead of trawling through tickers at random.
- For investors who want potential upside without ignoring quality, start with companies that combine strong fundamentals and attractive pricing using our 173 high quality undervalued stocks.
- If capital preservation matters just as much as growth, narrow your search to steadier businesses by scanning a set of 227 resilient stocks with low risk scores that score well on resilience.
- When you want sturdier balance sheets supporting long term plans, focus on companies with healthier gearing and liquidity by reviewing the list of solid balance sheet and fundamentals (196 results) available in the screener.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com