


Philip Morris International (PM) recently raised its full year 2026 reported diluted EPS guidance to a range of $7.28 to $7.43, reflecting currency effects. Investors now have a refreshed earnings anchor for evaluating the stock.
The higher 2026 earnings guide lands while Philip Morris International’s share price is trading at $190.48. The 90 day share price return of 6.77% and the year to date share price gain of 18.83% point to building momentum, backed by a 1 year total shareholder return of 22.02% and triple digit total shareholder returns over 3 and 5 years.
Spot momentum in Philip Morris International and then widen your radar across curated income plays and defensives with the 6 dividend fortresses.Philip Morris International now pairs refreshed EPS guidance with a share price near record territory. Do you lean into the momentum or wait and hope valuation gives you a second chance?
Most Popular Narrative: 6.5% Undervalued
Philip Morris International is being framed as modestly undervalued, with a fair value of $203.80 sitting above the recent $190.48 close, and that gap rests heavily on how the smoke free pivot plays out.
The accelerating global adoption of smoke-free alternatives, driven by increasing health awareness and regulatory moves away from combustibles, is associated with strong double-digit volume and margin growth in PMI's IQOS, ZYN, and VEEV platforms. This secular shift is described as enabling the company to capture new consumer segments, expand its addressable market, and structurally boost net revenues and operating margins over time.
See why 93 investors see Philip Morris International as 7% undervalued.
Behind that narrative sits a fair value estimate of $203.80, built using an 8.05% discount rate and analyst assumptions for mid single digit annual revenue growth and higher profit margins over the next few years. The result is a view that the current share price reflects much of the expected earnings path already, with only a small margin between price and the implied valuation.
The same framework also leans on improving profitability, with net profit margin assumptions moving from 25.5% today to just above 31% in a few years, and a future P/E of roughly 26x on projected 2029 earnings. That multiple is higher than the current level for the broader tobacco peer group, so the thesis depends on Philip Morris International continuing to outpace the sector on earnings quality and smoke free execution rather than simply tracking the industry average.
Result: Fair Value of $203.80 (UNDERVALUED)
Still, the Philip Morris International story can be upset if smoke free momentum slows, or if tighter taxes and regulation squeeze both volumes and profitability.
Find out about the key risks to this Philip Morris International narrative.
Another View: Philip Morris International Through The P/E Lens
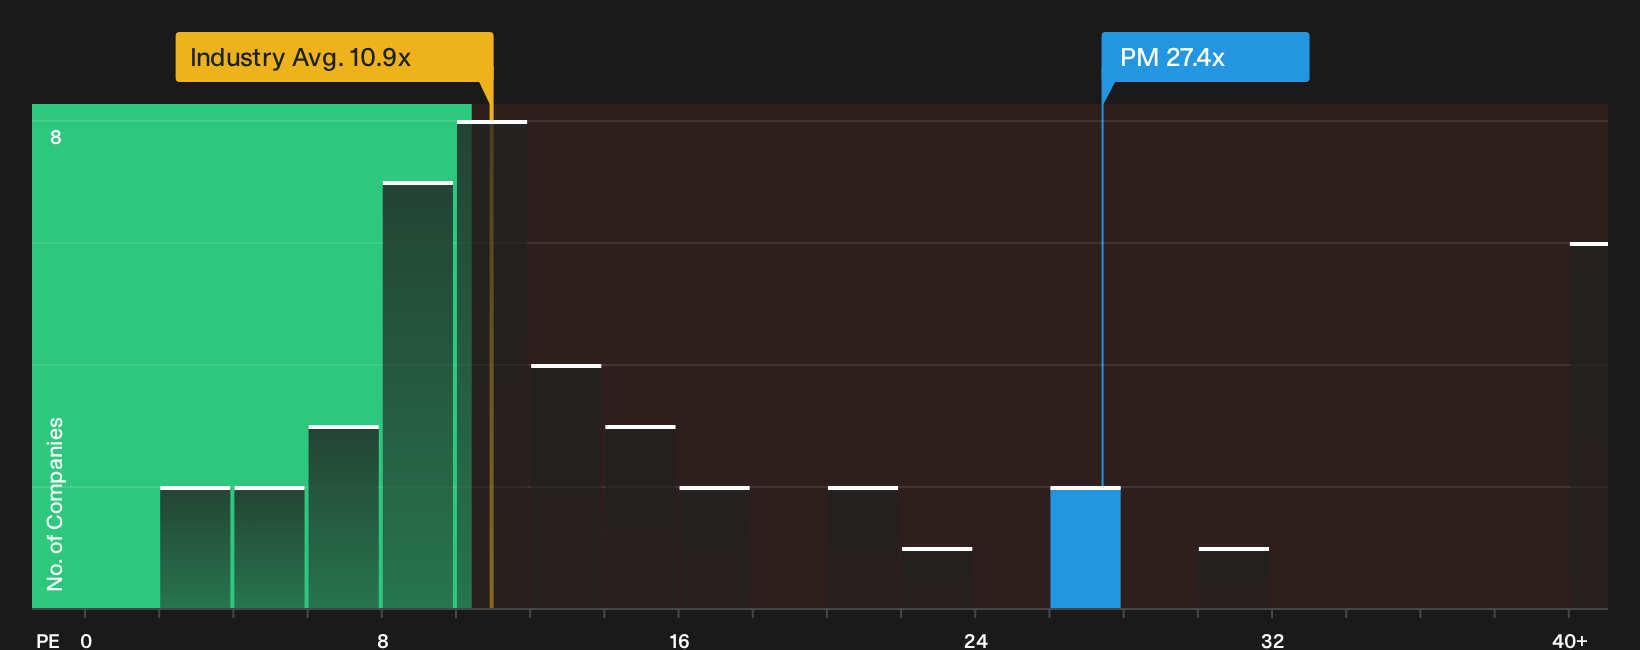
There is a different read on Philip Morris International once the focus shifts from fair value models to the simple P/E ratio. The stock trades at 27.4x earnings compared with a 22.4x peer average and 10.9x across the global tobacco group, while the fair ratio is 27.3x.
That gap points to investors already paying up for the smoke free story, with only a tiny cushion versus the fair ratio if sentiment cools. Does this richer multiple signal conviction worth paying for, or limited room for error if the next few earnings prints disappoint?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed reactions to Philip Morris International are clear in the data, with both concerns and bright spots in play. Weigh the trade off yourself, then drill into the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Philip Morris International?
If the Philip Morris International setup has you thinking harder about positioning, now is the moment to widen your opportunity set and test fresh ideas.
- Target sturdier portfolios by screening for resilient companies using the 30 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which candidates emerge from the 16 high quality undiscovered gems.
- Rebalance toward financial strength by scanning our list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com