


NeoGenomics has been on a sharp run, with the share price moving far ahead of where it started a year ago. That kind of surge puts a spotlight on a simple question for investors who focus on fundamentals, whether the current US$19.89 price is supported by the company’s sales.
- NeoGenomics has returned 130.7% over the past year, which makes it important to ask how much of that move is grounded in its revenue base rather than just sentiment.
- The business model relies on scaling its testing volume over a relatively fixed cost base, which can increase the importance of each extra dollar of sales for future profitability and cash generation.
- The analysts covering NeoGenomics have run their own numbers. See what analysts think NeoGenomics's shares could be worth.
The issue now is whether NeoGenomics’ current market value can be justified by the level of sales the company is generating today.
If you want more ideas built around sales driven cases like NeoGenomics, a focused stock screen can be a useful second step in your research, starting with 29 high quality undervalued stocks.
Has NeoGenomics Run Too Far on Sales?
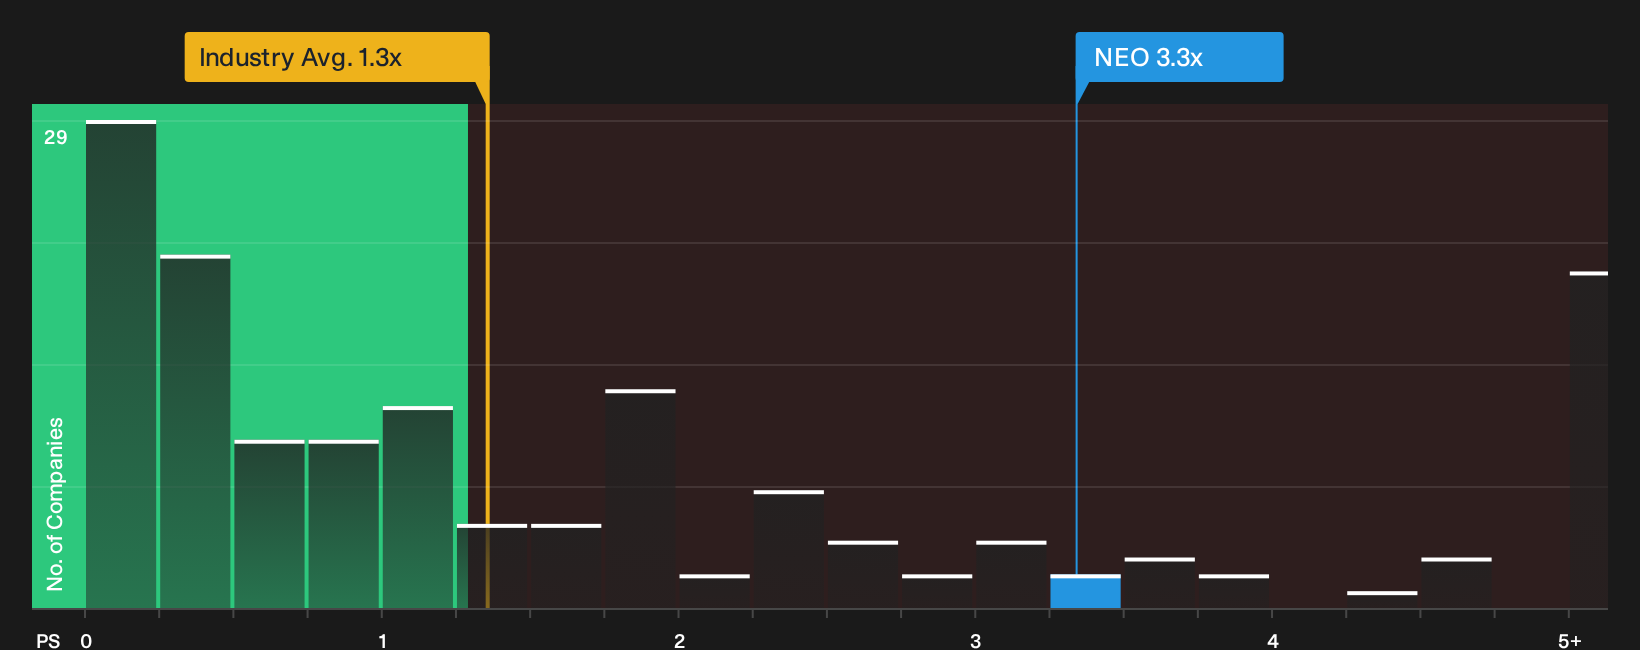
P/S suits NeoGenomics because the business is still working through losses, so revenue gives a cleaner anchor than P/E. On this measure, the stock trades on a P/S of 3.3x, which is more than double the Healthcare industry average of 1.3x and above the peer group at 1.4x. That indicates the market is paying a richer tag for each dollar of NeoGenomics’ sales than for many similar businesses.
The Fair Ratio, which adjusts the benchmark for NeoGenomics’ own size, margins, sector and risk profile, points to a lower P/S than the current 3.3x. That gap implies the shares screen as overvalued on this framework, so anyone building a position would need to be comfortable that the quality and durability of future revenue can support a premium to sector and peer pricing. Explore the numbers behind NeoGenomics's P/S valuation.
The NeoGenomics Narrative: What Would Justify Today's Price?
NeoGenomics’ valuation question introduces the role of Simply Wall St Narratives. These map out what would need to happen to revenue growth, margins and eventual earnings power for the stock to be worth materially more or less than today’s share price, and are available on the company’s Community page.
Each scenario is built on its own set of fair value assumptions rather than a single multiple or model output, so you can track how those expectations line up with actual results over time.
NeoGenomics attracts two very different reads, with one group of investors seeing room for upside while another focuses on execution and competitive risks.
Bull case: 36% undervalued
"By integrating a single LIMS, accelerating automation, and driving digital pathology adoption, the company stands to unlock significant operational leverage..."
Discover why this Narrative puts NeoGenomics at 36% undervalued.
Bear case: 24% overvalued
"Persistent weakness and volatility in the pharma services segment, with revenues declining 26 percent year-over-year due to reduced demand from pharmaceutical and biotech clients..."
Explore why this Narrative puts NeoGenomics at 24% overvalued.
NeoGenomics’ price is only one piece of the decision
Valuation work explains what the market is paying for NeoGenomics today, but the research also flags company specific concerns that some investors may want to review before going further. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com