


- Saab AB reported that Sweden's Defence Material Administration placed a SEK 2,900 million order for concept work on future fighter systems running from 2026 to 2028, with options extending to 2029 and 2030.
- The programme focuses Saab's resources on technologies such as autonomy, systems integration and advanced demonstrators, which are directly linked to long-term capability building for Sweden's air combat systems and Saab's future offering mix.
- The next step is to consider how Saab's investment narrative could be influenced by this SEK 2,900 million future fighter systems contract.
Compare Saab's future fighter push with other defence and aerospace opportunities by scanning our hand picked 37 power grid technology and infrastructure stocks that could benefit from long-term infrastructure and security spending themes.
Saab Investment Narrative Recap
To own Saab, you need to believe in long duration defence budgets, steady order intake and the firm’s ability to turn heavy R&D into exportable products. The SEK 2,900 million future fighter concept contract fits that story, but the effect on near term results is likely incremental rather than transformational.
The key short term swing factor still appears to be execution on the existing backlog, alongside managing cost inflation and capacity build out. The largest risk remains the reliance on government spending and policy choices. Any slowdown in awards or contract timing could matter more than this single fighter systems order.
The management reshuffle around Aeronautics and Dynamics is the announcement that most closely ties into the fighter systems news. Putting Marcus Wandt, with his pilot and test pilot background, in charge of Aeronautics aligns the leadership bench with the technical complexity of future fighter programmes.
For you as an investor, this raises practical questions about execution quality and internal coordination rather than strategy shifts. Leadership transitions can create friction if priorities or processes change. Progress on concept milestones, margin discipline in Aeronautics and stable customer relationships will be the cues to watch relative to the existing catalysts and risks.
What The Fighter Programme Means For Saab's Numbers
Saab's narrative projects SEK 148.1b revenue and SEK 13.3b earnings by 2029. This lines up with analyst assumptions of 18.9% yearly revenue growth and implies an earnings increase of about SEK 6.2b from SEK 7.1b today.
Uncover why Saab's fair value is in line with its current price.
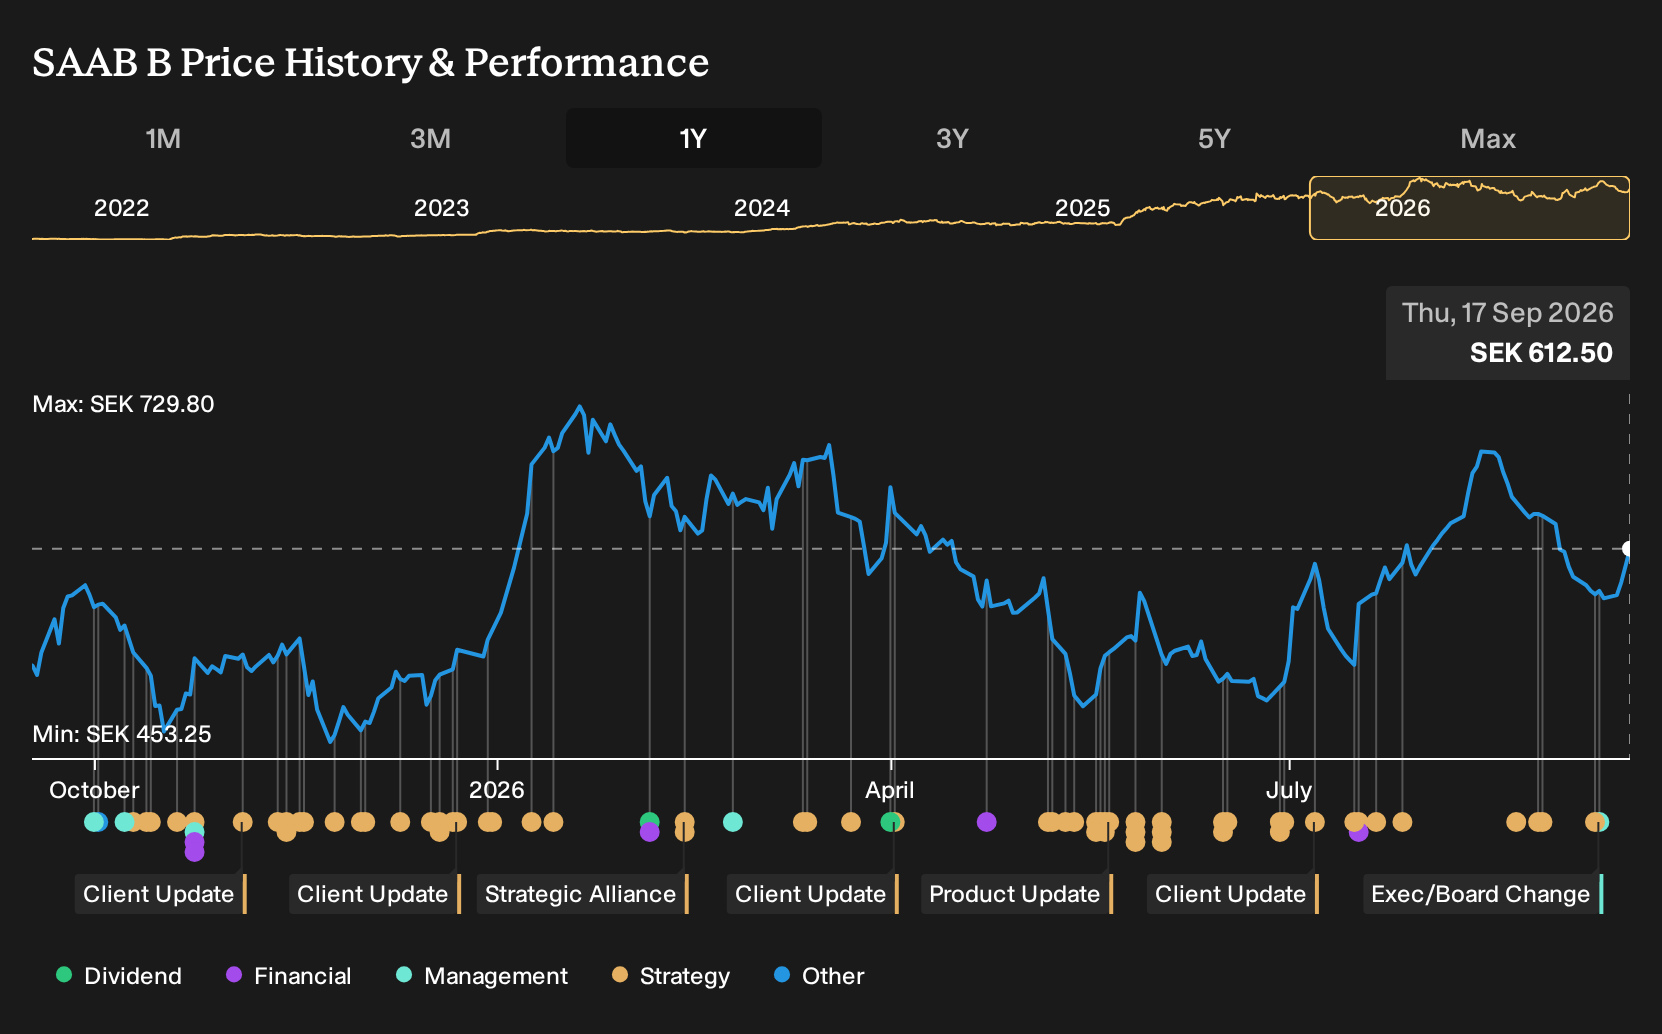
Exploring Other Perspectives
One alternate angle you might consider is execution risk. The most optimistic analysts already pencilled in revenue of about SEK 153.9b and earnings of SEK 14.6b by 2029 before this Saab fighter and management news. That is a much sharper curve than consensus, and these new developments could either reinforce or challenge those expectations.
Explore 5 other Saab fair value estimates, including one that suggests as much as 24% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Saab research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Saab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saab's overall financial health at a glance.
Looking For More Ideas Beyond Saab?
If this Saab story has sharpened your thinking about defence exposure but you want a broader watchlist, the Simply Wall St Screener can surface other stocks that match the kind of risk and quality profile you have in mind.
- If capital preservation is high on your list, focus on resilient businesses with stronger balance sheets and fewer red flags through a 227 resilient stocks with low risk scores.
- For investors who care most about financial strength and flexibility, a list of solid balance sheet and fundamentals (196 results) can help surface companies that are better equipped to handle shocks.
- If the goal is to find lesser known opportunities with sound fundamentals, use a 618 high quality undiscovered gems to spot potential candidates before they are widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com