


MDA Space (TSX:MDA) just used the World Space Business Week stage to roll out its full MDA CHORUS Earth observation portfolio, marking a key milestone ahead of the constellation launch later this year.
Recent trading reflects that story. The share price has climbed 4.41% over the last day and 6.18% over the past week, even after a 30 day share price return that declined 10.36% and a 90 day share price return that fell 28.25%. At the same time, the year to date share price return of 53.49% and 3 year total shareholder return of roughly 3x both point to strong longer term momentum that recent product news like MDA CHORUS and MDA AURORA BLACK is helping to test in the short term.
Scan beyond MDA Space and compare this kind of space infrastructure story with a curated list of other potential compounders in our 9 high quality undiscovered gems that are still flying under most radars.
After a CA$42.41 close and a share price that has already roughly tripled over three years, is most of MDA Space’s payoff now in the rear-view mirror, or is it still ahead based on the numbers investors are paying today?
Most Popular Narrative: 37% Undervalued
On the most followed narrative, MDA Space screens as materially cheaper than its CA$67.27 fair value estimate, even after closing at CA$42.41, which puts a spotlight on what could justify that gap.
The ramp-up of large LEO constellation contracts, including the landmark $1.8 billion EchoStar direct-to-device satellite order with options to expand, and multiple pipeline opportunities in broadband, defense, and IoT, is expected to drive robust multi-year revenue growth as global demand for satellite connectivity accelerates.
Expansion of MDA's Montreal facility will enable high-volume digital satellite production (targeting up to 2 satellites a day by late 2025 and scalable further), positioning the company to capitalize on rising market demand and to increase operating leverage, supporting higher EBITDA margins over time.
See why 78 investors see MDA Space as 37% undervalued.
Result: Fair Value of CA$67.27 (UNDERVALUED)
Still, MDA Space’s heavy capital spending and reliance on converting a US$40b pipeline into firm contracts could quickly challenge that narrative of being 37% undervalued.
Find out about the key risks to this MDA Space narrative.
Another View on MDA Space’s Valuation
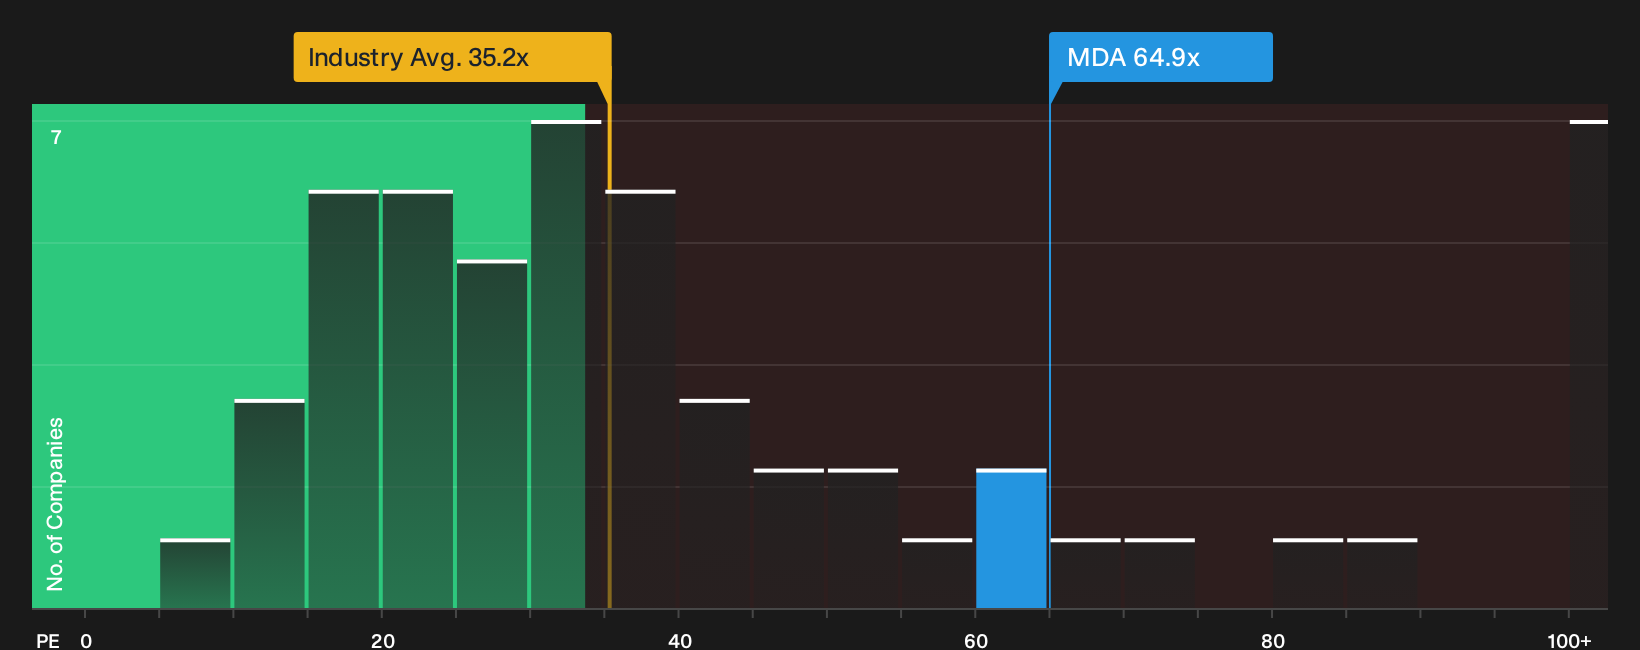
The earlier fair value story for MDA Space leans on growth forecasts and analyst targets. A different lens looks at what investors are actually paying today. On a P/E of 64.9x, the shares trade well above the fair ratio of 54.3x, the North American Aerospace & Defense average of 35.2x, and the peer average of 41.3x. This points to less margin for error if expectations change.
That gap raises a blunt question for any holder: Is this a long runway being appropriately priced, or is the market already paying up for a lot of good news that still needs to be delivered in contracts, cash flow, and execution?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these around MDA Space rarely stay unresolved for long, so pressure is on you to weigh both sides quickly and decide how you feel about the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MDA Space?
You have already done the work on MDA Space, so do not stop short when there are more focused stock ideas waiting in front of you.
- Target resilient balance sheets by running your filters through a list of solid balance sheet and fundamentals (7 results) that highlights companies with financial strength at the core of their story.
- Identify potential mispricing by checking a 3 high quality undervalued stocks that concentrates candidates with strong fundamentals priced below their assessed worth.
- Focus your search on steadier compounding by reviewing a 1 dividend fortresses that highlights high yielders designed for investors who want consistent income.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com