


- JCDecaux secured the exclusive 2m² outdoor advertising contract in Düsseldorf through a competitive tender, covering public areas and Rheinbahn bus and tram stops, which reinforces its operational role in this German city.
- The renewed exclusivity on compact street furniture directly supports JCDecaux's focus on recurring municipal contracts and transit advertising, areas that influence asset efficiency and contract-driven revenue visibility.
- We will now assess how JCDecaux's renewed exclusive 2m² Düsseldorf contract could interact with the existing investment narrative on long-term contracts.
See how JCDecaux’s renewed Düsseldorf deal compares with peers winning long-term city contracts by reviewing the curated list of solid balance sheet and fundamentals (196 results).
JCDecaux Investment Narrative Recap
To own JCDecaux, you need to believe the out of home format keeps its relevance as brands juggle budgets between physical space and online channels, and that long term street furniture and transport contracts keep filling the pipeline for digital upgrades. The Düsseldorf renewal supports that contract thesis, although on its own it does not materially change the near term story.
For now, the key swing factor remains how efficiently JCDecaux converts its portfolio to higher margin digital and programmatic inventory while keeping capex near the targeted approximately 8% of sales. The biggest current risk is pressure on tender terms or delayed renewals if municipalities and transport authorities stay cautious on budgets.
With no other fresh announcements around the same time as the Düsseldorf award, the most relevant context is still JCDecaux's ongoing push into premium digital and data led formats. That operational focus sits behind analyst expectations for revenue growth of 6.9% a year and earnings growth of 4.31% a year, even if those forecasts trail the broader French market on profits.
For you as a shareholder, the question is whether a portfolio of exclusive, long term city and transport contracts, like Düsseldorf, can support that digital transition without squeezing free cash flow too hard. The risk is that higher capital spending, combined with tender competition and soft spots in markets such as China, crimps the payoff period on those investments.
What The Düsseldorf Contract Means Against JCDecaux’s Forecasts
JCDecaux's narrative projects €4.7b revenue and €361.7m earnings by 2029. This is based on assumed 8.1% yearly revenue growth and an earnings increase of about €34.9m from €326.8m today.
Uncover why JCDecaux's fair value is essentially aligned with its current price.
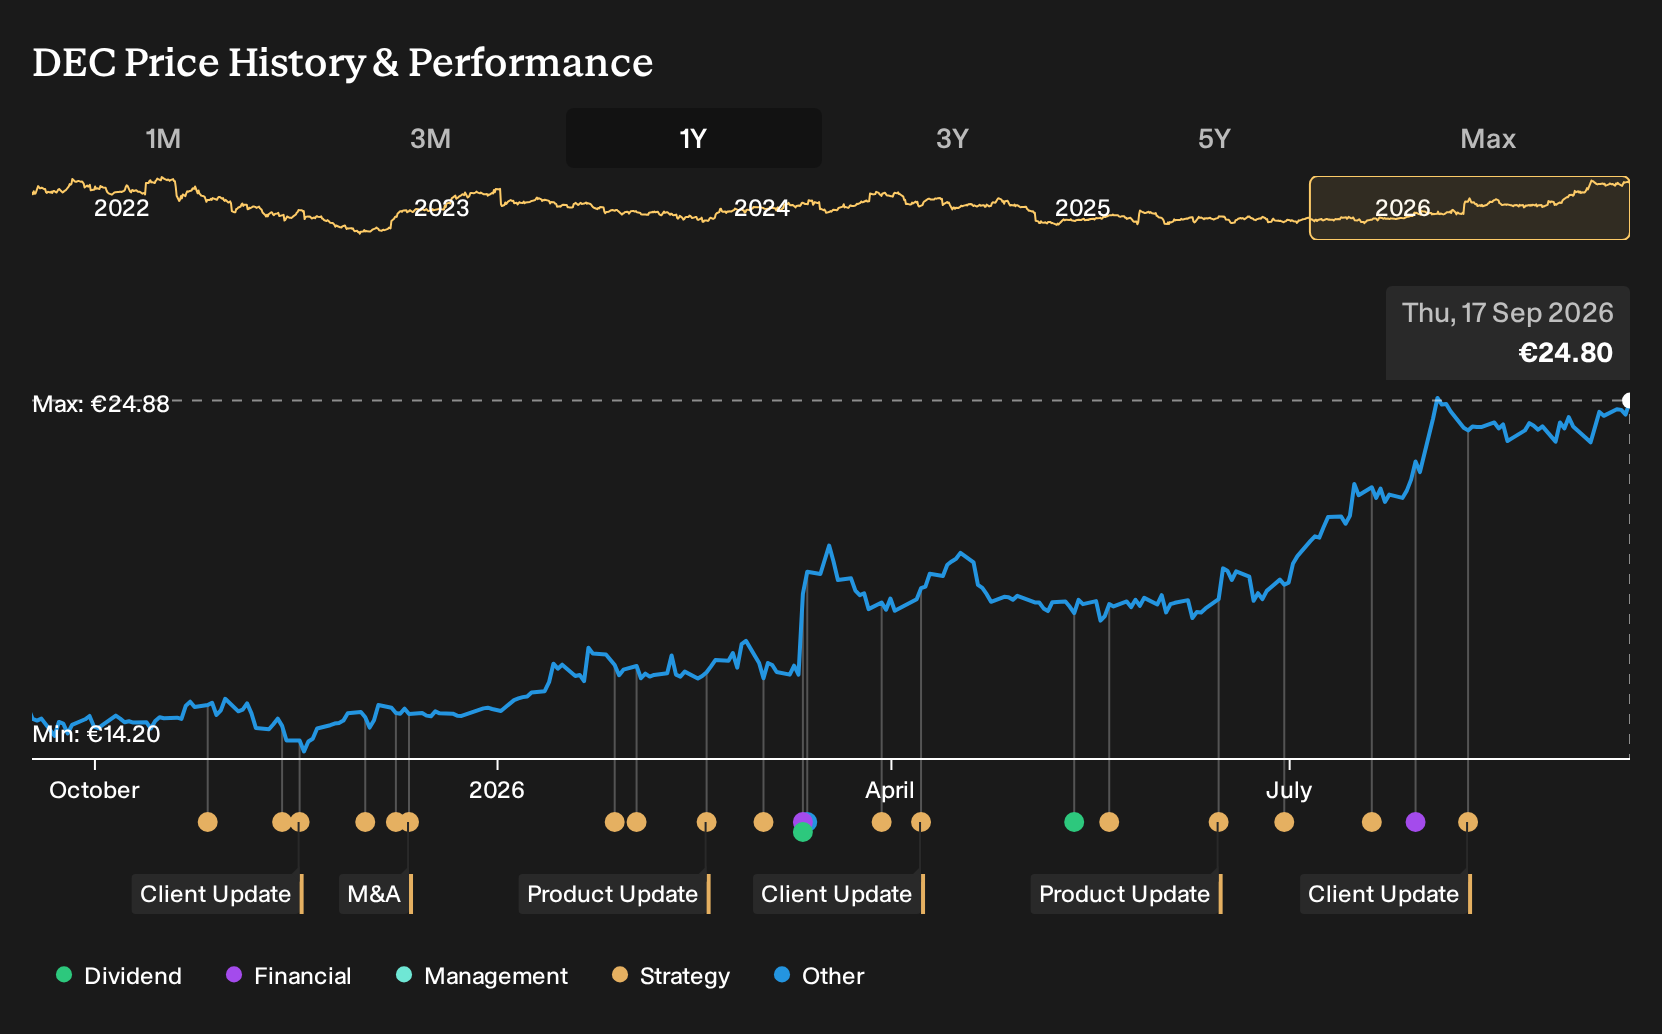
Exploring Other Perspectives
Some of the most optimistic analysts frame contracts like Düsseldorf as proof that JCDecaux could lean harder into digital and programmatic, with their pre news models already pencilling in 9.3% yearly revenue growth and about €410.9m in 2029 earnings. You can treat this fresh deal as a prompt to compare those upbeat assumptions with more cautious views.
Explore 3 other JCDecaux fair value estimates, including one that suggests potential upside of up to 35% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JCDecaux research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JCDecaux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JCDecaux's overall financial health at a glance.
Looking For More JCDecaux Investment Ideas?
If this JCDecaux story has you thinking about position sizing, risk and income streams, it can help to line it up against other businesses with different strengths. The Simply Wall St Screener lets you quickly scan for companies that match the kind of balance sheet quality, valuation profile or dividend focus you want to pair with a holding like JCDecaux.
- For investors who want potential mispricing alongside solid fundamentals, start with a curated group of 173 high quality undervalued stocks that may offer a different risk reward profile to JCDecaux.
- If capital preservation sits high on your checklist, compare JCDecaux with a 227 resilient stocks with low risk scores to see which businesses better fit a steadier approach.
- For those looking to broaden beyond JCDecaux with stronger financial footing, scan a list of solid balance sheet and fundamentals (196 results) and see which companies align with your comfort level on debt and cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com