


Subaru (TSE:7270) is back in focus after Subaru of America outlined pricing for the 2027 Forester Hybrid lineup and confirmed a new Wilderness Hybrid model, while also working with onsemi on next generation embedded power systems.
Those hybrid headlines land against a mixed price backdrop, with Subaru’s 7 day share price return of 4.90% and 90 day share price return of 10.08% contrasting with a year to date share price decline of 22.02% and a 1 year total shareholder return decline of 7.85%, even though the 5 year total shareholder return is up 58.55%. This indicates that recent momentum has improved after a weak stretch.
Compare Subaru’s hybrid push with other potential opportunities by scanning a curated set of 20 resilient stocks with low risk scores that aim for resilience alongside future-focused themes like electrification.
Subaru’s hybrid news has helped the share price bounce in the short term, yet the stock is still down for the year. Does that create a reasonable entry point now, or does it make a stronger case for waiting on potentially better terms?
Preferred P/E of 22.2x for Subaru: Is it justified?
Subaru’s last close at ¥2,686.5 sits on a P/E of 22.2x, which positions the stock on the richer side of the sector and raises the question of whether investors are paying a premium for its hybrid story and earnings profile or simply overpaying for near term momentum.
The P/E multiple compares the current share price with earnings per share, so a higher ratio usually reflects stronger profit expectations or a willingness to pay up for perceived quality. For an automaker with a large Automotive segment contributing ¥4,668,061m in revenue and additional earnings from Aerospace and Other operations, this valuation metric matters because it signals how the market is weighing that diversified income stream against current profitability.
Forecast data indicates earnings are expected to grow 19% per year, which is quicker than the wider JP market forecast of 8.8% per year. Revenue is projected to rise 2.8% per year, which is slower than both the JP market at 6.4% and a 20% high growth threshold. Profit margins currently sit at 1.8%, down from 6.4% last year. Return on equity is 3.1% with forecasts pointing to 7.2% in three years, and both figures are described as low. That mix of faster profit expansion, slower top line growth, and modest profitability can justify some uplift in P/E. However, it also caps how far the multiple might stretch before investors start questioning whether expectations have become too optimistic.
Compared with peers, Subaru looks expensive on several fronts. The stock’s P/E of 22.2x is above the peer average of 18x and well above the Asian Auto industry average of 13.9x, so the market is paying a clear premium versus sector benchmarks. Internal fair value work also points to a lower “fair” P/E of 17.1x, which suggests a level the valuation could move towards if sentiment cools or if earnings progress does not fully support the current pricing.
Explore the SWS fair ratio for Subaru.
Result: Price-to-earnings of 22.2x (OVERVALUED)
Still, Subaru could face real pressure if hybrid demand underperforms or if its 1.8% profit margin leaves little cushion against any earnings disappointment.
Find out about the key risks to this Subaru narrative.
Another View on Subaru’s Value
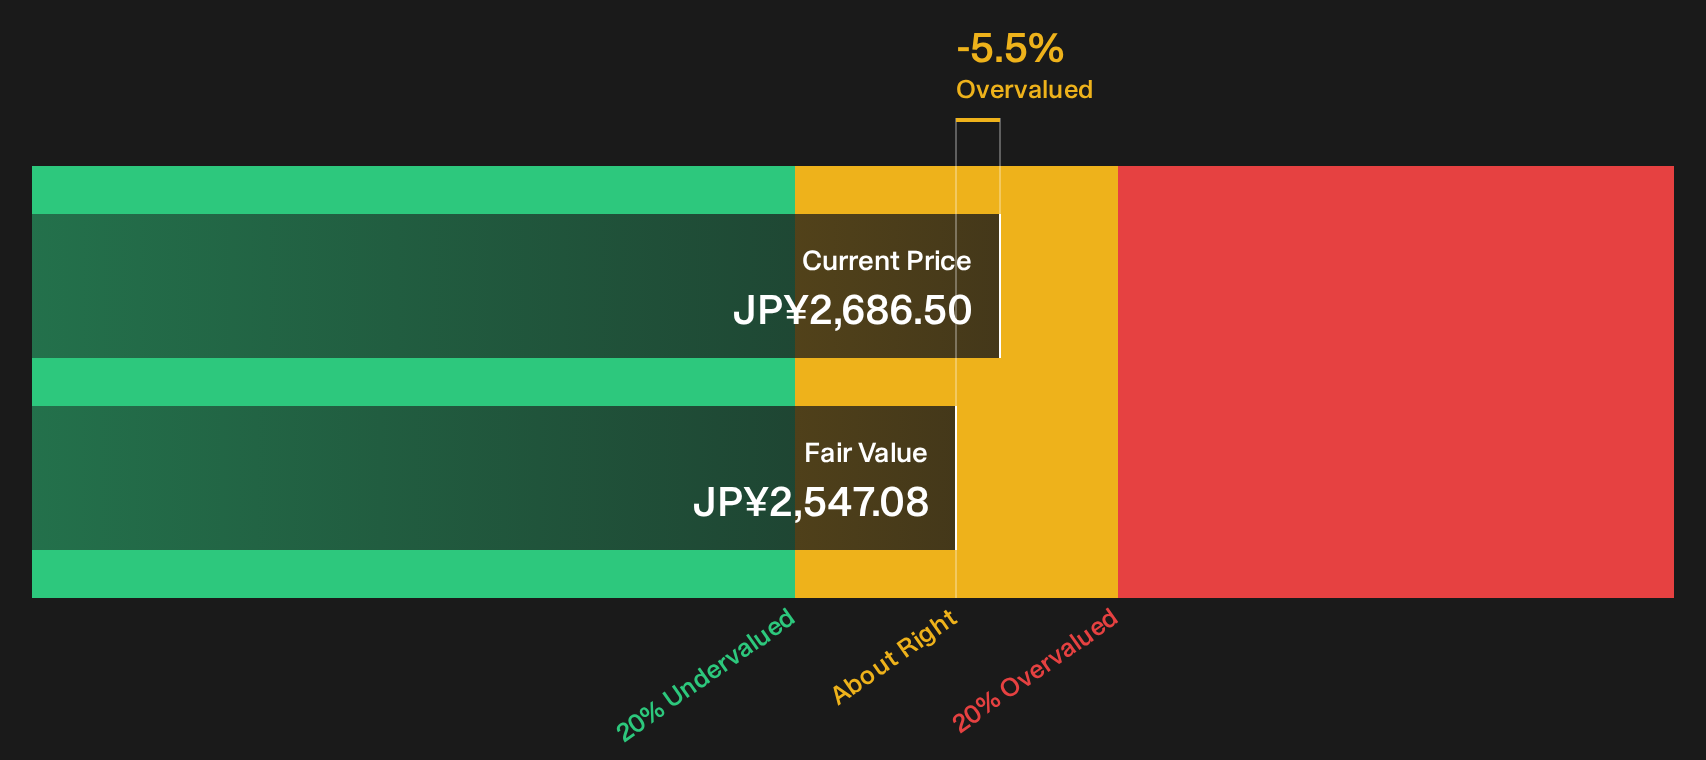
A different lens paints a similar picture. Subaru trades at ¥2,686.5 while our DCF model estimates the future cash flow value at ¥2,547.08. That gap points to a stock that screens as overvalued on cash flows as well as on earnings. The real question is whether the hybrid story can close that gap over time.
For investors who want to see how the cash flow assumptions stack up line by line, it is worth reviewing how the SWS DCF model approaches Subaru’s fair value today: Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Subaru for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Subaru’s hybrid push and valuation can feel messy, so move fast, pull up the numbers yourself and pressure test the story against the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Subaru?
If Subaru’s setup leaves you on the fence, broaden your watchlist with a few targeted stock pools that match different risk and return preferences.
- Target potential mispricing by scanning a 17 high quality undervalued stocks that couples quality fundamentals with price tags that may not fully reflect them yet.
- Strengthen your income focus by reviewing 14 dividend fortresses that aim to combine higher yields with business models built for consistency.
- Prioritize durability by filtering for a list of solid balance sheet and fundamentals (20 results) so you are not relying on fragile finances when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com