


Amylyx Pharmaceuticals (AMLX) drew fresh attention after signing long-term manufacturing arrangements for its avexitide drug substance with Bachem Americas and Polypeptide Group, alongside a scheduled appearance at Morgan Stanley’s Global Healthcare Conference.
The latest manufacturing agreements and conference appearance come against a backdrop of strong momentum in Amylyx Pharmaceuticals’ share price. The 90-day share price return is 116.59% and the year-to-date share price gain is 197.20%, while the 1-year total shareholder return of 156.15% and 3-year total shareholder return of 87.72% point to investors steadily repricing both growth prospects and risk around the pipeline.
Compare the surge in Amylyx Pharmaceuticals with other biotech stories on the move by scanning the hand-picked 16 high quality undiscovered gems shaping the next wave of potential market re-rating candidates.
Amylyx Pharmaceuticals has already delivered a powerful rerating, yet the market is still weighing whether recent contracts justify more optimism or mostly lock in what is already priced. That will depend on how investors assess valuation from here.
Most Popular Narrative: 50% Overvalued
Amylyx Pharmaceuticals closed at $33.94, while the most followed narrative pegs fair value at $22.63. The story turns on whether current optimism about avexitide and the broader pipeline stretches too far ahead of execution and earnings.
While the company has extended its cash runway into 2028 and reduced total operating expenses to US$36.6 million in the latest quarter, ongoing R&D spend on avexitide, AMX0318, AMX0114 and AMX0035, including milestone payments such as the US$4 million to Gubra, may keep earnings under pressure if none of these programs reach late stage value inflection in the expected time frame.
See why 0 investors see Amylyx Pharmaceuticals as 50% overvalued.
Result: Fair Value of $22.63 (OVERVALUED)
Still, Amylyx Pharmaceuticals faces real tripwires if the Phase 3 LUCIDITY data fail to translate into approval or if PBH prescribing remains focused on nutrition based management.
Find out about the key risks to this Amylyx Pharmaceuticals narrative.
Another View On Amylyx Pharmaceuticals Valuation
Analysts focused on Amylyx Pharmaceuticals also highlight a very different signal. The Simply Wall St DCF model points to a future cash flow value of $201.25 per share, which is far above the current $33.94 price and presents the stock as deeply undervalued on that basis. Which perspective do you think is closer to reality?
Our DCF model combines long term cash flow assumptions, discount rates and terminal values into a single number, so it is important to understand what is built into that output and how sensitive it might be to small changes in forecasts. Look into how the SWS DCF model arrives at its fair value.
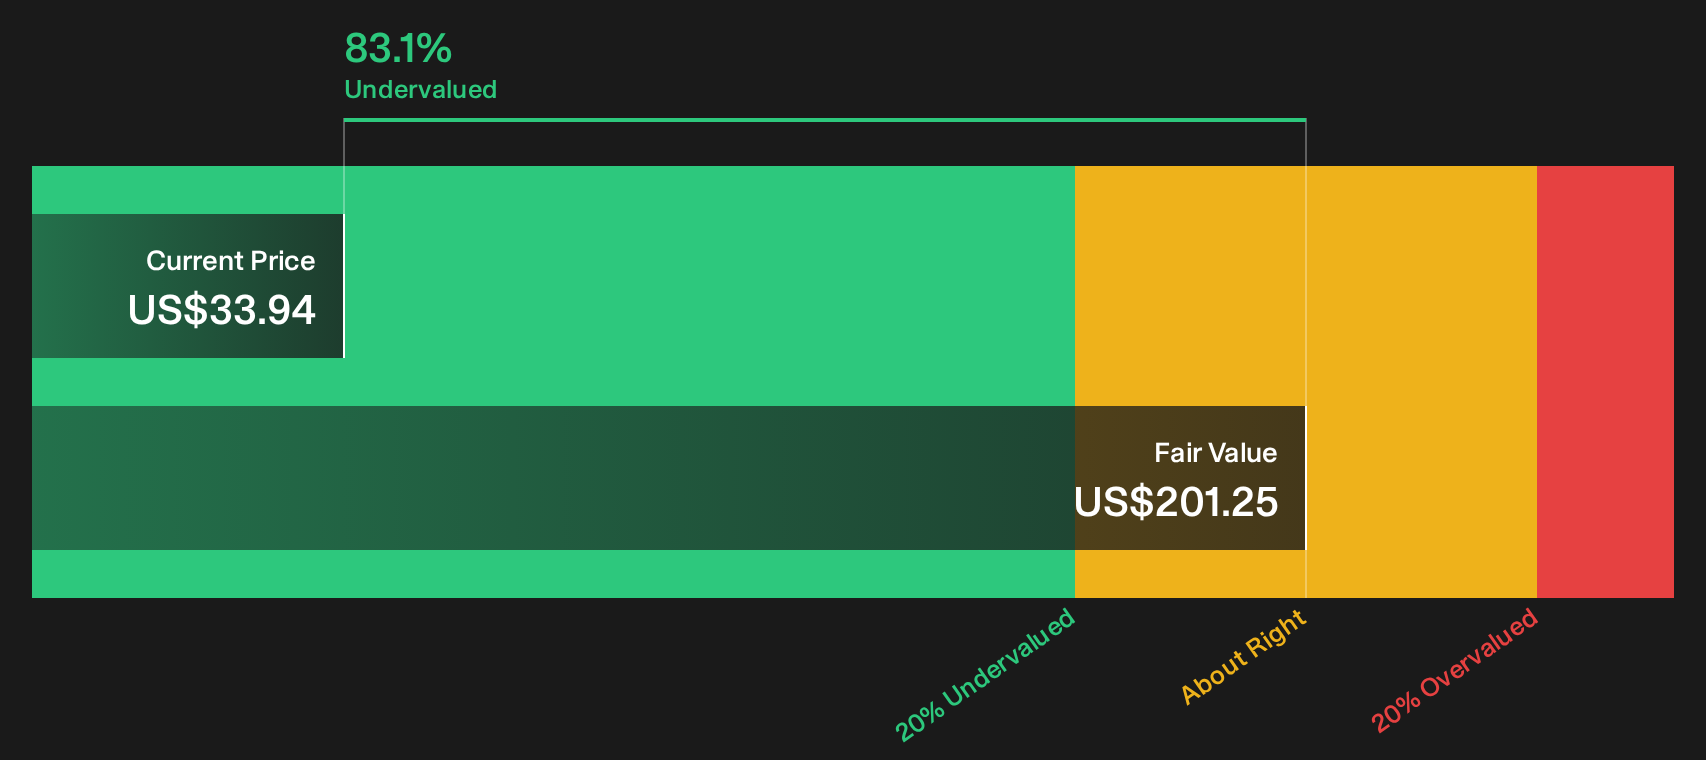
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amylyx Pharmaceuticals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed sentiment around Amylyx Pharmaceuticals leaves you torn, treat that uncertainty as a prompt to move quickly and build your own thesis using the 2 key rewards and 4 important warning signs.
Looking for more Amylyx Pharmaceuticals sized ideas?
Use what you have learned from Amylyx Pharmaceuticals as a springboard and keep building your watchlist with fresh, high conviction possibilities that match your style.
- Target potential upside by scanning a 29 high quality undervalued stocks that filters for businesses where quality and pricing may be out of sync.
- Strengthen portfolio durability by reviewing a list of solid balance sheet and fundamentals (23 results) that focuses on companies with robust financial foundations.
- Hunt for overlooked opportunities through a 16 high quality undiscovered gems curated to surface under-the-radar stocks before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com