


- AltaGas reported strong Q2 2026 results, with midstream earnings rising and utilities providing steady support. Management lifted 2026 guidance to normalized EBITDA of $2.0 billion to $2.1 billion and normalized EPS of $2.35 to $2.60.
- The firm kept its dividend framework intact with a total payout of $0.24 per share and a payout ratio near 65%, which highlights that current earnings still need to cover both growth investments and regular cash returns to shareholders.
- We will now look at how AltaGas's investment narrative is shaped by the higher 2026 guidance for EBITDA and earnings.
AltaGas Investment Narrative Recap
To own AltaGas, you need to be comfortable with a hybrid story. Regulated gas utilities are aimed at steady, rate-based returns, while the midstream arm is more exposed to Western Canada gas flows and Asian LPG export demand. The raised 2026 EBITDA and EPS guidance leans on that midstream strength, with utilities providing ballast as modernization spending continues.
In the near term, the key swing factor is execution in midstream exports without margin volatility undoing the higher guidance. The biggest risk remains capital intensity and funding costs. Interest payments are not well covered by earnings and free cash flows do not fully cover the dividend, so balance sheet management stays front and center.
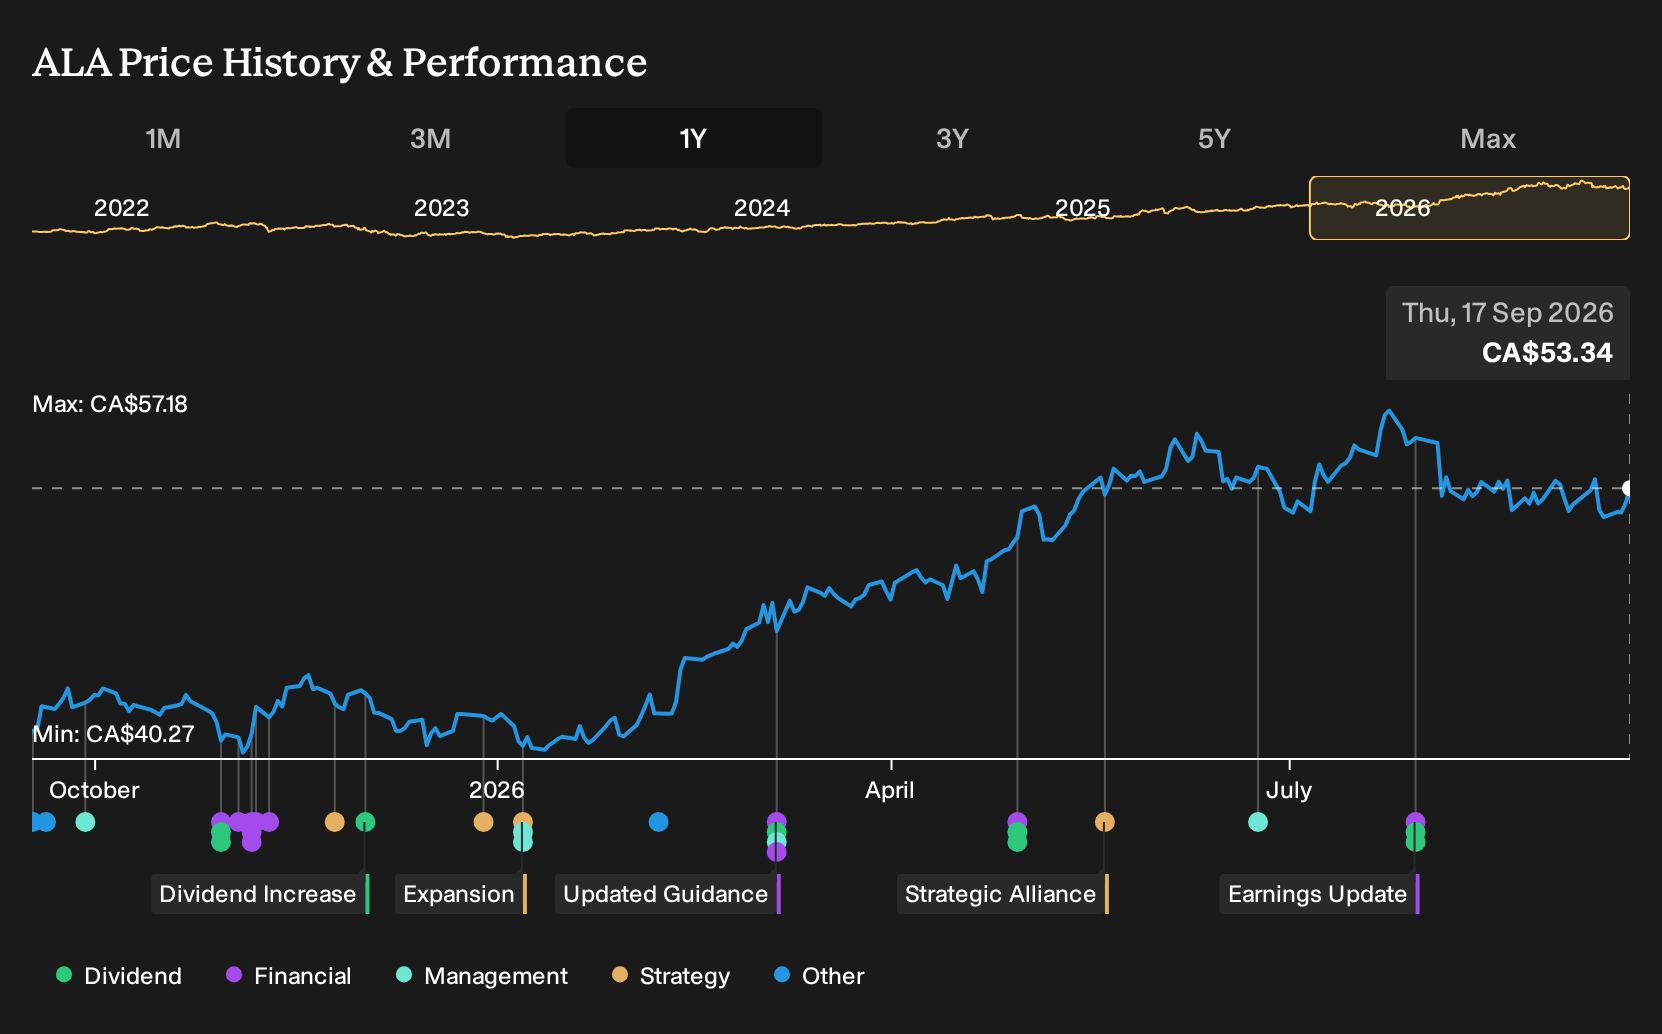
The newest data point that ties this together is AltaGas confirming a total dividend of CA$0.24 per share with an ex dividend date of 16 September 2026 and a payout ratio around 65%. That level aims to keep income flowing while still leaving room for debt reduction and ongoing capital projects in utilities and midstream.
For you as a shareholder, the message is that AltaGas is not loosening its dividend policy in response to stronger Q2 and higher 2026 guidance. The focus remains on funding infrastructure upgrades and export capacity while carrying meaningful leverage. The catalyst continues to be consistent operational delivery against guidance, with the key watchpoint being whether future cash flows tighten or ease this payout and interest coverage pressure.
AltaGas' current analyst narrative points to CA$16.4b in revenue and CA$1.0b in earnings by 2029. That profile assumes revenue grows at about 6.2% per year and earnings rise by roughly CA$385m from CA$615.0m today.
Uncover why AltaGas' fair value indicates a 13% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community place AltaGas anywhere between roughly 60 and 92, which is a wide gap for just a pair of estimates. Those retail forecasts sit before the latest dividend news and guidance lift. Use them alongside policy risks, export exposure, and debt pressures to test your own AltaGas thesis.
Explore another AltaGas fair value estimate, including one that suggests it could be worth just CA$60.18.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AltaGas research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AltaGas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AltaGas' overall financial health at a glance.
Looking for more investment ideas beyond AltaGas?
Once you have a view on AltaGas, it can help to stress test that thinking against a wider watchlist. The Simply Wall St Screener makes it easier to scan for other companies that line up with the kind of balance between income, quality, and risk that suits you.
- If you want potential mispricing with financial resilience, check out a focused list of 3 high quality undervalued stocks that combine solid fundamentals with room for the market to reassess them.
- If capital strength and durability matter most to you, start with a list of solid balance sheet and fundamentals (7 results) and see which businesses pair prudent leverage with consistent fundamentals.
- If you prefer to keep volatility contained, aim for stability first by reviewing a 8 resilient stocks with low risk scores that screens for companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com