


Arm Holdings has delivered a powerful share price run in recent years, which leaves a basic question on the table for investors who care about fundamentals. With expectations around artificial intelligence now tightly linked to Arm, the issue is whether that higher market value lines up with what the balance sheet actually shows in book value.
- Over the past 3 years the stock has returned about 407.9%, which puts a lot of weight on whether the share price still has support from the equity recorded on its books.
- Management is leaning into AI specific chip demand and a newer push into selling complete data center processors, a shift that can influence how much capital Arm needs to commit and how quickly any future earnings may build up book equity.
- Your read on Arm Holdings is one view; the desks covering it have another. See what analysts think Arm Holdings's shares could be worth.
The issue now is whether Arm Holdings' current share price is adequately supported by its book value when set against the industry average.
If you want a reference point for Arm Holdings' AI story and current P/B debate, it can help to scan other 89 AI infrastructure stocks.
Is Arm Holdings Getting Expensive on Book Value?
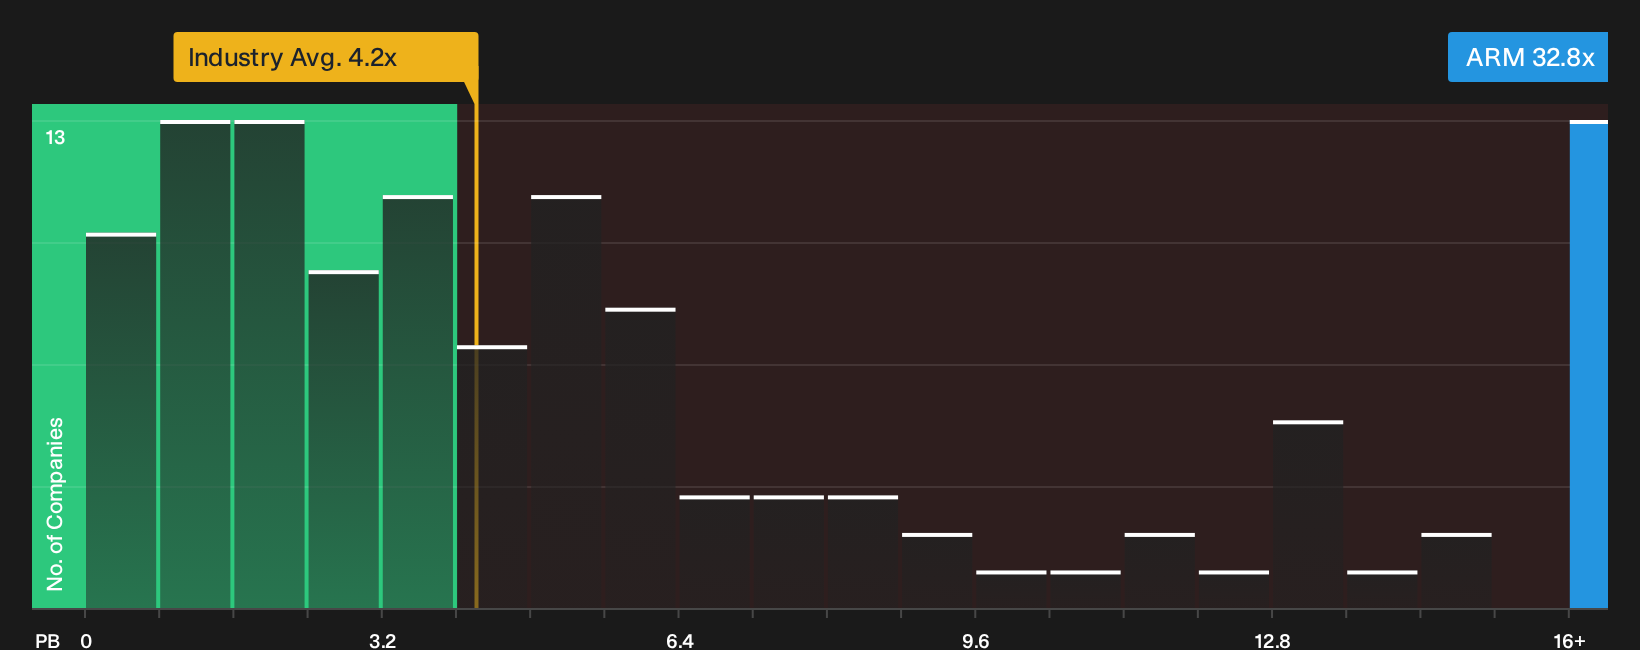
P/B works reasonably well for Arm Holdings because the group earns royalties on designs rather than owning heavy manufacturing assets, so the equity base matters for what you are paying for each dollar of net assets. On this yardstick the stock trades at about 32.8x book value, which is far above the semiconductor industry average of roughly 4.2x and also well above the peer group at about 9.3x.
Because the recent AI related selloff has already taken some heat out of Arm Holdings, the remaining 32.8x P/B still leaves the shares screening as overvalued relative to sector norms and similar chip designers. The gap suggests investors are paying a steep premium over the balance sheet, so anyone considering the stock needs to be comfortable that Arm's AI licensing and new data center chip ambitions justify paying more than triple the peer P/B level. Explore the numbers behind Arm Holdings's P/B valuation.
The Arm Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Arm Holdings act as the missing link between that rich P/B multiple and the expectations sitting behind it. They spell out what would need to happen to future growth, profitability and earnings power for the shares to be worth materially more or materially less than today’s price. Rather than relying on a single valuation output, each narrative lays out its underlying assumptions so you can compare them with actual results as they are reported on the Community page.
Community views on Arm Holdings now split between those who see an AI platform still mispriced and those who think the story is already overpaid for.
Bull case: 38% undervalued
"Arm may be one of the most strategically important companies in computing, but the stock already assumes a very large part of that future…"
Discover why this Narrative puts Arm Holdings at 38% undervalued.
Bear case: 278% overvalued
"ARM’s long-term structural story remains compelling, but the near-term valuation appears increasingly decoupled from fundamentals…"
Explore why this Narrative puts Arm Holdings at 278% overvalued.
One more Arm Holdings question before you log off
The price tag on Arm Holdings is only part of the story, because the people setting priorities and the way their incentives are structured can tilt the whole risk and reward profile. See who runs Arm Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com