


- Akamai Technologies expanded its technology collaboration with MuleSoft to link API governance with runtime security intelligence, while ITV plc used Akamai’s TrafficPeak on Akamai Cloud to gain subsecond observability for World Cup 2026 streaming on ITVX.
- The MuleSoft integration and ITV deployment both show Akamai pushing deeper into high-value security and observability workflows that tie directly to core client operations and uptime.
- We will now look at how Akamai Technologies' MuleSoft API security integration could influence the broader investment narrative around the business.
Scan how Akamai Technologies fits into the broader security and infrastructure story by reviewing a curated set of 89 AI infrastructure stocks that are powering API protection and real-time observability.
Akamai Technologies Investment Narrative Recap
For Akamai Technologies, the core belief is that security and compute can offset pressure in its mature CDN delivery activity. The short term hinge point is whether newer security and cloud services scale fast enough to justify rising CapEx and keep operating margins from compressing too far as investments ramp.
The MuleSoft integration and ITV’s TrafficPeak deployment both speak directly to that thesis. They highlight Akamai Technologies pushing deeper into higher value security and observability workflows. The main risk does not disappear. Customer concentration in compute and ongoing CDN headwinds still matter if large contracts or traffic volumes do not materialize as expected.
The MuleSoft collaboration is the clearest operational highlight here. It links Akamai Technologies’ API security engine with MuleSoft’s governance layer, giving customers continuous runtime visibility into APIs, MCP servers and AI interactions rather than point in time checks. That tight coupling plays into Akamai’s push to be a full stack security and infrastructure partner instead of just a delivery vendor.
For investors watching catalysts, this matters because it embeds Akamai Technologies inside day to day workflows for API design, compliance and incident response. That sort of integration can support stickier security revenue and makes the expanding cloud infrastructure footprint more relevant. Execution risk remains. The firm still needs to convert early MuleSoft adopters beyond the current 20 plus users and manage margin pressure as partner sourced solutions scale.
Akamai Technologies' current analyst story points to US$6.0b in revenue and US$659.8m in earnings by 2029, based on an 11.6% yearly revenue growth rate and an earnings increase of about US$248.8m from the US$411.0m reported today.
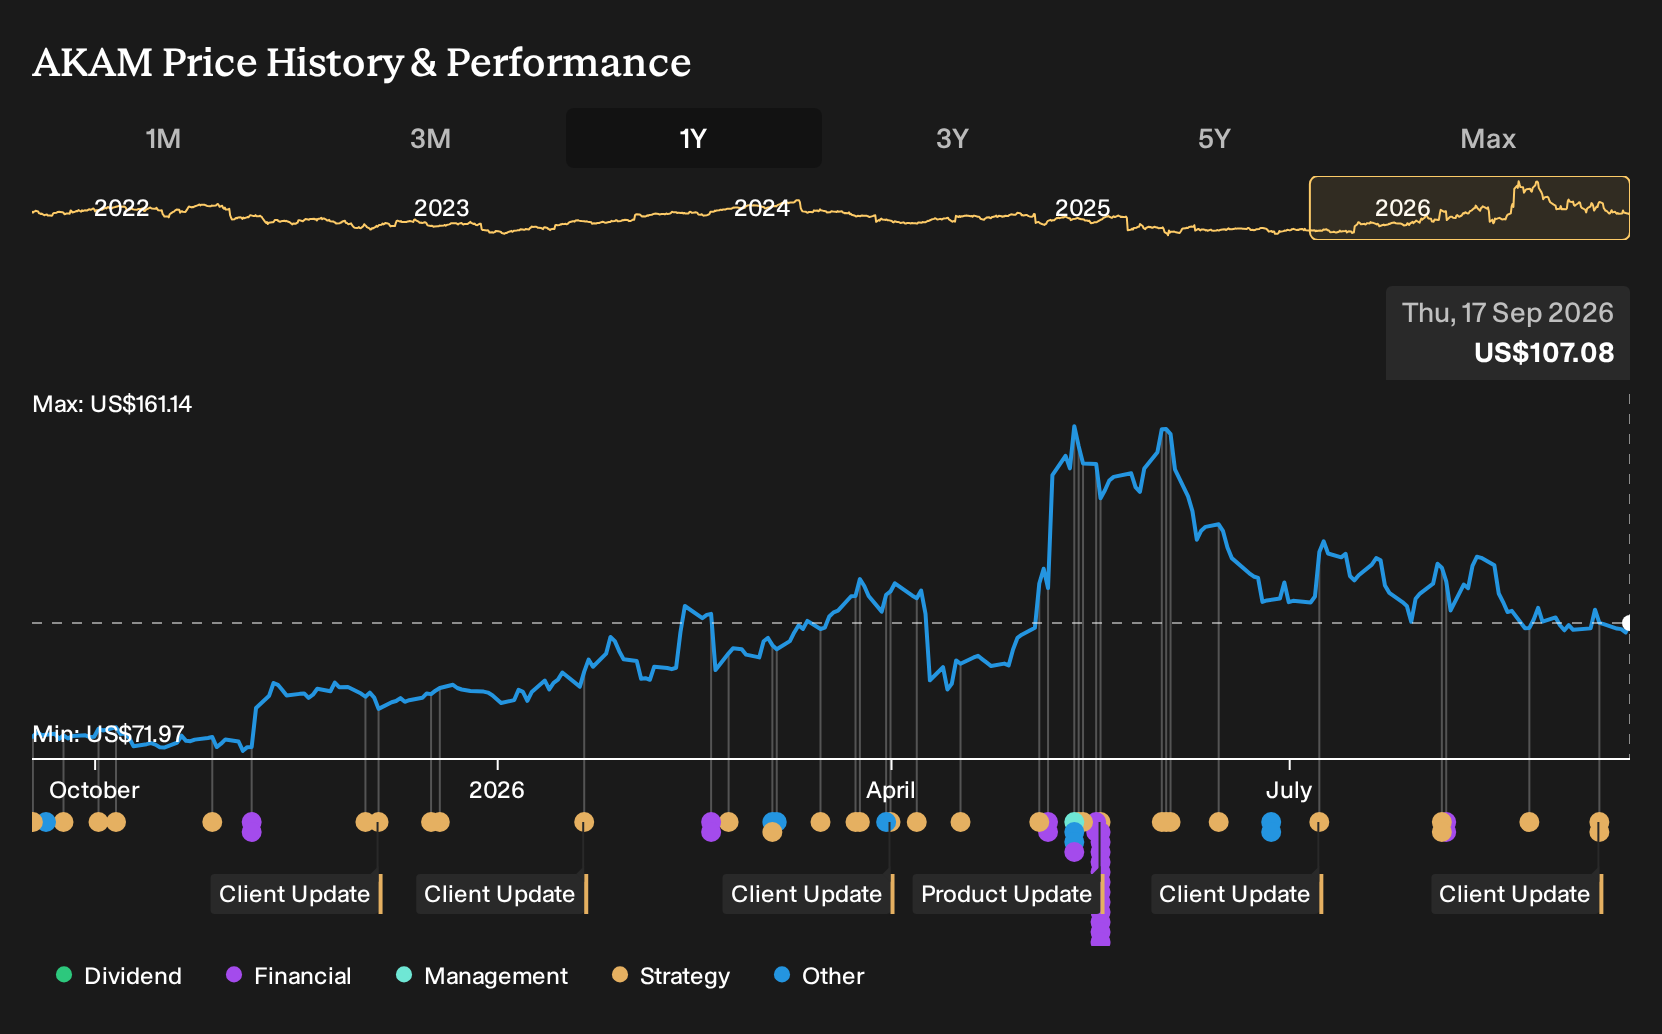
Uncover why Akamai Technologies' fair value indicates a 43% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view leans heavily on competition risk. In that story, hyperscale clouds and open source cap Akamai Technologies’ pricing power, with bearish analysts penciling in revenue of about US$5.7b and earnings of roughly US$408.7m by 2029. Those forecasts were set before this MuleSoft security news, so expectations could shift.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests as much as 72% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes often come from independent thinking, so consider your own analysis carefully.
- A great starting point for your Akamai Technologies research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Akamai Technologies?
If Akamai Technologies has sharpened your thinking about security, infrastructure and margins, it can be useful to widen the lens and compare it with other businesses that share similar financial traits. The Simply Wall St Screener lets you quickly scan for stocks that match the quality, balance sheet profile or risk level that fits your own approach.
- For investors who want growth potential with a margin of safety, scan a curated set of 29 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If capital preservation matters most to you, focus on stability first by filtering for 30 resilient stocks with low risk scores that score well on volatility and key financial risk checks.
- When balance sheet strength is a priority, narrow the universe to a list of solid balance sheet and fundamentals (23 results) that already shows robust finances before you spend more time on deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com