


- SPX Technologies has attracted attention after third party research highlighted its above average earnings outlook and strong cash flow profile, supported by recent positive revisions to profit estimates.
- The focus on higher expected EPS growth and healthier cash generation suggests SPX Technologies may have more internal funding flexibility for future projects than many peers.
- We will now look at how this focus on stronger cash flow may influence SPX Technologies' broader investment narrative and risk profile.
Compare SPX Technologies' growth and cash generation profile with a curated 16 high quality undiscovered gems list that may be quietly building similar earnings and cash flow momentum under the radar.
SPX Technologies Investment Narrative Recap
To own SPX Technologies, you need to believe the business can keep turning its HVAC and Detection & Measurement footprint into steady earnings and cash generation, even as projects ebb and flow. The recent focus on faster expected EPS and cash flow growth supports that view but does not change the basic near term story. The key near term catalyst remains execution on the large project backlog and capacity ramps.
The biggest risk still sits in how project heavy demand and M&A are handled. If several Detection & Measurement jobs that were pulled forward leave a hole later, or if integrations underperform, earnings could look choppy. Strong recent cash flow metrics help cushion that possibility but do not remove it.
The most relevant data point in this news cycle is the cited 34.2% year over year cash flow growth and the expectation for EPS to grow faster than the broader machinery peer group. That combination gives SPX Technologies more room to self fund capacity expansions in Canada and the U.S. and to keep pursuing bolt on deals without leaning too hard on external capital.
For catalysts, the interesting angle is how that cash generation interacts with a project driven portfolio. Healthy internal funding can support OlympusV Max rollouts, HVAC capacity additions and further niche acquisitions while still absorbing bumps if Detection & Measurement orders become lumpy. The flip side is that continued heavy use of acquisitions and large engineered projects means that execution risk on both integration and backlog delivery remains central to the SPX Technologies equity story.
SPX Technologies' narrative projects revenues of $3.2b and earnings of $494.6 million by 2029. This scenario assumes 10.5% yearly revenue growth and an earnings increase of about $236 million from $258.2 million today.
Uncover why SPX Technologies' fair value indicates a 50% potential upside to its current price that could narrow quickly.
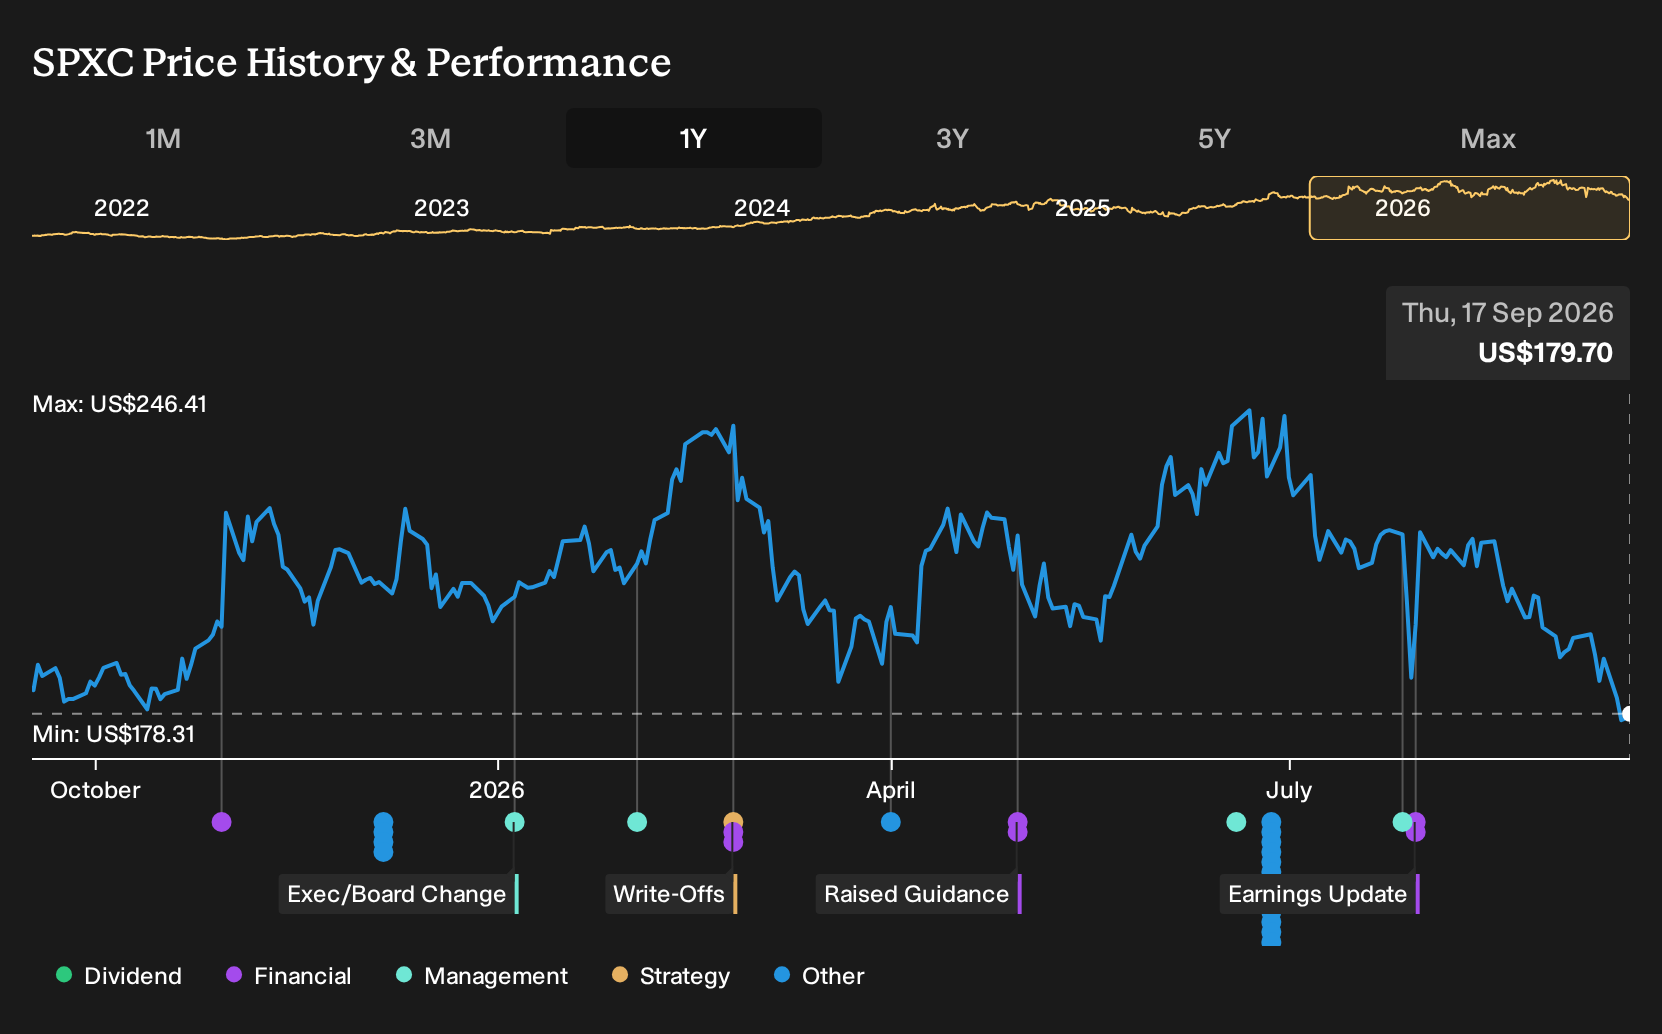
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$203 and about US$269, which already shows how far apart views on SPX Technologies run. Those retail models pre date the recent growth headlines. When you also consider project lumpiness, M&A execution risk and data center capacity plans, you get a wider set of outcomes worth exploring.
Explore 2 other SPX Technologies fair value estimates, including one that suggests the potential for 50% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your SPX Technologies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for SPX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPX Technologies' overall financial health at a glance.
Looking for more SPX Technologies style ideas?
If the SPX Technologies story has sharpened your thinking on cash generation, risk and upside, it can help to widen the lens and compare it with other businesses that fit different profiles on quality, resilience and income.
- For investors who want potential mispriced quality, review a 29 high quality undervalued stocks that combine strong fundamentals with prices that some models flag as below intrinsic value.
- If capital preservation and balance sheet strength matter most to you, filter for companies in the list of solid balance sheet and fundamentals (23 results) to see which businesses carry less financial strain on their books.
- For those focused on income reliability, scan a 6 dividend fortresses that offer higher yields while aiming to maintain payout support from underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com