


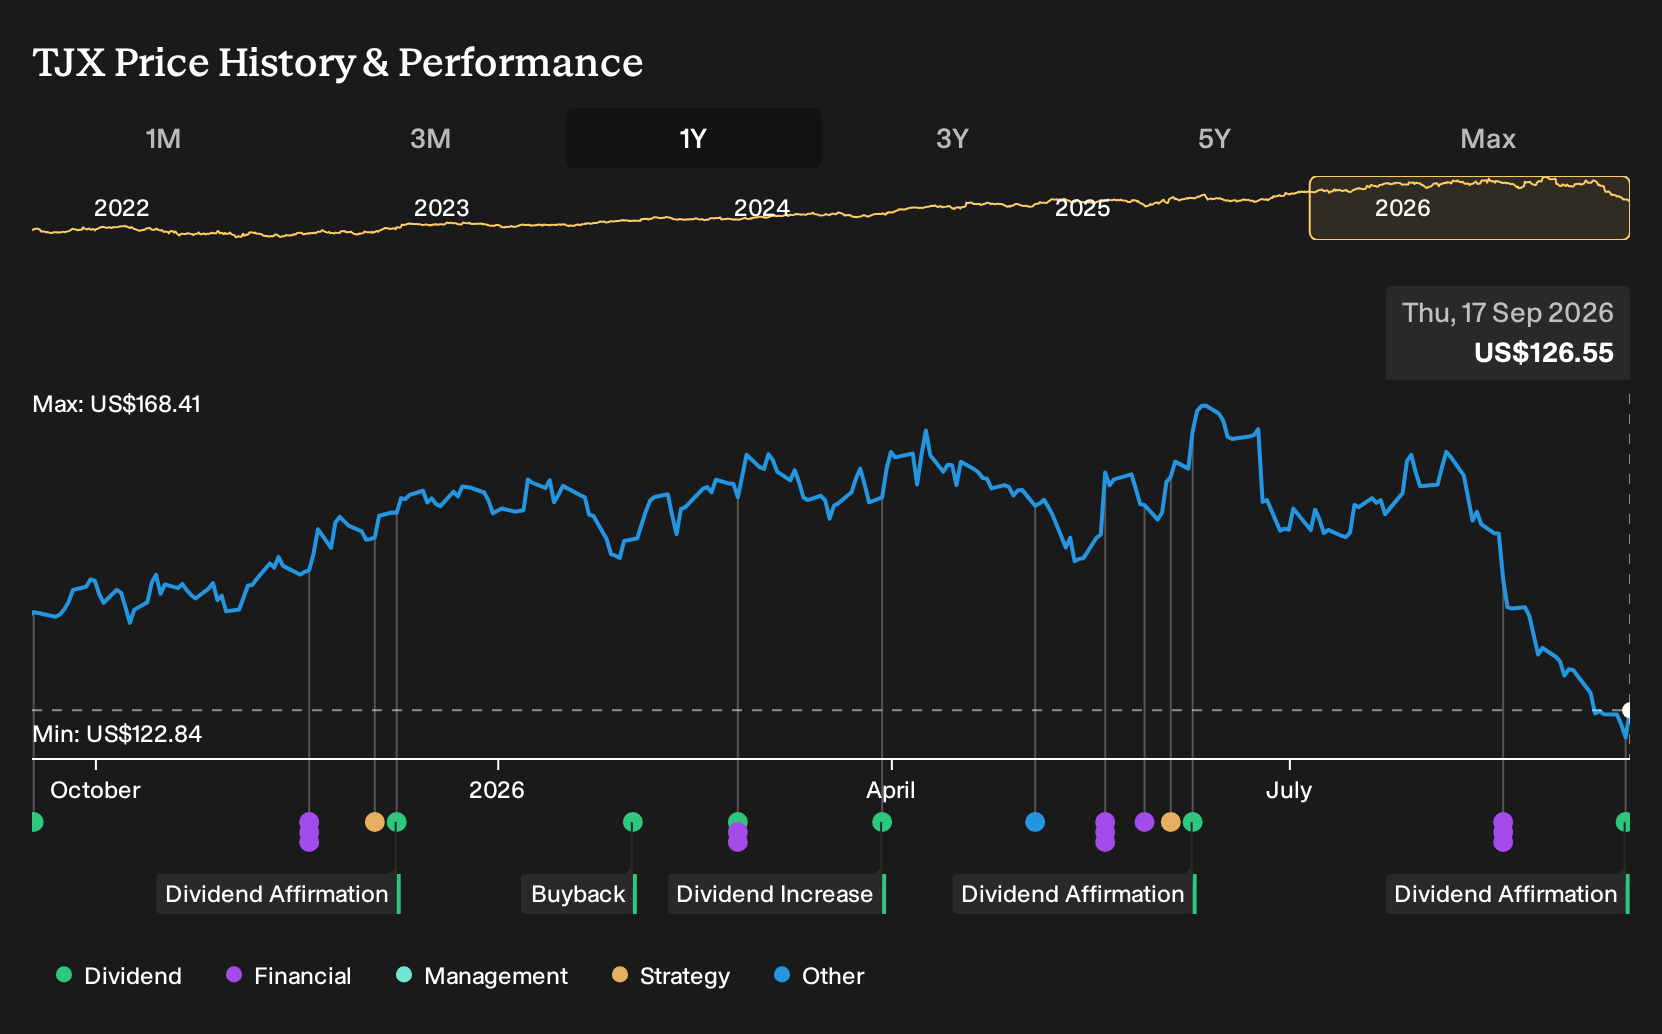
- TJX Companies confirmed a quarterly dividend of $0.48 per share payable on December 3, 2026, and added Craig A. Pintoff to its Board and Audit and Finance Committee after his long tenure at United Rentals.
- The retailer is refining its store footprint by closing at least four TJ Maxx locations while still planning to grow overall store count and opening pace, even as Marmaxx faces soft comparable sales and rising cost pressures.
- We will now examine how TJX Companies' store footprint reset, including selective closures, may reshape the broader investment narrative that investors track.
TJX Companies Investment Narrative Recap
To own TJX Companies, you need to believe its off price, treasure hunt model can keep pulling shoppers into stores even as e commerce competition intensifies and Marmaxx merchandising issues are addressed. The near term swing factor is whether management can realign product mix and maintain traffic while absorbing wage, fuel, and currency cost pressures.
The latest board and dividend news does not materially change that operating story. Store footprint tuning, with a few TJ Maxx closures alongside an intent to grow locations overall, matters more for now. The main risk remains margin pressure if labor and sourcing costs outpace what TJX can recoup through pricing and mix.
The most relevant update here is the confirmed quarterly dividend of US$0.48 per share, payable in December 2026. That decision provides another data point on how TJX Companies is balancing cash returns with the need to fund store remodels, new formats, and international growth while handling a softer patch at Marmaxx.
Dividend sustainability has been flagged as a weaker area, so the payout sits alongside execution risk on margins and comparable sales trends as something to watch rather than a settled strength. For potential catalysts, investors are likely to focus more on whether traffic and merchandise availability support earnings expectations than on the dividend itself.
TJX Companies' narrative projects US$74.8b revenue and US$7.2b earnings by 2029. This assumes 6.3% yearly revenue growth and an earnings increase of about US$1.1b from US$6.1b today.
Uncover why TJX Companies' fair value indicates a 37% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Here is a very different angle to consider. The most optimistic analysts treat TJX Companies’ global store expansion and e commerce build out as the key upside catalyst, with revenue projections of about US$78.3b and earnings near US$7.3b by 2029. Those estimates were set before this dividend and board news, so your view might shift as reactions evolve.
Explore 6 other TJX Companies fair value estimates, including one that suggests up to 56% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your TJX Companies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TJX Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TJX Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TJX Companies?
Once you have a handle on TJX Companies, it can help to compare its profile with other businesses that offer different mixes of growth potential, income, and balance sheet strength. The Simply Wall St Screener lets you quickly filter for the traits that matter most to you instead of trawling through tickers one by one.
- For investors who care most about quality at a sensible entry point, scan a curated set of 16 high quality undiscovered gems that have strong fundamentals but limited attention.
- If reliable balance sheets are your first filter, start with a list of solid balance sheet and fundamentals (23 results) to see which businesses pair financial resilience with underlying fundamental strength.
- Income focused readers can zero in on higher yield opportunities by checking out a 6 dividend fortresses that concentrates on companies offering 5%+ payouts with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com