


- Baidu is facing a securities class action lawsuit in the US that focuses on alleged misstatements about how its AI operations offset weakness in its core online marketing services.
- The filing highlights pressure on Baidu’s fundamentals, with detailed disclosures about falling legacy marketing revenue and slower momentum in the AI-powered segment that management had positioned as a key offset.
- We will examine how this lawsuit, which centers on Baidu’s AI offset claims, could reshape the broader investment narrative around the business.
Baidu Investment Narrative Recap
To remain a Baidu shareholder, you need to believe the AI-powered units can eventually carry more of the load as legacy online marketing weakens. The lawsuit targets that belief. Recent filings show Baidu General Business and legacy Online Marketing Services both declining, while the Core AI-powered segment has recently lost momentum instead of clearly offsetting that pressure.
In the near term, the key factor is whether Baidu can stabilize AI Cloud and broader AI services after the reported quarter-over-quarter and year-over-year slowdowns. The biggest operational risk is that heavy AI investment, combined with falling ad-related revenue and current unprofitability, keeps margins and free cash flow under strain for longer than investors are prepared to tolerate.
The most relevant disclosure for this legal action is Baidu’s August 18, 2026 report, which showed Baidu Core AI-powered business falling 8% quarter over quarter to RMB 12,500 million while legacy marketing weakened further. That update contradicted the earlier message that a faster-growing AI engine could meaningfully offset a shrinking ad base.
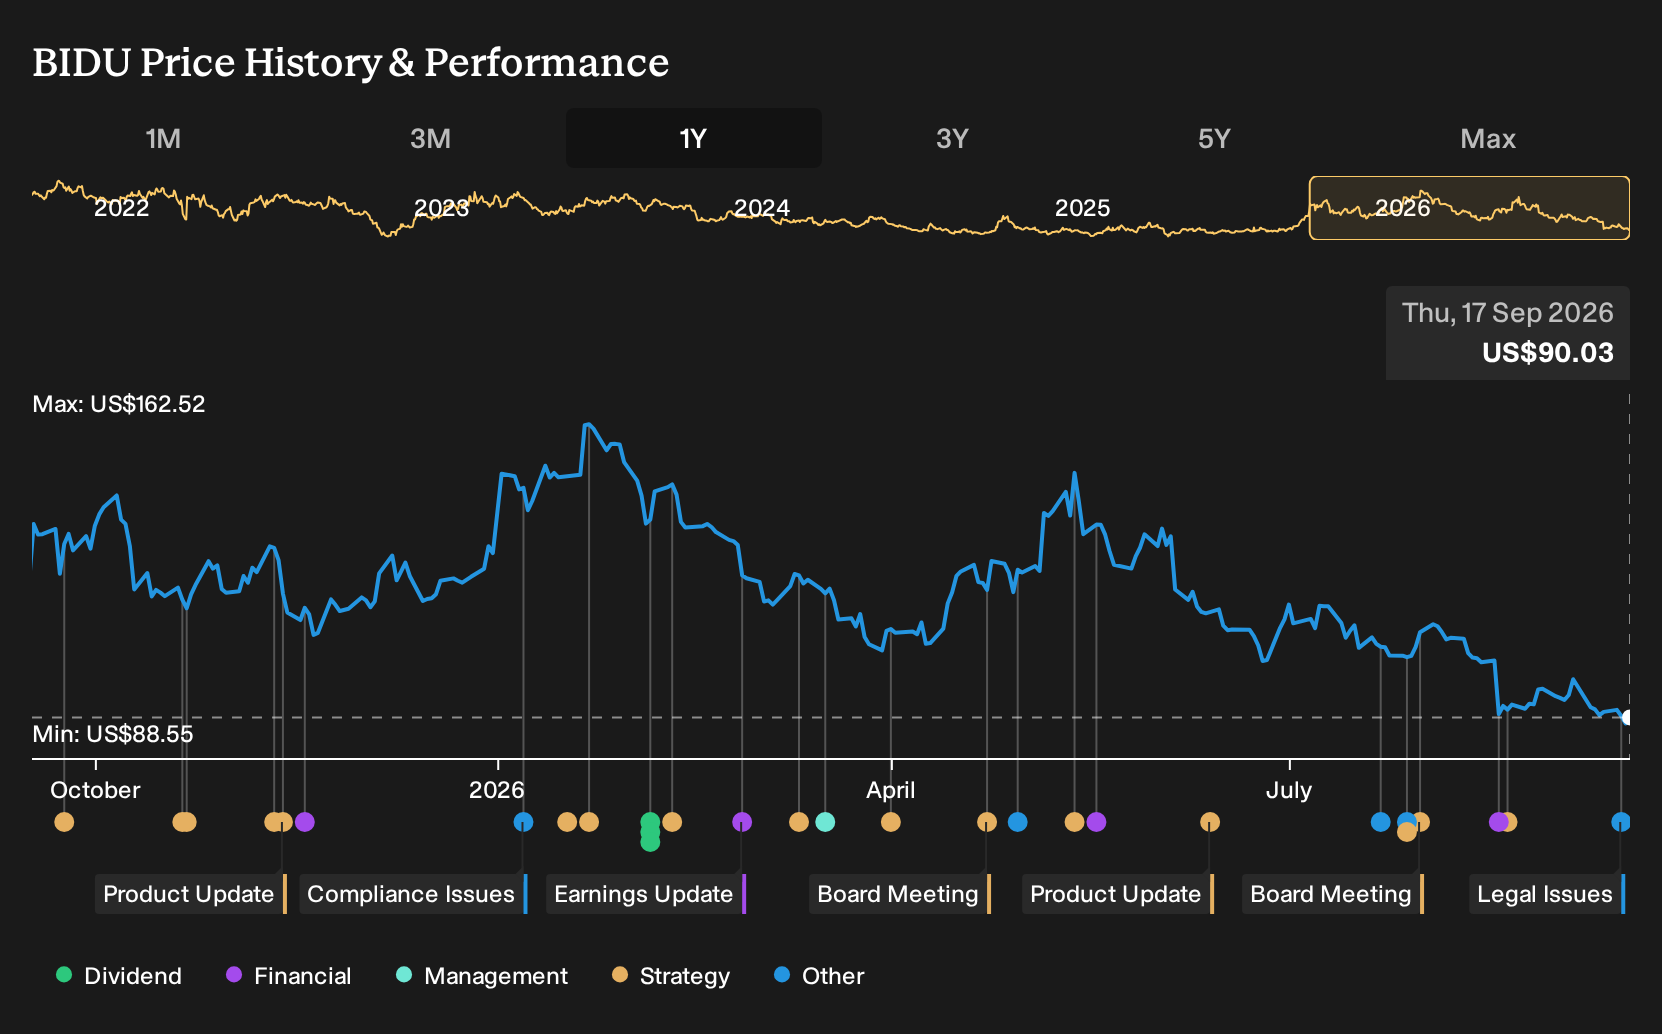
For you, the operational question is whether that AI segment can return to steadier growth while legacy Online Marketing Services remains under pressure. Execution around AI Cloud Infra, autonomous driving partnerships, and AI search monetization now needs to be assessed against a backdrop of class action scrutiny, revenue contraction at the group level, and a stock that has already fallen sharply over the past year.
Baidu's current analyst script points to CN¥154.2b in revenue and CN¥16.2b in earnings by 2029, based on a 6.6% yearly increase in revenue and an earnings change of about CN¥20.8b from a loss of CN¥4.6b today.
Uncover why Baidu's fair value indicates a 63% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You are now seeing how sharply opinions on Baidu can diverge. The most optimistic analysts leaned on AI as a catalyst, projecting CN¥218.1b in revenue and CN¥39.5b in earnings by 2029 before this lawsuit surfaced. You may decide those expectations look too upbeat once the legal and disclosure questions are clearer.
Explore 6 other Baidu fair value estimates, including one that suggests there could be as much as 175% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Baidu research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Baidu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baidu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Baidu?
Once you have a view on Baidu, it can help to compare it with other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you filter for exactly the kind of businesses you want to research next.
- If capital preservation is your anchor, focus on resilience first by scanning a 30 resilient stocks with low risk scores that aims to keep volatility and balance sheet risk in check.
- If you are hunting for value, widen your watchlist to companies that combine strong fundamentals with appealing prices by reviewing 16 high quality undiscovered gems that may not yet be widely followed.
- If steady income is a priority, line up potential payers and stress test their payouts against your own criteria using a 6 dividend fortresses that puts yield and durability side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com