


TeraWulf’s pivot toward AI infrastructure
TeraWulf (WULF) is in the middle of a business overhaul as it shifts away from pure bitcoin mining toward AI-focused infrastructure and high-speed computing operations.
The new 20-year lease agreement with Anthropic signals a move toward long-term contracted revenue, even as recent results reflected missed expectations tied to weaker bitcoin-related income.
Recent trading has been choppy for TeraWulf. The stock has a 1-day share price return of 7.02% and a 7-day share price return of 2.04%. However, the 90-day share price return declined 43.17% even as the 1-year total shareholder return reached 47.45% and the 3-year total shareholder return was very large at over 10x.
Scan beyond TeraWulf’s AI pivot and line up other potential beneficiaries of the same trend with a curated list of 89 AI infrastructure stocks
TeraWulf’s shares have swung from sharp gains to a 90 day pullback, while analyst estimates sit far higher than the current price. Where does a reasonable view of fair value land within that gap?
Most Popular Narrative: 57% Undervalued
The most followed narrative on TeraWulf pegs fair value at $37.94 per share, well above the last close at $16.47. This frames the current price as a steep discount that depends heavily on long-horizon AI infrastructure contracts playing out as expected.
Long-term partnerships and investments from marquee players (Google's $1.8B lease backstop and equity stake) signal institutional validation, enhance creditworthiness, and are likely to lower WULF's future cost of capital, directly supporting margin expansion and accelerated infrastructure growth.
See why 142 investors see TeraWulf as 57% undervalued.
Result: Fair Value of $37.94 (UNDERVALUED)
Still, TeraWulf’s AI narrative leans heavily on capital intensive buildouts and the financial strength of tenants, so funding strains or counterparty setbacks could quickly test that optimism.
Find out about the key risks to this TeraWulf narrative.
Another view on TeraWulf’s valuation
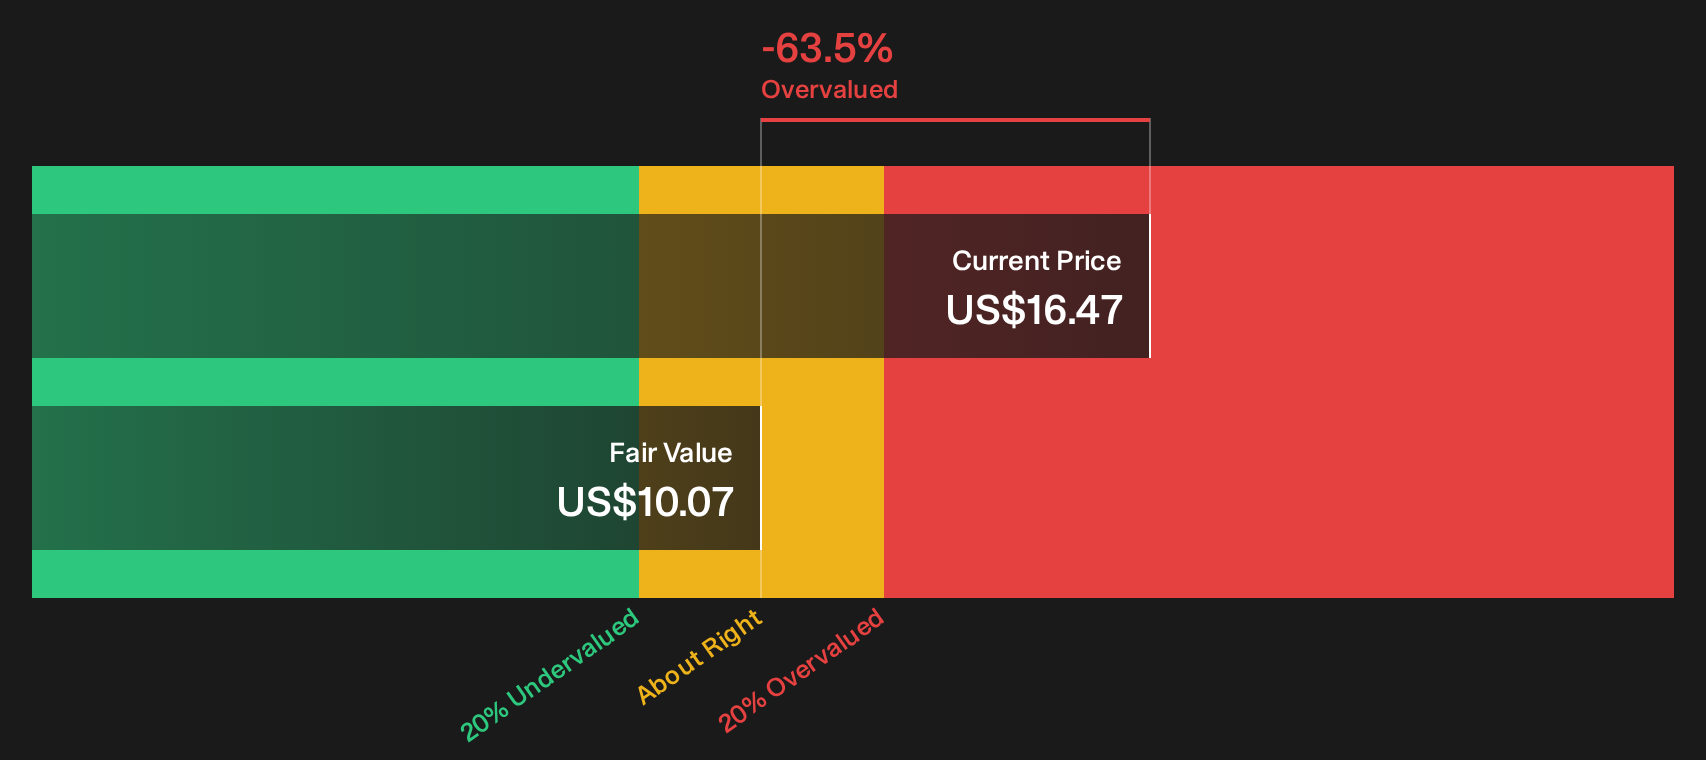
The most popular narrative leans on long term AI contracts to argue TeraWulf looks 57% undervalued. A second lens tells a very different story. Our DCF model puts future cash flow value at $10.07 per share, which is well below the current $16.47 price and points to an overvalued outcome instead. How comfortable are you if the cash flow math ends up being closer to reality than the story around long duration leases?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on TeraWulf is split, with bulls focused on rewards and skeptics watching the risk list closely. Move quickly and pressure test the numbers yourself by weighing 1 key reward and 4 important warning signs
Hunting for more investment ideas beyond TeraWulf?
If TeraWulf has your attention, do not stop your research here. Cast a wider net across other potential opportunities so you are not relying on a single AI infrastructure story.
- Target potential value opportunities by scanning a curated set of 29 high quality undervalued stocks that pair financial strength with pricing that may not fully reflect fundamentals.
- Strengthen your income toolkit and stress test your cash flow plan with a focused group of 6 dividend fortresses that combine higher yields with resilient payout records.
- Reduce portfolio fragility by filtering for 30 resilient stocks with low risk scores that score well on balance sheet resilience and lower overall business risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com