


BKV (BKV) recently completed a US$500 million convertible bond offering with 1.625% notes due October 15, 2031, a financing move that gives investors another lens on the company’s balance sheet and capital plans.
BKV’s recent financing and Barnett Shale acquisitions arrive after a softer share price patch, with the stock down 16.95% on a year to date share price return. Even so, the 1 year total shareholder return of 2.70% remains slightly positive, suggesting momentum has faded while investors reassess growth potential and balance sheet risk.
Compare how BKV performs relative to other gas producers under pressure by reviewing a curated list of list of solid balance sheet and fundamentals (23 results).
BKV now trades well below the average analyst target, yet has just layered on fresh convertible debt and Barnett exposure. Is this a sensible discount for added risk or an opportunity the market is overpricing?
Most Popular Narrative: 36% Undervalued
At a last close of $22.79 versus a narrative fair value of $35.36, the most followed view on BKV frames the stock as materially discounted and links that gap to its integrated gas, power and carbon capture build out.
The closed loop strategy that integrates natural gas, power and carbon capture is resonating with large hyperscalers and industrial customers that are willing to pay premiums for carbon neutral energy solutions. If BKV converts its strong commercial pipeline into long term contracts across multiple business lines, the market may reassess the company as a scarce integrated energy transition platform, which could result in multiple expansion and outsized appreciation in revenue and earnings relative to a flat share price outcome.
See why 2 investors see BKV as 36% undervalued.
Result: Fair Value of $35.36 (UNDERVALUED)
Still, the BKV story can break if ERCOT power projects or CCS facilities slip on timing or profitability, or if lower margin forecasts prove closer to reality.
Find out about the key risks to this BKV narrative.
Another View on BKV’s Valuation
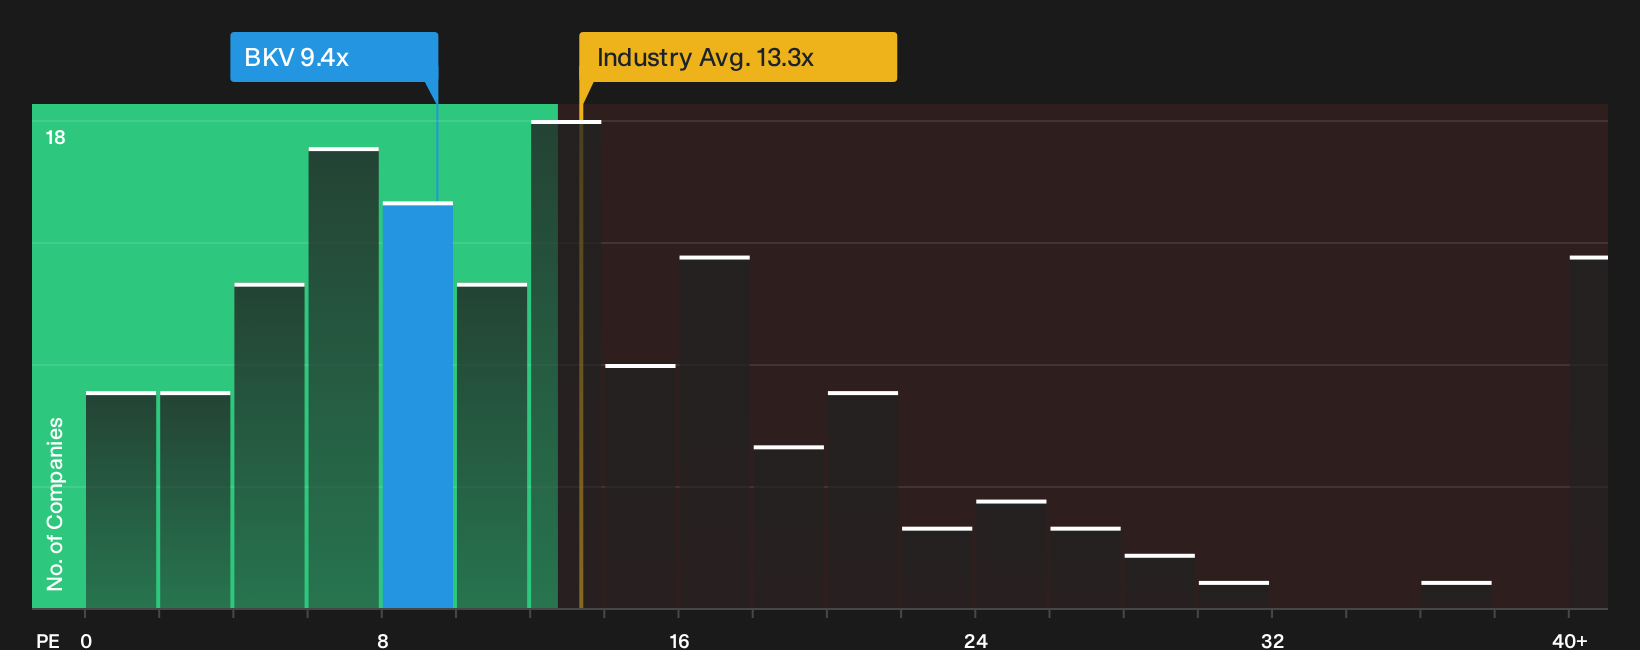
The analyst narrative presents BKV as 36% undervalued, yet a straightforward earnings measure suggests a different perspective. The stock trades on a P/E of 9.4x, which appears lower than the US Oil and Gas industry at 13.2x, but higher than its own fair ratio of 7.4x. That combination points to some potential upside narrative, along with clear valuation risk if sentiment changes.
If earnings move toward the lower end of analyst margin and profit forecasts, a shift closer to the 7.4x fair ratio would suggest the market is applying stricter scrutiny to how much to pay for BKV’s future earnings.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Bullish or cautious on BKV after all this, the key is to move quickly from headline takes to the underlying numbers and form your own view. To balance the upside story with the concerns already flagged by the market, start with the 3 key rewards and 4 important warning signs.
Looking For More BKV Investment Ideas?
Do not stop your research with BKV alone. Broaden your watchlist with fresh ideas that match your risk tolerance and return goals using focused stock screens.
- Target resilient balance sheets and cleaner fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that highlights financially sturdier businesses.
- Hunt for potential mispricings by reviewing a hand picked set of 29 high quality undervalued stocks that may trade below their intrinsic estimates.
- Prioritise income potential and durability by filtering for 6 dividend fortresses that combine higher yields with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com