


- IREN has pivoted from Bitcoin mining toward a vertically integrated AI cloud platform, anchored by a five year, roughly US$5.50b partnership with Nvidia and supported by large multiyear AI compute contracts.
- The shift means IREN’s operations are increasingly tied to data center build out, GPU supply constraints, and execution on high value AI cloud services rather than cryptocurrency cycles.
- The focus will now be on how IREN’s investment narrative is shaped by this Nvidia backed AI cloud expansion strategy.
Scan how IREN's pivot into AI infrastructure compares with other GPU heavy plays by reviewing the hand picked 89 AI infrastructure stocks powering the same build out story.
IREN Investment Narrative Recap
To own IREN, you need to believe the pivot to AI cloud can scale into a durable compute platform, funded by heavy data center and GPU spending, without squeezing liquidity too far. Recent results show AI revenue now ahead of Bitcoin mining and sizeable multiyear AI contracts in place, so the near term operating focus sits squarely on deploying that capacity on time.
The key short term catalyst is whether IREN can turn contracted AI demand into stable, high utilization across its facilities despite GPU and high bandwidth memory bottlenecks. The biggest risk is that losses and large capex, layered on a short cash runway and debt or lease financing, stretch the balance sheet before earnings improve.
The Nvidia partnership, roughly US$5.50b over five years, looks most relevant here. That agreement gives IREN preferred access to GPUs in a sector where CoreWeave and Nebius are both raising capital and increasing AI compute prices because of tight supply. For an investor, the central question is whether IREN can translate that chip access into reliable AI capacity faster than rivals.
This same deal also increases the firm’s exposure to execution risk. IREN already reports widening losses and less than one year of cash runway, while rapidly expanding data center infrastructure. Any delay in Nvidia hardware deliveries, high bandwidth memory constraints or data center build outs could slow the AI revenue ramp, while debt, leases and energy costs continue to run in the background.
IREN's narrative projects US$13.6b revenue and US$1.6b earnings by 2029. This rests on analysts assuming roughly 168.0% yearly revenue growth and earnings moving from a loss of US$702.6m today to a profit of US$1.6b, a swing of about US$2.3b.
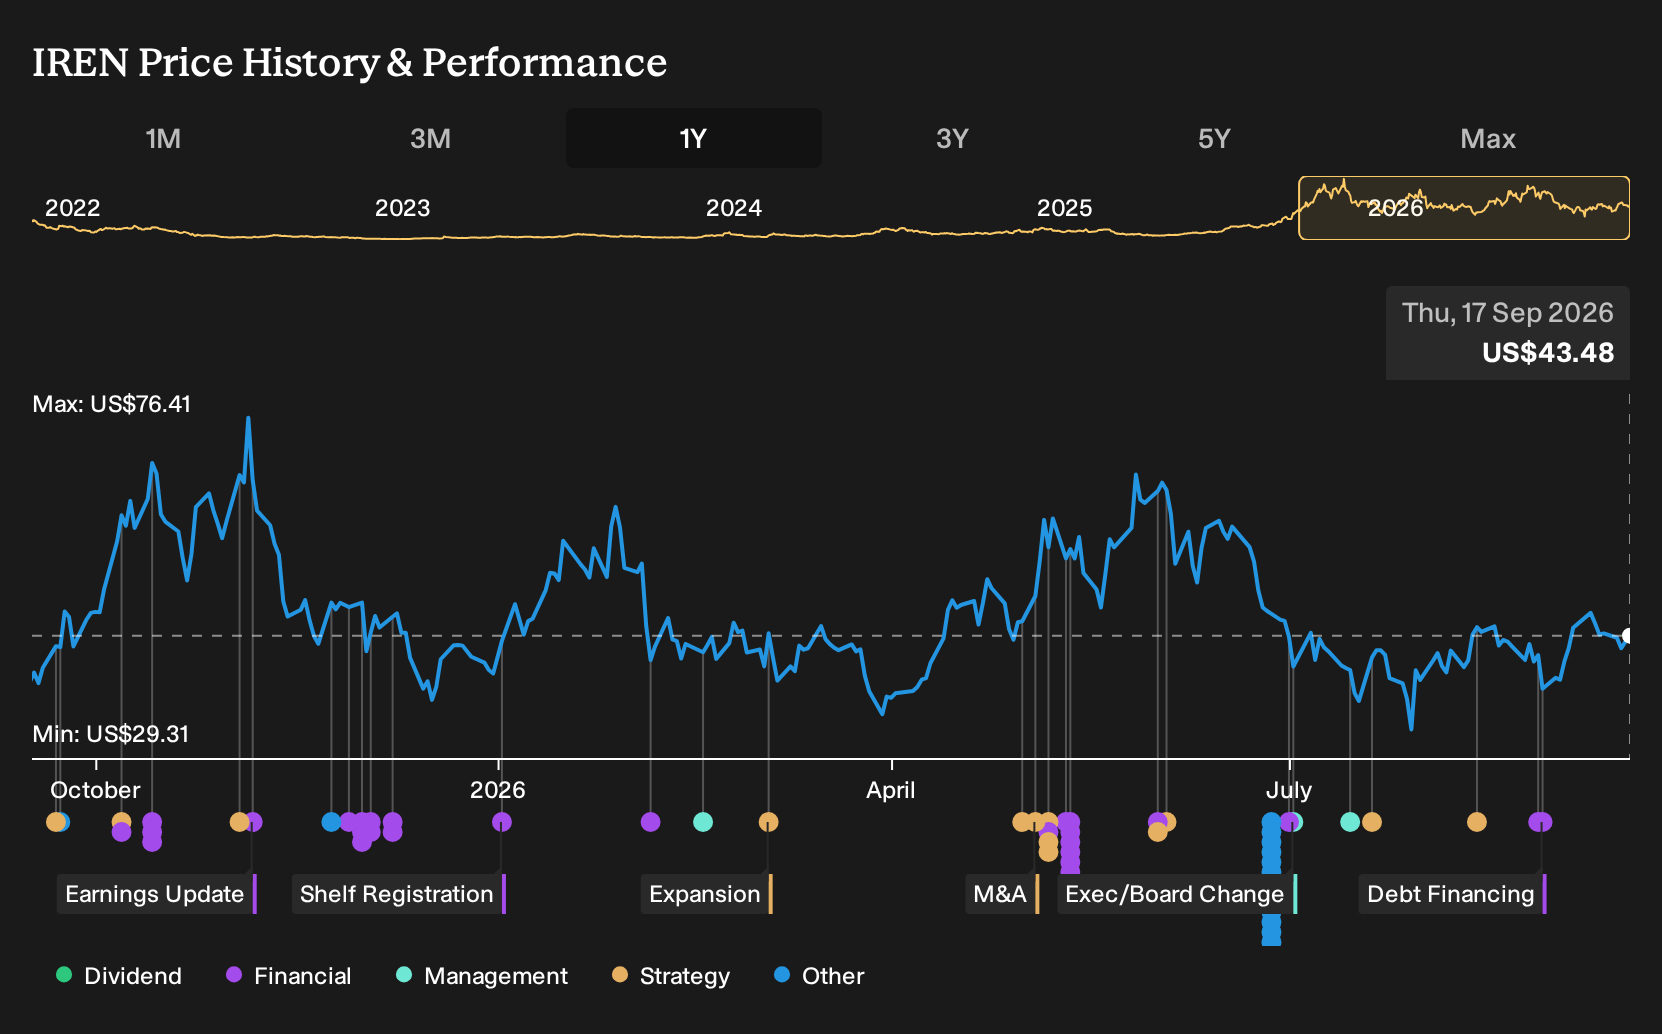
Uncover how IREN's fair value indicates an 82% potential upside to its current price before IREN's valuation gap narrows.
Exploring Other Perspectives
One alternate view on IREN puts far more weight on regulatory crackdowns around energy use. Under that lens, the lowest analysts were working off much smaller long range assumptions, with revenue forecasts around US$4.80b and earnings near US$551.6m by 2029. That is a sharply more cautious narrative that could shift after this news.
Explore 23 other IREN fair value estimates, including one that suggests as much as 97% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your IREN research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for IREN. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IREN's overall financial health at a glance.
Looking for more investment ideas beyond IREN?
If the IREN story has you thinking about position sizing, risk, and balance sheet strength, it can help to line it up against other potential opportunities using the Simply Wall St Screener.
- If capital preservation is front of mind, focus on resilience first by scanning a 30 resilient stocks with low risk scores that may better fit a defensive approach.
- If value is your starting point, compare IREN with a 29 high quality undervalued stocks that combine solid fundamentals with pricing that some investors may see as attractive.
- If you want to move earlier in the research cycle, widen your watchlist with a 16 high quality undiscovered gems that have strong underlying metrics but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com