


Steven Madden (SHOO) just posted Q2 results that topped analyst expectations on both revenue and earnings per share, yet the footwear specialist has seen its share price slip since the report.
That reaction sits against a mixed backdrop for Steven Madden. The share price has slipped around 10.6% over the past month and is down slightly year to date. However, the 1-year total shareholder return of about 30.5% and 3-year total shareholder return of roughly 44.8% still point to stronger gains for longer term holders than short term traders are currently seeing.
Scan how Steven Madden compares with a hand-picked 29 high quality undervalued stocks that have also beaten expectations yet still trade at a discount to their fundamentals.
Steven Madden now trades about 25% below the average analyst target and at an implied 54% discount to estimated fair value after the post earnings pullback. Is that a margin of safety or a warning sign?
Most Popular Narrative: 20% Undervalued
Against a last close of $41.80, the most followed narrative pegs Steven Madden's fair value at about $52.40, leaving a sizeable valuation gap that analysts link directly to execution in digital, international and brand expansion.
Vertical integration efforts and ongoing supply chain diversification away from China (with U.S. imports sourced from China expected to move from 71% to 30% year-over-year) provide a pathway to improve gross margin stability and working capital management, supporting future earnings recovery once tariff disruptions stabilize.
See why 3 investors see Steven Madden as 20% undervalued.
Result: Fair Value of $52.40 (UNDERVALUED)
Still, the bullish Steven Madden narrative can be knocked off course if tariff policy stays unpredictable or if the Kurt Geiger integration drags on costs and execution.
Find out about the key risks to this Steven Madden narrative.
Another View On Steven Madden's Valuation
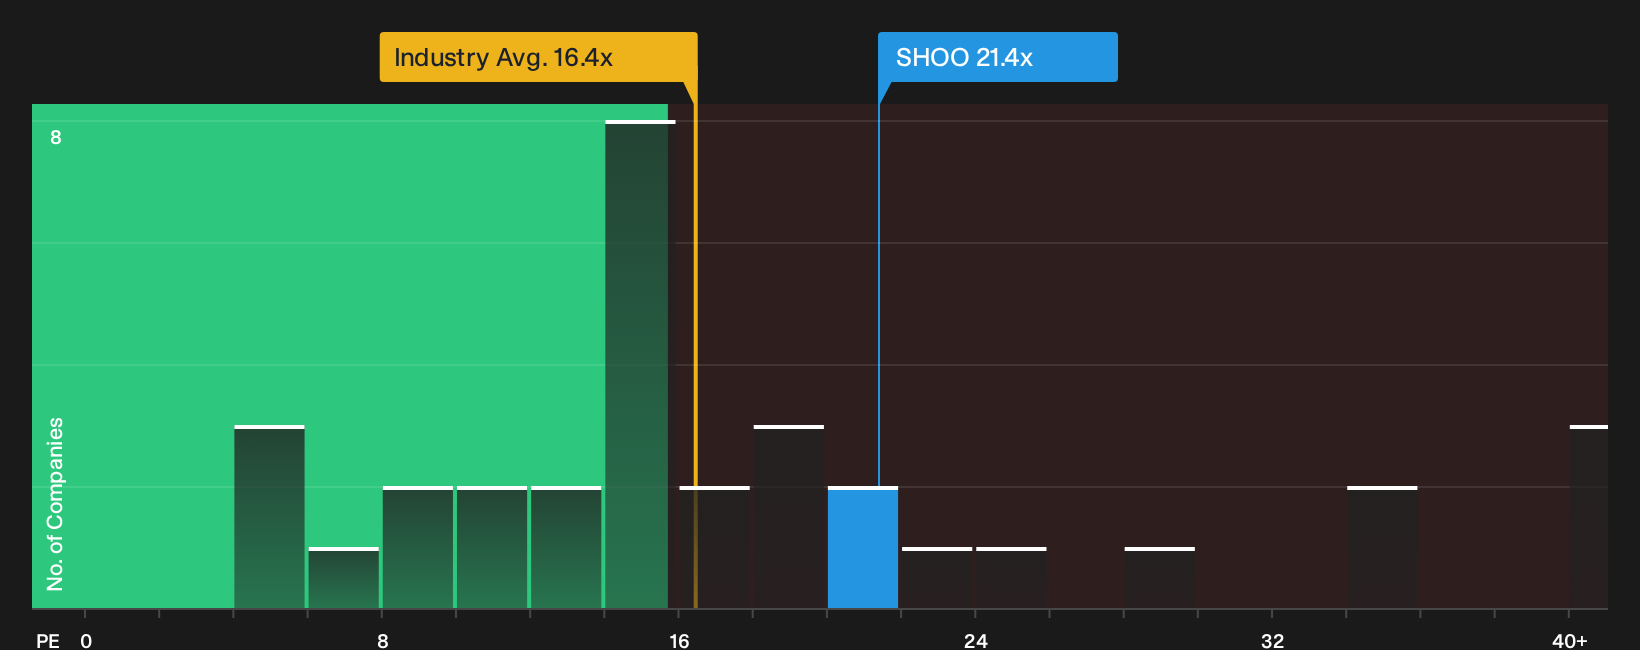
The market is not treating Steven Madden as a clear bargain on earnings. The stock trades on a P/E of 21.4x compared with 12.5x for direct peers and 15.6x for the broader US Luxury group. The fair ratio sits almost exactly in line at 21.5x.
The multiple suggests investors are already paying a premium to the sector. The fair ratio, however, points to something closer to fully priced on this metric. This raises a simple question for you as a shareholder or potential buyer: is the extra P/E premium really justified by the story you believe in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the upbeat valuation case and the recent share price softness on Steven Madden is reasonable. Move quickly and weigh the full picture yourself by comparing both the cautions and the upside in the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Steven Madden?
If Steven Madden has sharpened your interest in valuation gaps and quality fundamentals, broaden your watchlist now and give yourself more options before the next move.
- Target resilient balance sheets and steady fundamentals by reviewing a curated list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
- Hunt for potential mispricings by scanning a focused 29 high quality undervalued stocks that already clear quality and financial strength filters.
- Prioritise staying power and defense by checking a hand-picked 30 resilient stocks with low risk scores that may help smooth out the rougher patches in your holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com