


Willis Lease Finance has delivered very strong gains over the past five years, yet the recent pullback and governance headlines leave a straightforward question for you as an investor. Is the current share price properly supported by the earnings power of the business?
- Over the past 5 years, Willis Lease Finance has produced a cumulative return of 356.8%, which puts the focus squarely on whether that share price climb matches the progress in its underlying earnings.
- The investigation into executive compensation, including large stock option awards to the executive chairman, may influence how much of future earnings ultimately flows through to ordinary shareholders.
- There is a second opinion on Willis Lease Finance worth weighing. See what analysts think Willis Lease Finance's shares could be worth.
The issue now is whether Willis Lease Finance's current valuation can be justified by the earnings investors are paying for today.
To evaluate whether Willis Lease Finance still aligns with your return targets, it can help to compare it with 29 high quality undervalued stocks.
Is Willis Lease Finance a Bargain on Earnings?
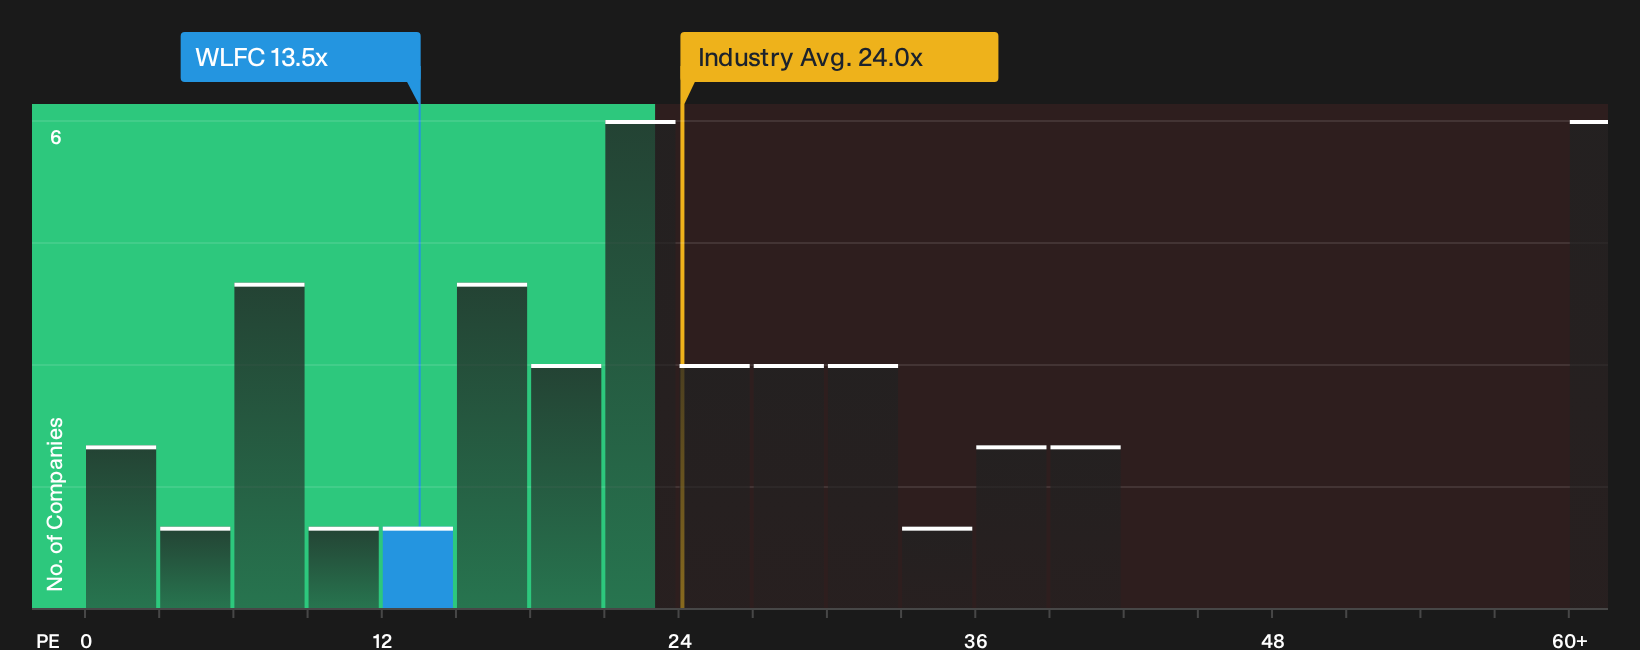
The P/E ratio fits Willis Lease Finance because earnings quality and consistency matter a lot for an aircraft leasing and services business. On this measure, the stock trades on about 13.5x earnings, which is well below the Trade Distributors industry average of roughly 24.0x and far under the broader peer group near 61.4x. That is a big gap in what investors are currently willing to pay for each dollar of Willis Lease Finance profit.
The Fair Ratio model, which adjusts the expected P/E for factors like the firm’s profitability, growth assumptions and risk profile, points to a higher level than the current 13.5x. Because of that, the shares screen as undervalued on this earnings multiple even after the recent investigation into executive compensation, which has drawn attention to governance and control. For a holder weighing whether the recent pullback has already priced in these issues, the low P/E relative to both tailored and simple benchmarks suggests the market is applying a meaningful discount that you may want to interrogate further. Explore the numbers behind Willis Lease Finance's P/E valuation.
The Willis Lease Finance Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where this P/E puzzle for Willis Lease Finance leaves off. It spells out what would need to happen to future growth, margins and earnings for the current share price to look either conservative or stretched. It then sets out the assumptions behind each fair value so you can weigh those inputs against actual results as they are reported. Narratives for Willis Lease Finance live on Simply Wall St's Community page.
A written, number driven view on Willis Lease Finance helps you pin down what earnings, governance and capital allocation outcomes would need to look like for the current valuation to make sense. With an active review into executive compensation and option awards underway, having those assumptions in black and white makes it easier to track whether future disclosures support or challenge your thesis as new results and board decisions come through.
Share your own Narrative for Willis Lease Finance and set out the assumptions behind your valuation.
One more Willis Lease Finance check that sits outside the headline valuation
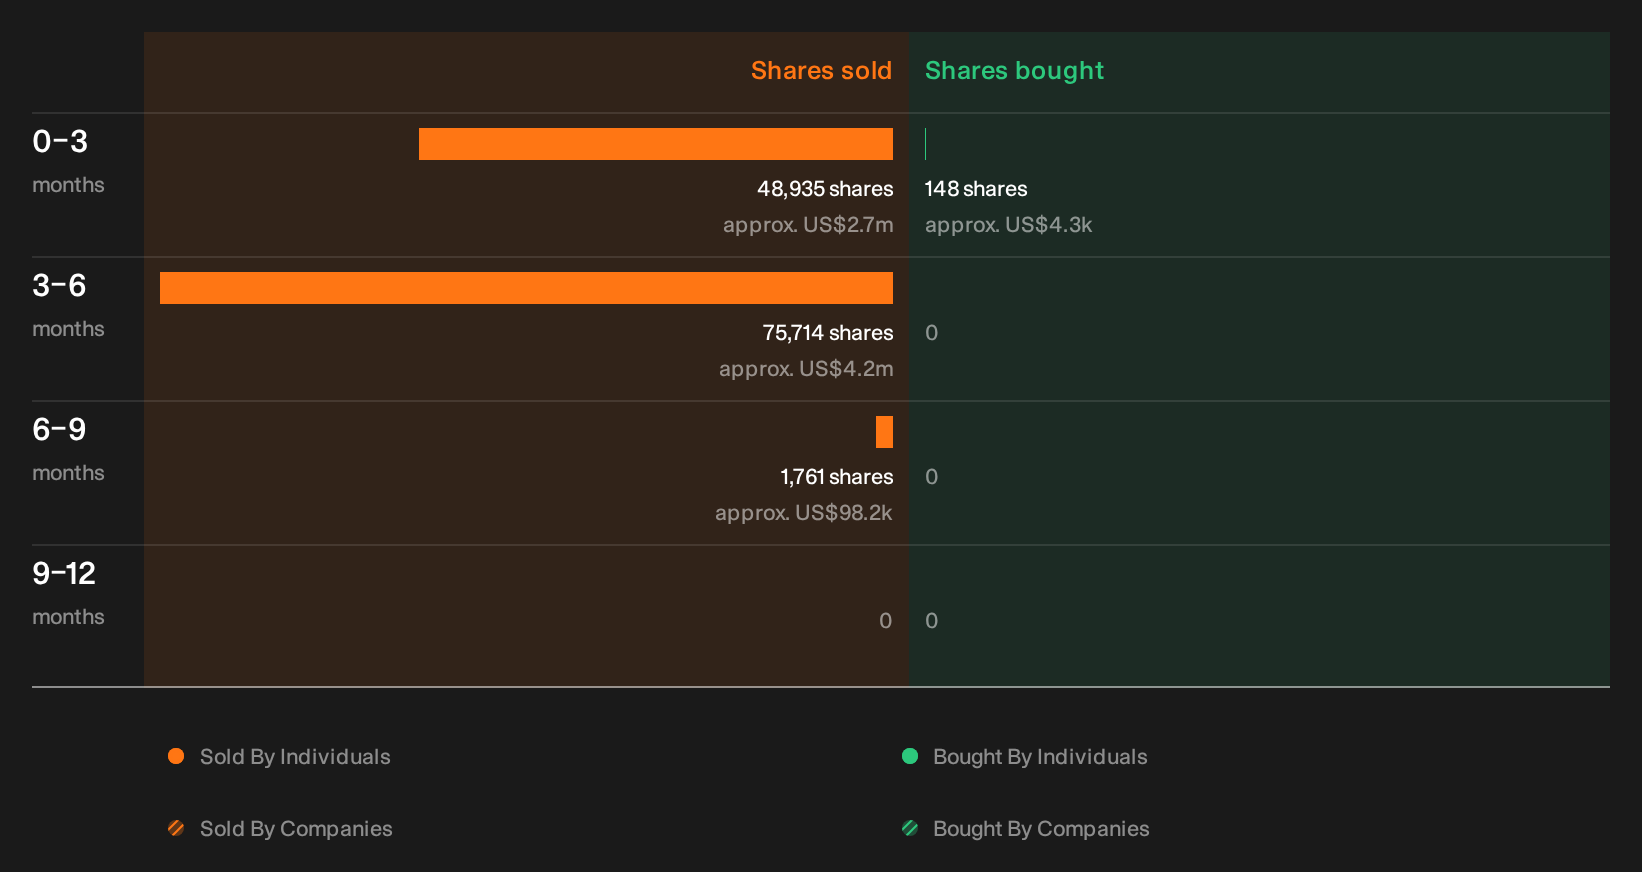
Price, earnings and governance only tell part of the story, because recent trading activity by people inside Willis Lease Finance has also been flagged by our checks and the identities, volumes and potential read through now sit waiting for you to review. See the recent insider selling flagged for Willis Lease Finance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com