


Becton Dickinson (BDX) is back under the regulatory spotlight after a December 2024 SEC order found repeated misstatements around risks tied to its Alaris infusion pump, resulting in a US$175m civil penalty.
The recent SEC order lands at a time when Becton Dickinson’s share price has already been through a sharp swing, with a 90 day share price return of 25.98%, a year to date share price decline of 6.96%, and a relatively modest 5 year total shareholder return of 2.03% that contrasts with a stronger 1 year total shareholder return of 25.59%. This indicates that momentum has picked up in the short term, while the longer multi year record remains muted.
Compare how Becton Dickinson’s recent regulatory overhang stacks up against other large caps facing scrutiny by scanning our hand picked list of 30 resilient stocks with low risk scores.
Becton Dickinson now trades about 23% below one intrinsic value estimate and roughly 8% under the average analyst target after that sharp rebound. Is this simply a discounted entry, or a warning label the market refuses to peel off?
Most Popular Narrative: 7% Undervalued
Becton Dickinson’s most followed valuation story pegs fair value near $196, a touch above the last close around $181, which puts the current discount in clear view and sharpens the focus on what might drive that gap to close.
The pending separation of the Biosciences and Diagnostic Solutions business, while touted as value-creating, introduces execution and integration risks (including stranded costs and reliance on transitional service agreements) that may lead to unforeseen costs and potential dilution to earnings. BD's strategy of continued heavy investment in selling, marketing, and innovation (fueled by BD Excellence productivity gains) carries the risk of overextending the company if new product launches or commercial initiatives underdeliver. This would be particularly relevant if macroeconomic or reimbursement environments deteriorate, potentially affecting future earnings growth.
See why 24 investors see Becton Dickinson as 7% undervalued.
Result: Fair Value of $195.67 (UNDERVALUED)
Still, the Alaris related regulatory scrutiny and the execution risk around separating the Biosciences and Diagnostic Solutions unit could easily derail the current Becton Dickinson upside story.
Find out about the key risks to this Becton Dickinson narrative.
Another View On Becton Dickinson Valuation
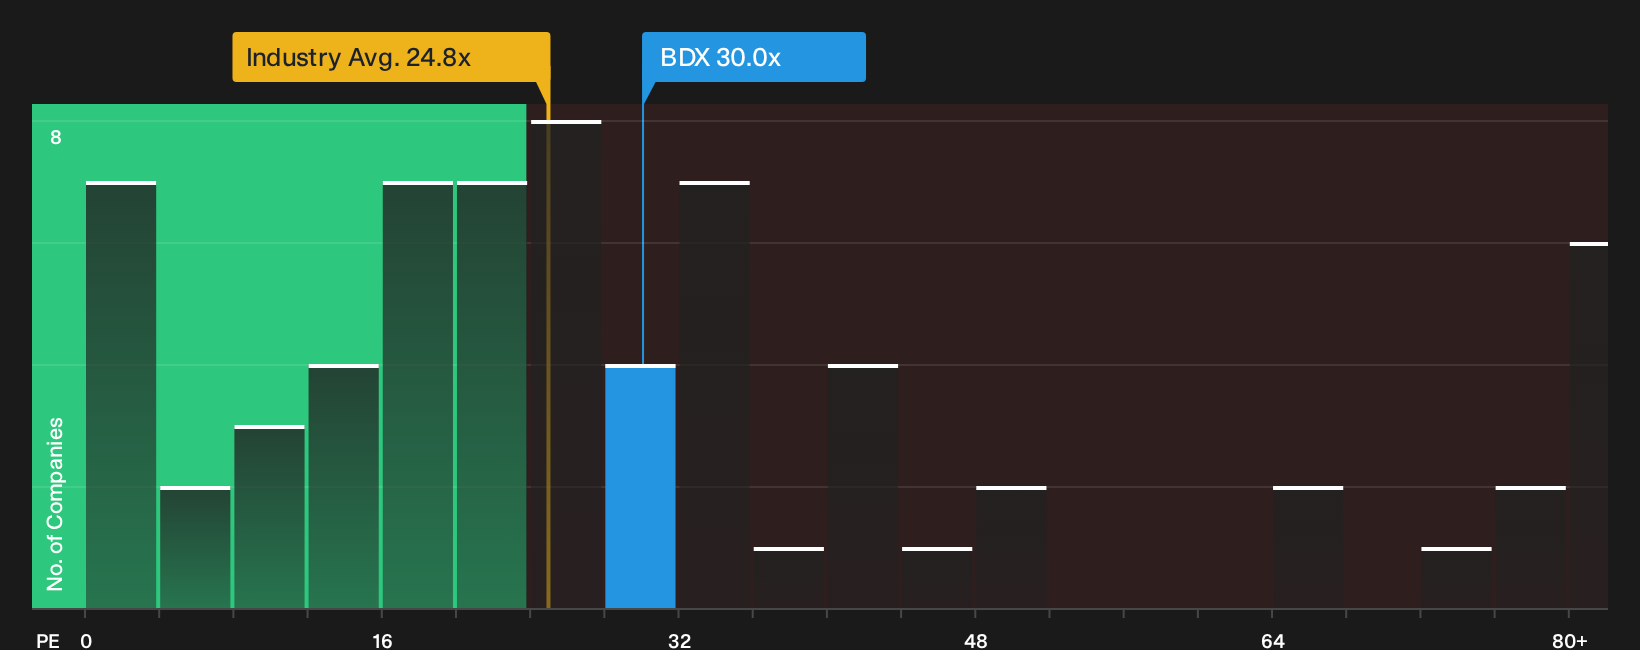
On simple P/E math, Becton Dickinson tells a very different story. The stock trades around 30x earnings, which is richer than the US Medical Equipment sector at 24.8x, yet still below a fair ratio estimate of 40.2x. That gap highlights both upside potential and rerating risk if sentiment changes.
To assess how firmly the numbers support this P/E perspective, review the valuation breakdown in our fair ratio work and then decide how much of that gap you are comfortable underwriting. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Becton Dickinson story so far. Move quickly, review the numbers carefully yourself, and weigh both sides of the ledger with 4 key rewards and 2 important warning signs.
Looking for more Becton Dickinson investment ideas?
Before closing the tab, give yourself an edge by scanning a few high quality shortlists on the Simply Wall Street Screener so you do not miss alternatives.
- Jump on opportunities where quality and valuation meet by checking companies flagged as 29 high quality undervalued stocks.
- Build defense into your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle shocks when conditions change.
- Get ahead of the crowd by filtering for 16 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com