


Sodexo (ENXTPA:SW) has been active in the market for its own shares, executing treasury purchases between 7 and 11 September 2026 under its existing buyback program to meet free share award commitments.
Those buybacks come at a time when Sodexo’s momentum has been building, with a 1-day share price return of 2.93% contributing to a 35.06% year-to-date share price gain and a 42.40% total shareholder return over five years, despite a slightly negative 3-year total shareholder return.
Scan how Sodexo’s buyback activity compares with other companies showing strong recent moves by reviewing the curated 169 high quality undervalued stocks that combines quality fundamentals with compressed valuations.
Bulls see Sodexo’s buybacks and recent 35% year to date jump as proof of a solid reset. Bears point to weaker 3 year returns and valuation risk. Which case does the data actually lean toward?
Most Popular Narrative: 11% Undervalued
The most followed narrative puts Sodexo’s fair value at €65, compared with the last close at €58.05. This means the current buyback sits inside a story that already assumes some upside is on the table and hinges on execution of longer term contract and margin plans.
While analysts broadly agree that the ramp-up of key Healthcare contracts like Captis will drive revenue in fiscal year 2026 and beyond, management's tone and specific details around exclusive ten-year partnerships, over €100 million revenue commitments in the first two years, and a €1.5 billion total pipeline suggest that this contribution could be materially higher and more durable than consensus expects, supporting a structural step-up in top-line and long-term cash flows.
See why 3 investors see Sodexo as 11% undervalued.
Result: Fair Value of €65 (UNDERVALUED)
Still, if Sodexo’s digital rollout continues to lag or client concentration in North America bites harder, that upbeat €65 narrative could quickly look stretched.
Find out about the key risks to this Sodexo narrative.
Another View On Sodexo’s Valuation
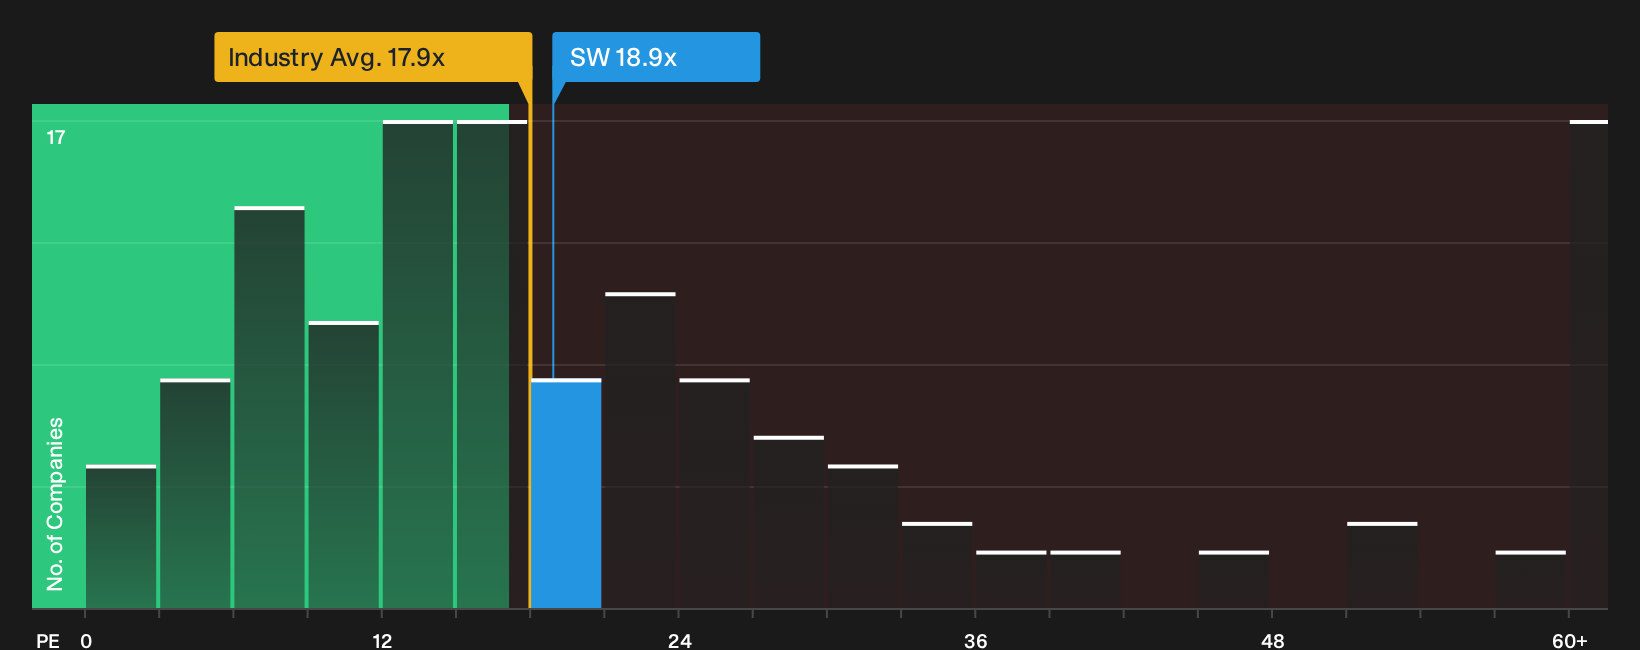
The bullish fair value story puts Sodexo at €65 with an 11% gap to the last close. A different yardstick tells a cooler story. On our numbers, Sodexo trades on a P/E of 18.9x, which is below the estimated fair ratio of 23.8x and far below the 63.5x peer average. That mix signals some room for re-rating on fundamentals while still leaving the stock slightly more expensive than the broader European Hospitality sector at 18x. This raises the question of how much weight to place on sector norms versus peer and fair ratio signals when judging potential upside and downside.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sodexo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 169 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sodexo’s valuation and recent buybacks make this a good time to move quickly, dig into the underlying data, and test whether the current price really matches your own risk and reward expectations with the help of 1 key reward and 3 important warning signs.
Looking for more Sodexo-sized ideas?
Do not stop your research with Sodexo. Broaden your watchlist with focused stock lists that surface different types of opportunities before the crowd pays attention.
- Target income first by reviewing a curated group of businesses built around resilient payouts through the 158 dividend fortresses.
- Hunt for mispriced quality and scan a 616 high quality undiscovered gems that many investors may be overlooking right now.
- Prioritise resilience and capital protection by checking a 227 resilient stocks with low risk scores that highlights companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com