


Grocery Outlet Holding (GO) just posted second quarter 2026 results, with net sales up 1.1%, comparable-store sales slipping 0.3%, higher full year guidance, and a net loss driven by a large non cash goodwill impairment.
Grocery Outlet Holding’s share price has been rebuilding some short term momentum, with a 1-day share price return of 1.4%, a 7-day gain of 4.9%, and a 90-day move of 25.5% to US$11.62. However, the 1-year total shareholder return is still down 31.5%, pointing to a business where sentiment has improved recently but long term holders remain under pressure.
Scan beyond Grocery Outlet Holding and compare this quarter’s setup with a hand picked group of retailers and consumer stocks in the 29 high quality undervalued stocks list.
For Grocery Outlet Holding, a 25.5% rebound in three months still leaves multi year returns deeply in the red. Is most of the catch up already reflected in the price, or does the valuation still suggest further upside potential?
Most Popular Narrative: 8% Overvalued
Analysts following Grocery Outlet Holding see fair value at $10.73, which sits modestly below the recent $11.62 share price and implies a market that is already baking in a recovery story.
The stock may reflect an expectation that Grocery Outlet will successfully navigate the accelerating shift to online grocery, but their lagging digital presence and the rise of larger, tech-enabled competitors could erode foot traffic, lower transaction frequency, and ultimately impair top-line revenue growth and earnings potential.
See why 4 investors see Grocery Outlet Holding as 8% overvalued.
Result: Fair Value of $10.73 (OVERVALUED)
Still, if Grocery Outlet Holding delivers stronger comps and better SG&A leverage than analysts expect, the current overvaluation narrative could appear overly cautious.
Find out about the key risks to this Grocery Outlet Holding narrative.
Another View On Grocery Outlet Holding’s Value
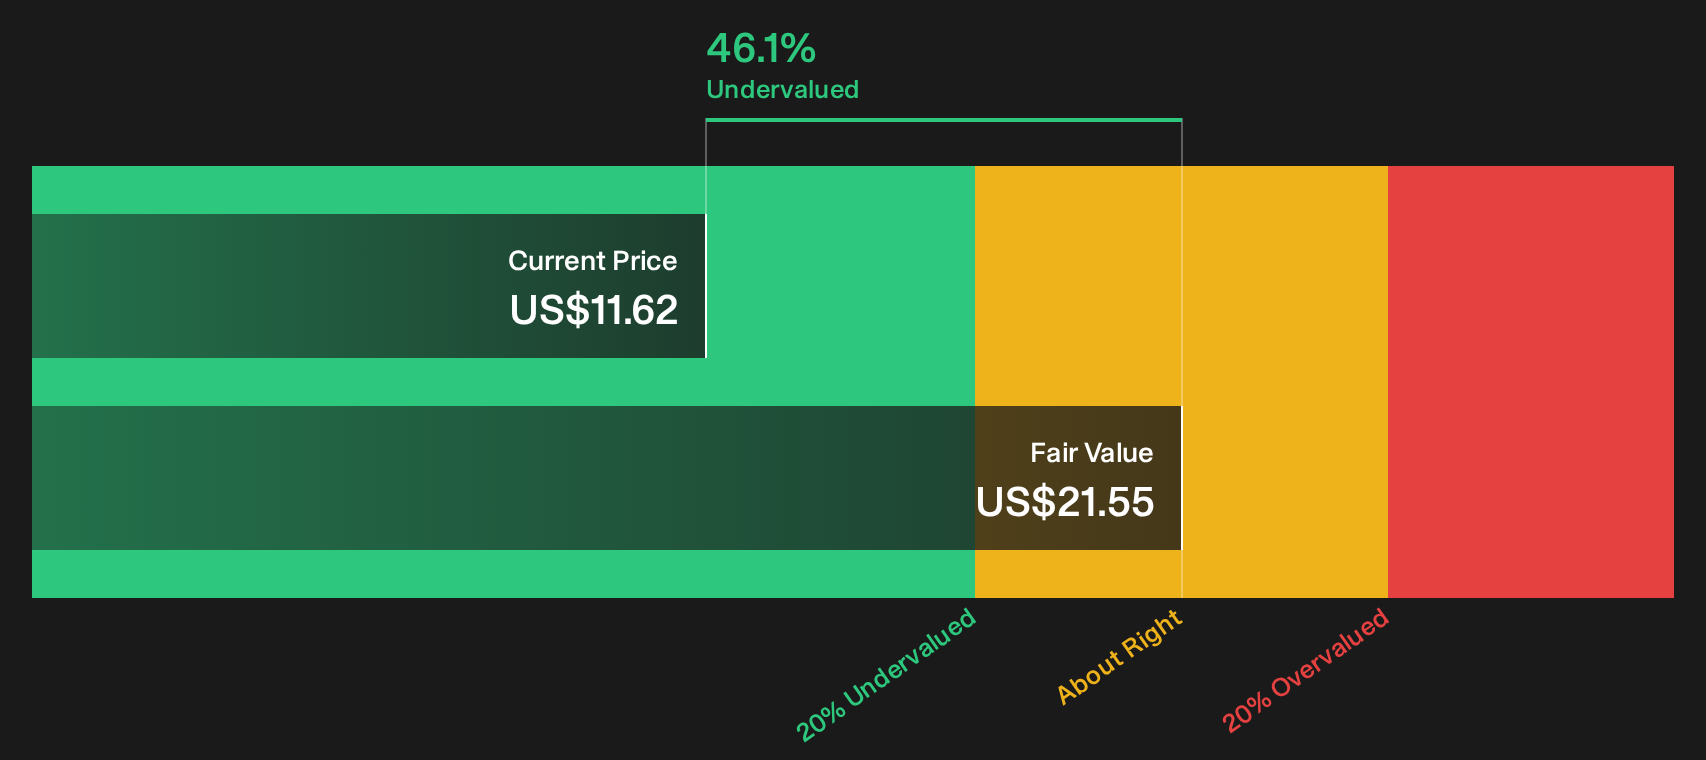
Analyst targets frame Grocery Outlet Holding as modestly overvalued at $11.62 versus a $10.73 fair value, yet our DCF model tells a different story. On future cash flows, the stock screens as trading about 46% below an intrinsic value estimate of $21.55. Which narrative feels more reasonable to you?
Our DCF model relies on explicit assumptions about future cash generation and discount rates rather than headline multiples. This approach can highlight misalignments when sentiment is weak or earnings are temporarily depressed. If you want to see how those inputs interact over time, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Grocery Outlet Holding is clearly mixed, with pressure from recent results offset by some renewed optimism in the rebound story. Act while the data is fresh in mind and stress test your own thesis using the 3 key rewards and 1 important warning sign.
Looking for more Grocery Outlet Holding style investment ideas?
If Grocery Outlet Holding has sharpened your focus, do not stop here. Use this moment to scan for fresh opportunities that fit your own investing playbook.
- Target companies that combine quality and a potential discount by starting with the 29 high quality undervalued stocks.
- Prioritise balance sheet strength and financial resilience by filtering for businesses in the list of solid balance sheet and fundamentals (23 results).
- Spot under-the-radar opportunities before the crowd by searching through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com