


- Honda Motor recently invested in US-based Niron Magnetics, which is developing rare-earth-free iron nitride permanent magnets for use across sectors including automotive and robotics, aiming to support commercialization and scaling of this technology.
- The move highlights Honda Motor’s push to diversify critical materials supply and potentially reshape future electrified powertrain design by reducing reliance on China-centric rare-earth sourcing.
- We will examine how Honda Motor's investment narrative is influenced by its backing of rare-earth-free magnet technology through its Honda Xcelerator Ventures unit.
Scan other electrification plays moving on material security themes such as Honda Motor by checking out the handpicked 37 best rare earth metal stocks that could be positioned for the next supply chain reset.
Honda Motor Investment Narrative Recap
To own Honda Motor, you need to believe the business can turn its unprofitable auto segment and heavy EV losses into a more balanced earnings profile while holding share against aggressive rivals, especially in China. The rare earth free magnet angle sits in that bigger question around whether Honda can reset its electrification economics.
Right now, the sharpest short term swing factor is execution on hybrids and EVs while containing the forecast ¥650b in EV related losses for the year to March 2026. The major near term risk is continued price pressure and tariffs that keep automobile margins weak. The Niron investment does not materially change that near term equation.
The Niron Magnetics deal is the clearest announcement tied to this theme. It sits alongside Honda Motor’s wider push into electrification technology, cost work and localization. Rare earth free magnets, if commercialized at scale, could influence future powertrain designs and component sourcing, which matters for unit economics in EVs and hybrids.
Investors tracking catalysts will likely focus more on how Honda Motor executes on localized hybrid and EV production, motorcycle profitability and cost optimization rather than on this single venture stake. The Niron move fits into the longer term materials and technology toolkit. It does not remove core risks around auto sales softness, tariff exposure or dividend coverage today.
Honda Motor Consensus Expectations In Context
Honda Motor's narrative projects ¥25,176.4b revenue and ¥1,013.3b earnings by 2029. This implies 3.8% yearly revenue growth and an earnings increase of about ¥1,183.0b from earnings today of a ¥169.7b loss.
Uncover why Honda Motor's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate angle puts trade risk ahead of everything else. The most cautious Honda Motor analysts were pencilling in flat revenue near ¥22,756.6b and earnings around ¥825.8b by 2029, well below consensus. Those views came before the Niron deal and the ACI NA presentation, so you can expect some of these narratives to evolve.
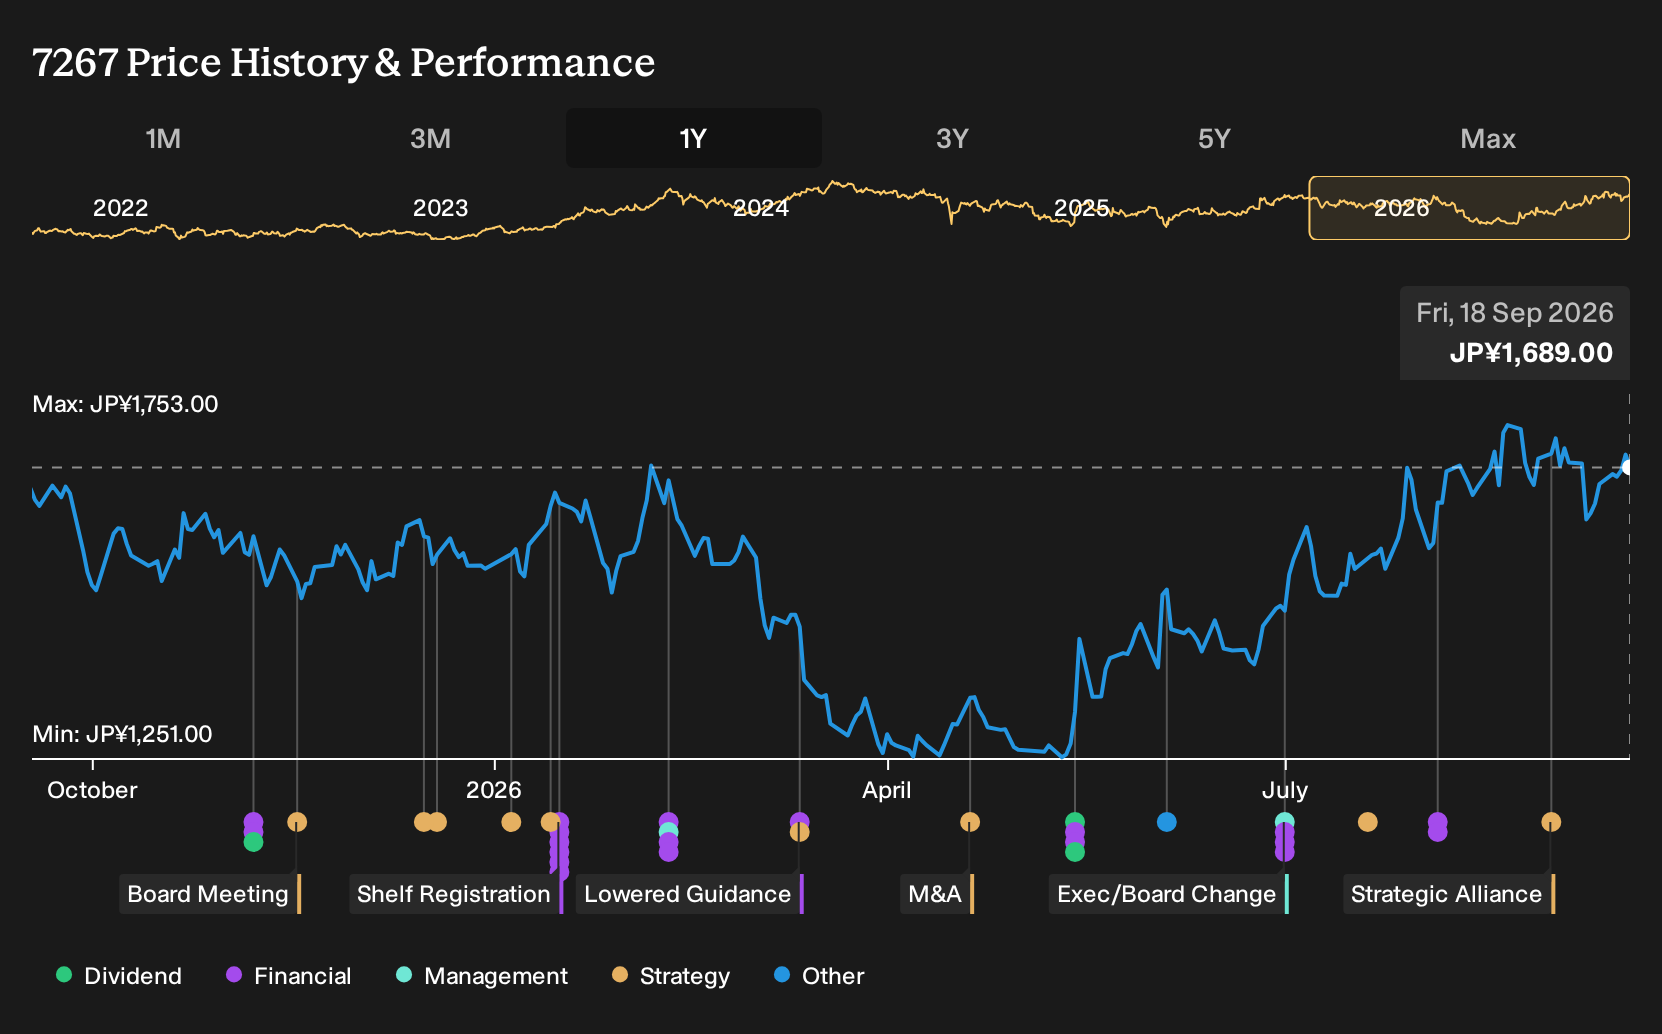
Explore 2 other Honda Motor fair value estimates, including one that suggests it could be worth just ¥1688.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Honda Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Honda Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Honda Motor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Honda Motor?
Once you have a view on Honda Motor, it often helps to widen the lens and compare it with other potential opportunities that line up with your risk profile and income needs.
- If you want potential growth with a small starting price tag, check out 1 elite penny stocks with strong financials, which combine tiny market values with stronger fundamentals than many peers.
- For investors who care most about quality at a reasonable entry point, take a look at 17 high quality undervalued stocks, which balance solid cash generation with more conservative balance sheets.
- Income focused readers who prefer steadier profiles can scan 21 resilient stocks with low risk scores, which screen for more resilient businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com