


Equinor (OB:EQNR) has entered the lithium conversation after partner Smackover Lithium released a positive Preliminary Economic Assessment for the Franklin brine project in East Texas, outlining sizeable long-life resource potential.
Equinor’s lithium exposure comes on top of a strong run in its core business, with the share price at NOK419.0 and a 90 day share price return of 32.43% contributing to an 80.78% 1 year total shareholder return. This suggests momentum that has been building rather than fading over both shorter and longer horizons.
Scan beyond Equinor’s lithium move and energy footprint by checking a curated set of resilient peers in our 227 resilient stocks with low risk scores that have already cleared strict risk filters.
After a near 81% 1 year total return and fresh lithium optionality, the question sharpens: Does Equinor’s current valuation still leave enough upside to justify the risk buyers take from here?
Most Popular Narrative: 20% Overvalued
On the most followed view, Equinor screens as overvalued, with a fair value of NOK349 versus the last close at NOK419. This puts the current rally against a lower narrative anchor built on a 6.65% discount rate.
Equinor faces overvaluation risk due to optimistic assumptions around both oil & gas demand and rapid, profitable renewables growth amid regulatory and margin pressures.
High returns and shareholder payouts may be unsustainable, as legacy assets mature, capex needs rise, and tightening ESG regulations limit growth and investment capacity.
See why 92 investors see Equinor as 20% overvalued.
Result: Fair Value of NOK349 (OVERVALUED)
Still, if Equinor executes major projects efficiently and long term gas contracts support cash flows, that could weaken arguments that the shares are overvalued.
Find out about the key risks to this Equinor narrative.
Another View On Equinor’s Valuation
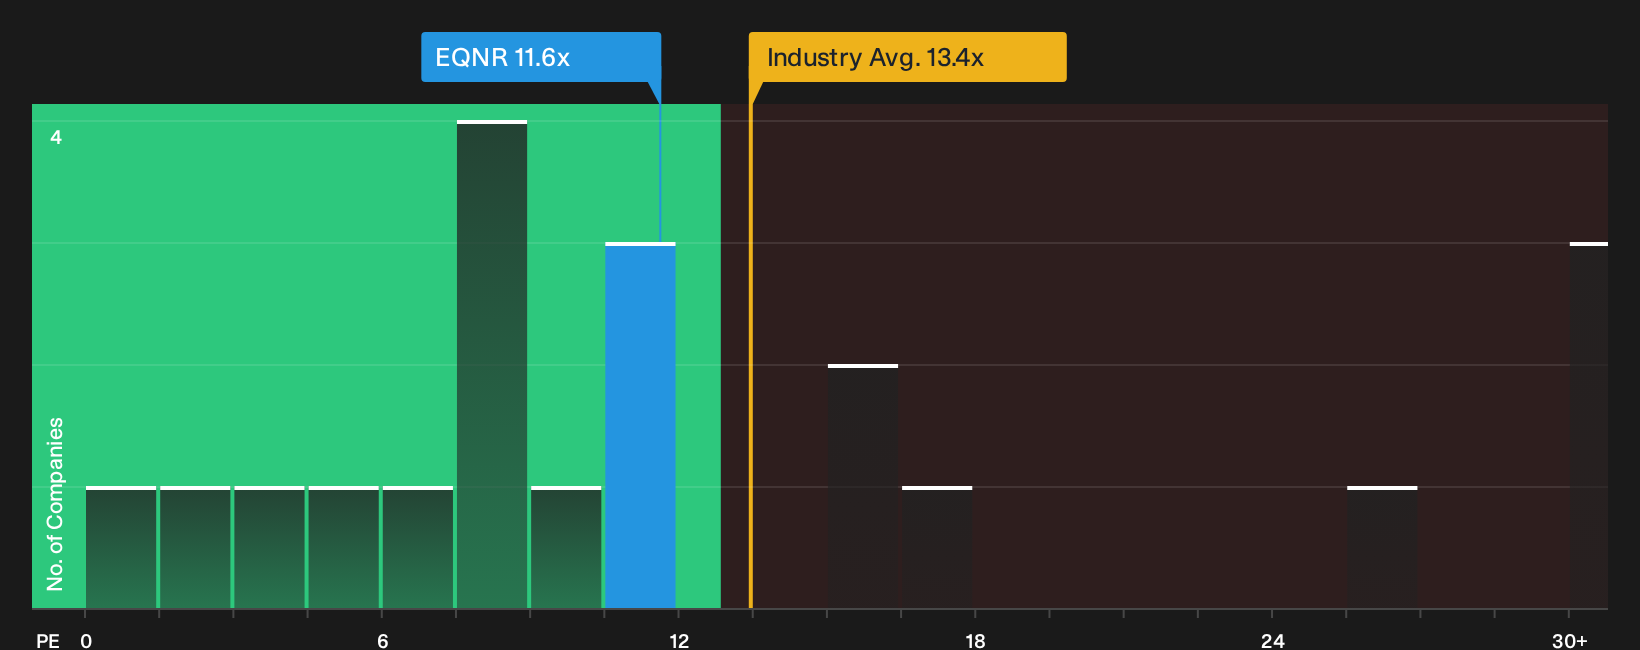
Analysts see Equinor as about 20% above their NOK349 fair value, yet the current P/E of 11.6x looks cheaper than both peers at 13.6x and the European Oil and Gas group at 13.4x. With a fair ratio of 12.1x, is the market leaving less downside than the narrative suggests?
Investors weighing these conflicting signals may want to stress test how much earnings risk they are really pricing in before leaning on this valuation gap as comfort. They can then sense check that view against the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Equinor is split, with clear risks on one side and meaningful potential on the other. Move quickly and test the numbers yourself using the 2 key rewards and 2 important warning signs.
Looking For More Equinor-Sized Investment Ideas?
If Equinor has sharpened your focus on risk, reward, and pricing, do not stop here. Fresh ideas now can change your portfolio’s path.
- Target dependable value by scanning a curated 169 high quality undervalued stocks that blends solid fundamentals with pricing that still leaves room for a thesis.
- Build a sturdier core in your holdings with a list of solid balance sheet and fundamentals (196 results) that can better withstand shocks when conditions turn.
- Get ahead of the crowd by tracking a 616 high quality undiscovered gems before wider attention potentially tightens the opportunity set.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com