


- WESCO International was recently upgraded to a Zacks Rank #1 after analysts raised earnings estimates, reflecting greater confidence in its current business outlook and underlying operations.
- The upgrade highlights how earnings expectations are catching up with WESCO International’s expanding role in power infrastructure and data center projects, rather than relying only on sentiment around the stock.
- We will now assess how this upgraded earnings outlook for WESCO International could reshape the broader investment narrative around its growth drivers.
Scan beyond WESCO International and track other power and infrastructure suppliers seeing earnings sentiment shift with our hand-picked 37 power grid technology and infrastructure stocks.
WESCO International Investment Narrative Recap
For an investor in WESCO International, the core belief is that spending on power infrastructure, utilities and data centers keeps translating into steady project flow across its three segments. The short term swing factor is how quickly that record style backlog in power intensive and data center projects converts into actual shipments and services.
The biggest operational risk is concentration in large, multiyear awards and AI focused data centers. Project delays, tighter labor or power constraints, or a pause in hyperscale build outs could slow revenue and keep working capital needs high. The recent earnings optimism upgrade does not change that execution risk; it reflects confidence in handling it.
The Zacks Rank upgrade ties most directly to the same factors investors already track. WESCO International is leaning into AI and cloud data center demand, power infrastructure projects and higher margin life cycle services. Analyst estimate revisions mainly signal rising comfort with how these themes are flowing through to earnings rather than introducing a new operational driver.
In practical terms, this makes execution on large Grid Services contracts and data center solutions the key catalyst to watch. Any evidence that project backlogs are converting on schedule, while working capital intensity is controlled and acquisitions like Newark Engineering are integrated cleanly, would matter more for the story than the rating change itself.
What The New WESCO International Forecasts Assume
WESCO International's current analyst framework points to revenues of US$30.2b and earnings of US$1.2b by 2029. That path assumes revenue grows at about 6.5% per year and earnings rise by roughly US$484.6m from today’s US$715.4m level.
Uncover why WESCO International's fair value indicates a 17% potential upside to its current price that could narrow quickly.
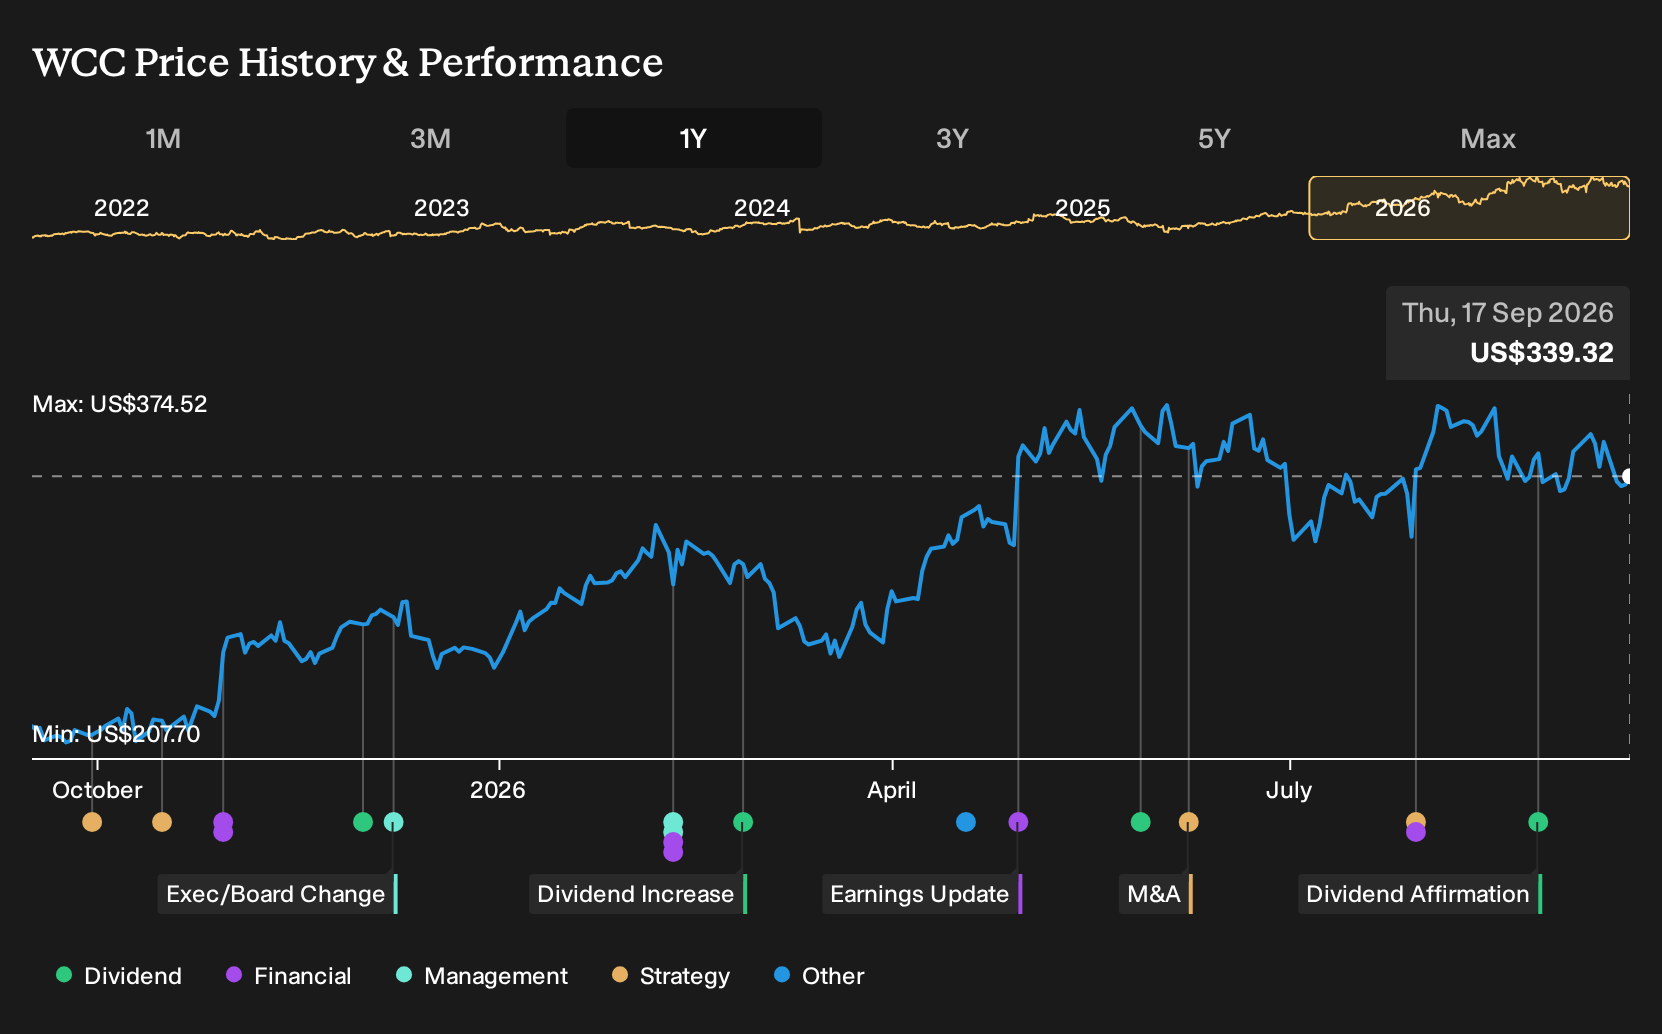
Exploring Other Perspectives
One alternate view leans hard into AI driven data centers as the real swing factor for WESCO International. Before this Zacks Rank upgrade, the most optimistic analysts were already working off roughly US$29.7b in 2029 revenue and US$1.2b in earnings. That is a far brighter script than consensus, and it may shift again as you compare fresh opinions against this news.
Explore 2 other WESCO International fair value estimates, including one that indicates potential upside of up to 78% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and research.
- A great starting point for your WESCO International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WESCO International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WESCO International's overall financial health at a glance.
Looking For More Investment Ideas Beyond WESCO International?
Once you have formed a view on WESCO International, it can be useful to compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener is built for exactly that, letting you filter the market by balance sheet strength, dividend profile, valuation and more in a few clicks.
- If you care most about resilient businesses with fewer red flags, start by scanning a set of 30 resilient stocks with low risk scores that keep risk scores in focus.
- For investors who want quality at a reasonable entry point, review a curated 29 high quality undervalued stocks that combine solid fundamentals with pricing that may look attractive on the numbers.
- If your priority is financial strength and durability, compare WESCO International against a list of solid balance sheet and fundamentals (23 results) so you can quickly spot companies with cleaner leverage and stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com