


Executive changes and earnings sentiment around Crown Castle
Fresh optimism around Crown Castle (CCI) has been sparked by an analyst upgrade tied to higher earnings estimates, putting the spotlight on how these expectations line up with recent leadership moves.
The rating shift reflects revised profit forecasts that some investors see as a signal of confidence in the business. It arrives as Crown Castle prepares for a measured transition in senior finance and operating roles over the next year.
Crown Castle’s share price has softened over 2026, with the stock down 16.9% year to date and recording a 10.1% decline over 90 days. The 1-year total shareholder return is also lower, which suggests current optimism is emerging against a backdrop of fading longer term momentum.
Scan how Crown Castle’s earnings reset compares with peers by reviewing a curated set of 29 high quality undervalued stocks that currently pair solid cash flows with stronger share price momentum.
Crown Castle trades at US$73.74 while analyst targets cluster near US$94.82, and one intrinsic estimate points to an even wider gap. Is the recent upgrade catching up to fair value, or getting ahead of it?
Most Popular Narrative: 23% Undervalued
Crown Castle’s most followed narrative points to a fair value of $96.12 against a last close of $73.74, putting the current upgrade debate in the context of a sizeable valuation gap built on tower focused assumptions and capital returns.
The decision to sell the fiber segment and become a pure-play U.S. tower company could unlock substantial value in the tower business by enhancing focus on operational excellence, customer service, and improved profitability, potentially driving higher revenue and net margins.
Crown Castle's plan to repurchase shares with the proceeds from the fiber segment sale, alongside a dividend strategy, suggests a disciplined capital allocation framework likely to enhance shareholder returns and Earnings Per Share (EPS) over time.
See why 42 investors see Crown Castle as 23% undervalued.
Result: Fair Value of $96.12 (UNDERVALUED)
Still, the narrative around Crown Castle could change quickly if regulatory delays around the fiber sale stretch out or if Sprint and DISH related churn hits tower revenue harder than expected.
Find out about the key risks to this Crown Castle narrative.
Another View on Crown Castle’s valuation
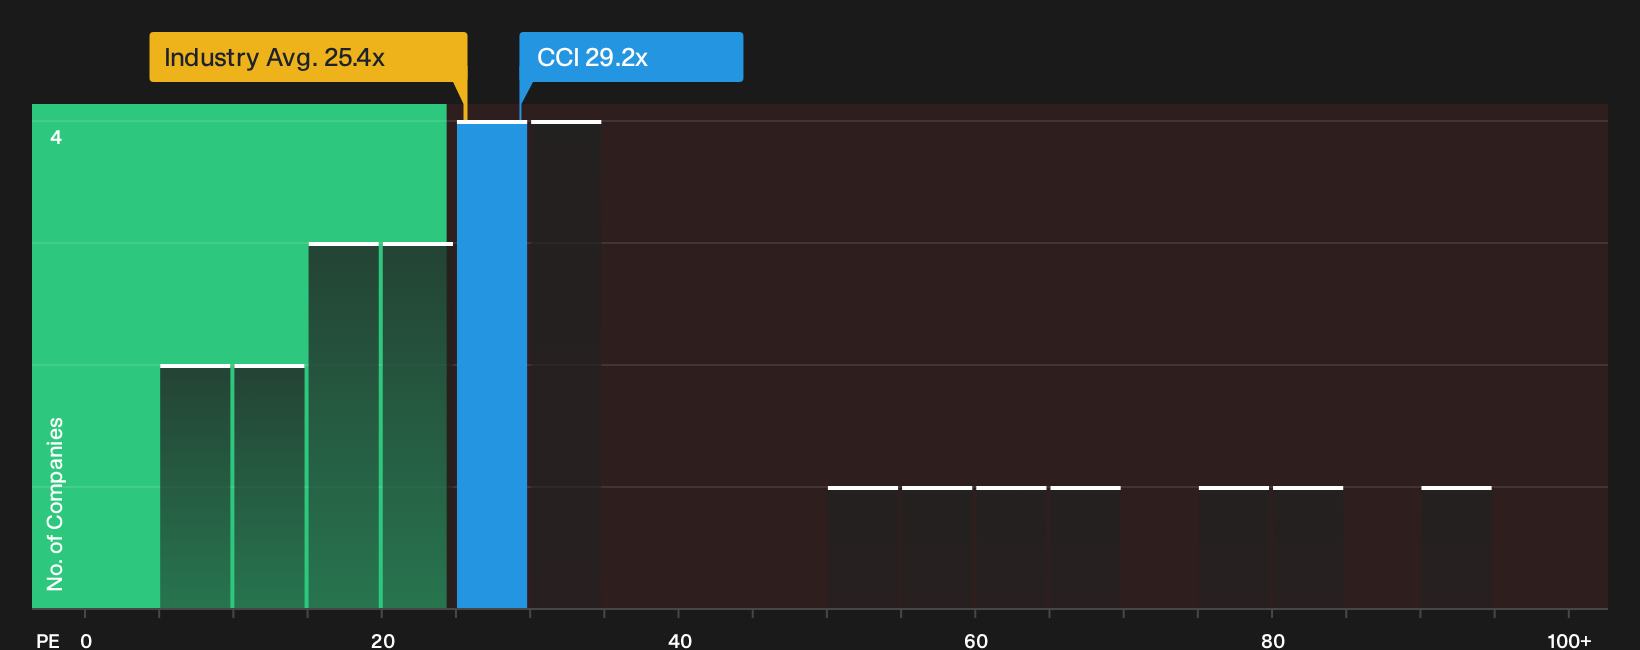
On price multiples, Crown Castle does not look cheap. The stock trades on a P/E of 29.2x, which is higher than the North American Specialized REITs group at 25.5x, even though analysts see slower earnings and revenue growth than the broader US market.
The fair ratio for Crown Castle is 39x. This implies the market could move toward a higher earnings multiple over time. That gap hints at upside if sentiment shifts, but it also leaves room for disappointment if growth or cash generation falls short of current expectations.
To see how this valuation gap has been framed using earnings and industry comparisons, take a closer look at the detailed multiple breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone around Crown Castle has you on the fence, review the numbers yourself and act promptly to form your own takeaway using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Crown Castle?
If Crown Castle has your attention but you want a broader watchlist, use these focused stock lists to quickly surface ideas that fit different goals.
- Target potential mispricing by scanning companies with strong fundamentals and valuation support using the 29 high quality undervalued stocks.
- Build a steadier income stream by reviewing higher yielding options that feature in the 6 dividend fortresses.
- Prioritise resilience by zeroing in on companies with healthier finances through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com