


Intellia Therapeutics (NTLA) is back in focus after the FDA accepted its Biologics License Application for lonvo-z and granted Priority Review, a key regulatory step for this CRISPR-based hereditary angioedema therapy.
Investors have responded quickly to the lonvo-z update, with Intellia Therapeutics’ share price gaining 6.7% over the past day and posting a 33.12% year-to-date share price return, although the 1-year total shareholder return has declined 23.9%, pointing to momentum rebuilding after a much tougher few years.
Scan beyond Intellia Therapeutics and consider other gene editing and high science plays with resilient balance sheets using our curated list of solid balance sheet and fundamentals (23 results).
Intellia Therapeutics now trades at a steep discount to both intrinsic value estimates and analyst targets, even after the lonvo-z bounce. Is that a safety margin or a warning label on market caution?
Most Popular Narrative: 49% Undervalued
Intellia Therapeutics trades at $12.26 against a widely followed fair value view of about $23.94, so the current pricing assumes plenty of risk even as the story leans on aggressive growth and margin expectations.
Improving financial discipline, as evidenced by successful restructuring, declining GAAP operating expenses (~10% reduction YoY), and a robust cash runway into the first half of 2027, enables Intellia to absorb increased R&D investment, advance pipeline expansion, and build out commercial infrastructure without dilutive fundraising. This supports protection of net margins and improves future earnings visibility.
See why 84 investors see Intellia Therapeutics as 49% undervalued.
Result: Fair Value of $23.94 (UNDERVALUED)
Still, Intellia Therapeutics faces real pressure if late stage trials stumble or if high R&D spend and ongoing losses force more aggressive funding decisions.
Find out about the key risks to this Intellia Therapeutics narrative.
Another View: Intellia Therapeutics Through a Sales Multiple Lens
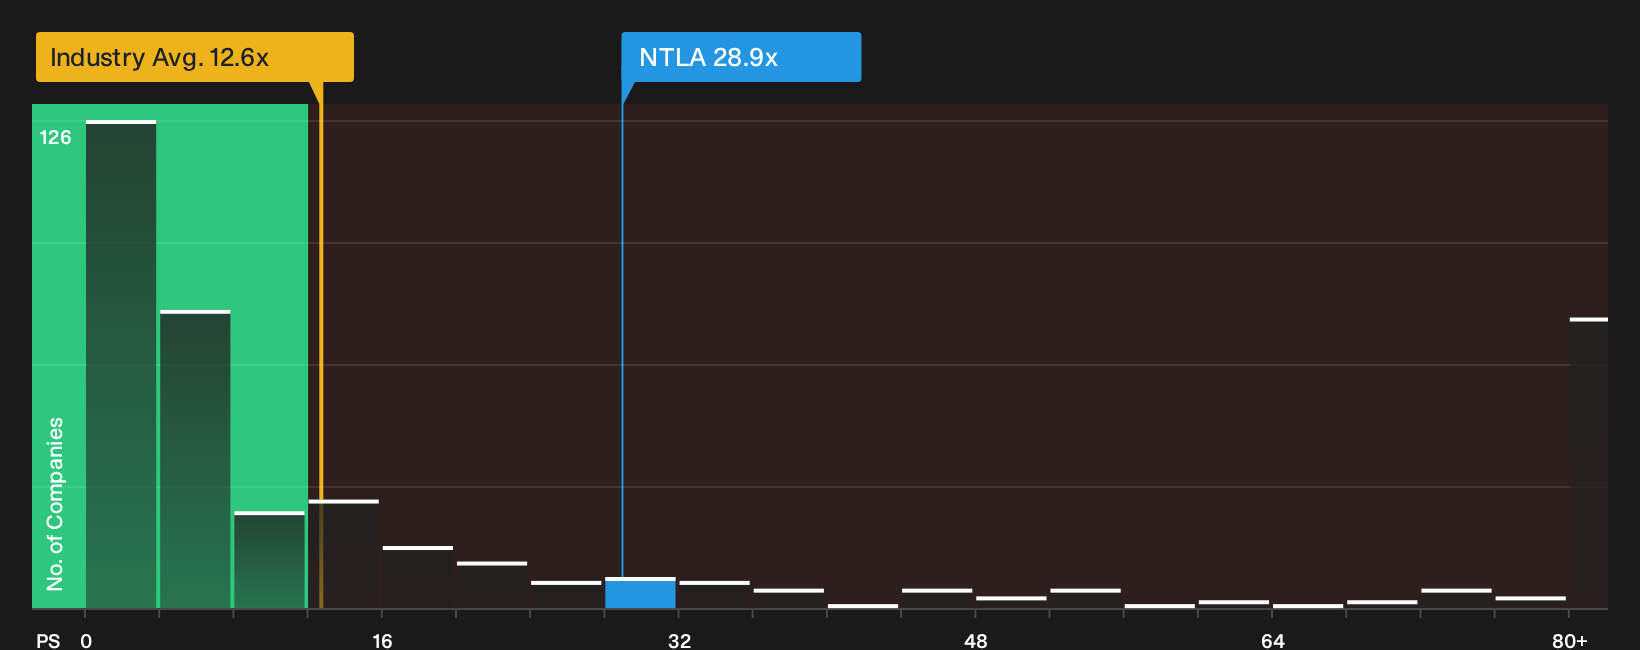
The SWS fair value work points to Intellia Therapeutics looking deeply undervalued, yet the simple sales multiple tells a very different story. NTLA trades on a P/S of 28.9x, above both peers at 23.6x and the US Biotechs average at 12.6x. This is also far above the fair ratio estimate of 0.1x. That gap suggests real valuation risk if sentiment cools or revenue forecasts are cut. The key question is which signal to focus on.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Intellia Therapeutics so far, right? If you want to move quickly and form your own judgement, consider weighing both sides of the story through 2 key rewards and 2 important warning signs.
Looking for more Intellia Therapeutics style ideas?
If Intellia Therapeutics has sharpened your appetite for high conviction opportunities, do not stop here. Fresh ideas often appear where most investors are not yet looking.
- Target potential mispricings by scanning companies that combine quality fundamentals with appealing entry prices through our 29 high quality undervalued stocks.
- Strengthen your downside protection by reviewing a 30 resilient stocks with low risk scores that focuses on businesses with more resilient profiles and fewer balance sheet surprises.
- Get ahead of the crowd by tracking a 16 high quality undiscovered gems before broader attention and capital start to follow the same stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com