


Baldwin Insurance Group has been in focus after a solid year to date share price run and a proposed take private deal, which naturally puts the spotlight on whether the current valuation can be explained by its sales base. With the stock now trading close to the cash offer level, the question for investors is how much of Baldwin Insurance Group's revenue power is already reflected in the price.
- The share price is up 34.4% year to date, which raises the stakes on whether that gain is supported by the scale and growth trajectory of its sales.
- The pending US$7.7b take private offer at US$32.50 per share and the related fairness review may support closer scrutiny of how Baldwin Insurance Group's revenue profile lines up with that transaction value.
- There is a second opinion on Baldwin Insurance Group worth weighing. See what analysts think Baldwin Insurance Group's shares could be worth.
The issue now is whether Baldwin Insurance Group's current share price is adequately backed by the sales it generates today and what investors reasonably expect those revenues to look like over time.
If you want context for Baldwin Insurance Group's take private price and sales based valuation, it can help to compare against other solid balance sheet and fundamentals stocks screener (23 results)
Has Baldwin Insurance Group Run Too Far on Sales?
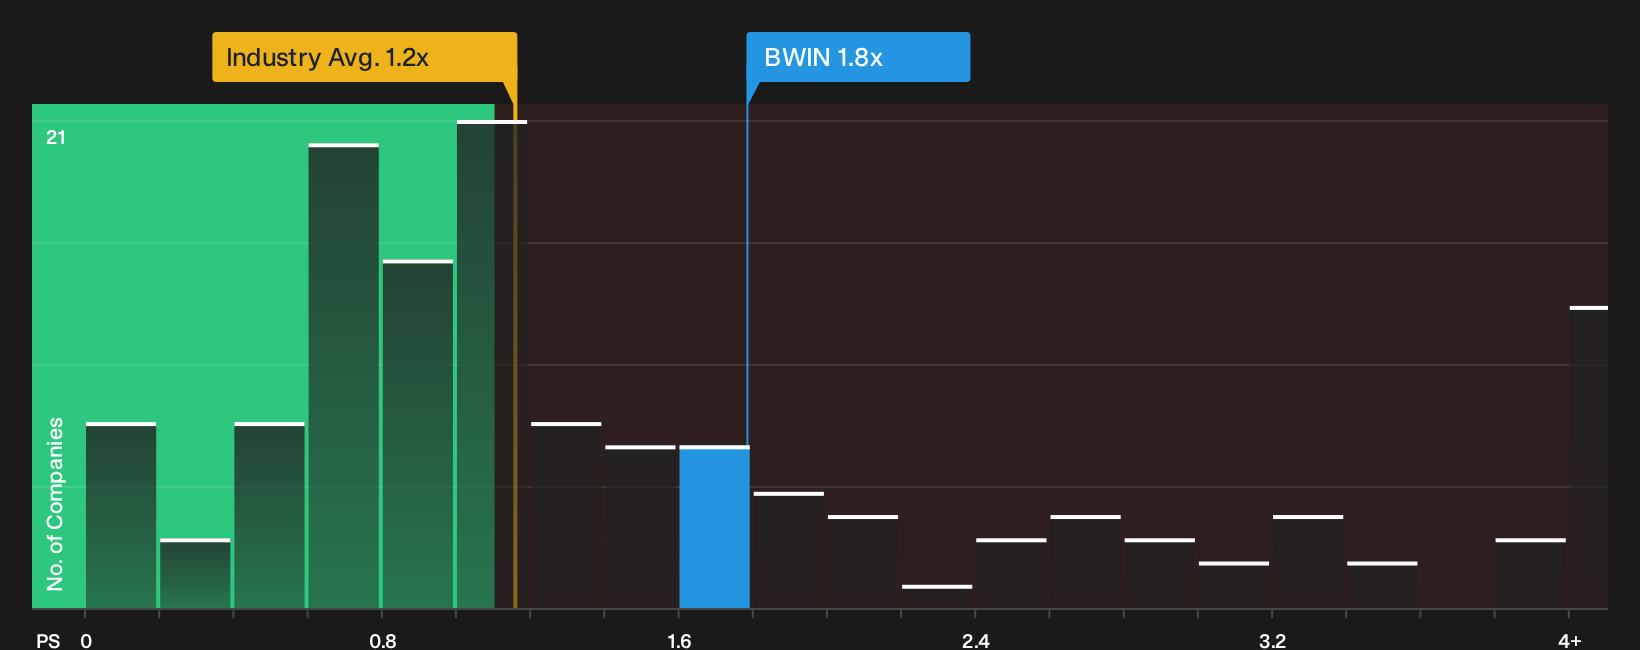
P/S is often the cleaner lens for Baldwin Insurance Group because insurance distribution leans heavily on revenue scale and recurring client relationships. On this measure, the stock trades on a P/S of 1.8x, compared with an Insurance industry average of about 1.2x and a peer group closer to 7.9x. That gap to peers is large, while the premium to the wider sector is much smaller, which leaves the shares looking neither like a bargain nor an outlier purely on a simple market snapshot.
The fair value framework, which adjusts the multiple you might expect for Baldwin Insurance Group given its margins, risk profile and size, points to the current 1.8x P/S as overvalued. Because the proposed US$32.50 per share take private price has pulled the stock toward that bid, the market is effectively endorsing a richer revenue tag than this tailored yardstick would imply. For anyone weighing whether that takeover level builds in enough compensation for execution and integration risks over time, it is worth exploring how much optimism is embedded in that P/S gap to the model. Explore the numbers behind Baldwin Insurance Group's P/S valuation.
The Baldwin Insurance Group Narrative: What Would Justify Today's Price?
Narratives for Baldwin Insurance Group pick up where this valuation puzzle leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the stock to trade meaningfully above or below today's price on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each narrative lays out the specific assumptions behind its estimate of fair value so you can compare those expectations with the numbers Baldwin Insurance Group actually reports over time.
Community views on Baldwin Insurance Group are now split between those who see deal-driven mispricing and those who think expectations already stretch the story.
Bull case: 14% undervalued
"Complete extinguishment of earnout liabilities, coupled with deferral of cash taxes for several years due to strong NOLs and interest deductibility, will unlock a powerful free cash flow surge and new capital deployment options…"
Discover why this Narrative puts Baldwin Insurance Group at 14% undervalued.
Bear case: 14% overvalued
"The rapid acceleration of digital transformation and insurtech innovation across the insurance value chain continues to threaten traditional brokers, and Baldwin's investments in proprietary technology may not keep pace with disruptive competitors offering direct to consumer digital experiences…"
Explore why this Narrative puts Baldwin Insurance Group at 14% overvalued.
The price of Baldwin Insurance Group is only one piece of your decision
Shares can only reflect so much when the real steering is done by the people in charge, and how those executives are rewarded can tilt their choices in ways you need to understand. See who runs Baldwin Insurance Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com