


Littelfuse (LFUS) is in focus after management outlined a long runway for a leadership transition, with longtime executive Deepak Nayar retiring in 2027 and Karim Hamed taking an expanded senior role.
Littelfuse shares trade at US$407.88 after a 1-day share price return of 1.50%, although momentum has cooled recently with the 7-day share price return down 5.65% and the 90-day share price return down 14.99%. The 1-year total shareholder return of 56.66% points to strong longer term gains as investors weigh the leadership changes and the new Flip Electronics distribution agreement against that earlier strength.
See how Littelfuse compares with other high quality industrial and electronics plays by reviewing the curated list of solid balance sheet and fundamentals (23 results) for ideas with relatively sturdy financial footing.
Littelfuse has pulled back sharply after a strong year, and expectations around new leadership and the Flip Electronics deal are already in the price. How much of the upside is still realistically on the table?
Most Popular Narrative: 16% Undervalued
Against Littelfuse's last close at $407.88, the most followed narrative anchors on a fair value estimate of $488.75, framing the recent pullback as a discount to its modeled cash flow potential under a 9.06% discount rate.
The rapid buildout of renewable energy infrastructure, grid storage, and sustainable grid ecosystems has resulted in double-digit sales growth and a robust opportunity pipeline for Littelfuse. This is described as positioning the company to benefit from continued secular tailwinds and expanding its addressable market, which is expected to positively impact both revenues and margins.
See why 6 investors see Littelfuse as 17% undervalued.
Result: Fair Value of $488.75 (UNDERVALUED)
Still, if Littelfuse misjudges shifts in power semiconductor technology, or if cyclical auto and industrial demand weakens further, that underperformance could quickly challenge this undervaluation story.
Find out about the key risks to this Littelfuse narrative.
Another View: Littelfuse Through The P/S Lens
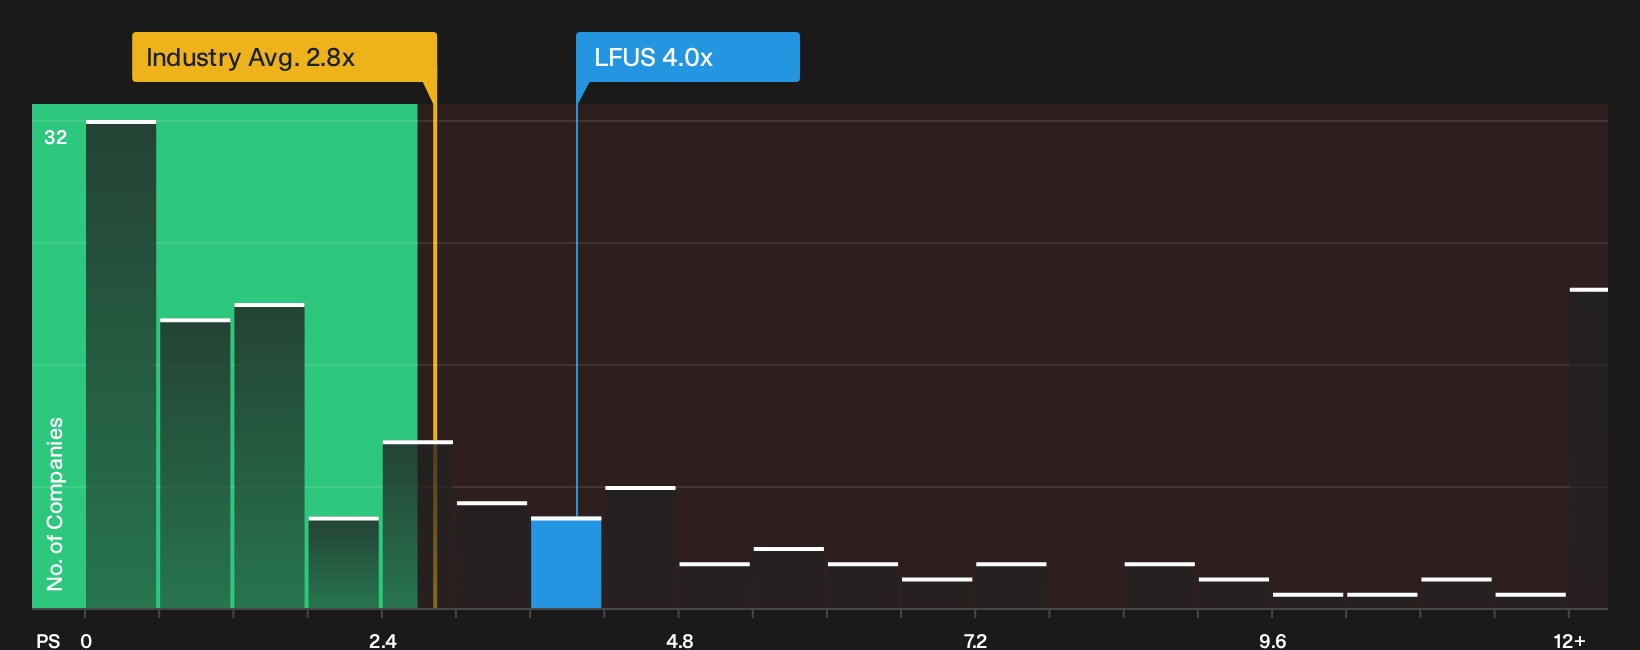
The cash flow model points to upside for Littelfuse, yet the simple P/S check tells a more cautious story. The stock trades at roughly 4x sales compared with a fair ratio of 2.7x and a peer group closer to 2.8x to 2.9x.
That gap implies investors are already paying a premium for Littelfuse relative to similar electronics businesses and where the fair ratio suggests the market could move toward. The question is whether you think the quality of the product mix and future execution justify keeping that premium in place.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages on Littelfuse leave you on the fence, move quickly from reading to testing the numbers yourself and pressure test the optimism baked into these assumptions. To see what investors are currently excited about, start with the 2 key rewards.
Looking for more Littelfuse investment ideas?
If Littelfuse has your attention, do not stop here. Broaden your watchlist with fresh opportunities that could round out your portfolio before others catch on.
- Target value first and hunt for quality companies that current prices may underestimate through the 33 high quality undervalued stocks.
- Prioritise resilience and scan for businesses with sturdier finances using the 30 resilient stocks with low risk scores.
- Get ahead of the crowd and search for early-stage opportunities with strong fundamentals through the 8 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com