


- Seagate Technology Holdings recently reported a non-GAAP gross margin of 52.7% for the June quarter, supported by a pricing strategy shift over the past three years that has nearly tripled margins while still keeping its drives a relatively small portion of cloud customers' capital budgets.
- The company’s ability to raise prices without significant customer pushback highlights how crucial its high-capacity drives are to cloud providers. Profitability is tied less to unit volumes and more to disciplined pricing and industry supply control.
- We will now explore how Seagate Technology's sustained pricing power and higher gross margins could influence the broader investment narrative around the business.
Seagate Technology Holdings Investment Narrative Recap
To own Seagate Technology Holdings, you need to believe that mass-capacity hard drives remain central to cloud and AI data growth and that disciplined pricing can sustain attractive gross margins. The June quarter non-GAAP gross margin of 52.7% supports that thesis. The key short term swing factor is whether that pricing power holds as customers scrutinise budgets.
The biggest operational risk right now sits with industry supply discipline and hyperscaler spending timing. Any break in pricing restraint or a pause in cloud buildouts due to power and permitting limits could pressure utilisation and margins. The latest margin print helps the story, but it does not erase these risks.
Recent commentary on Seagate Technology’s HAMR based Mozaic drives connects closely to this margin discussion. Higher density products potentially support the current pricing structure because they offer more capacity per rack, which matters to hyperscalers running tight data center footprints and power envelopes.
For you as an investor, the link between Mozaic adoption, build to order execution and pricing power is central. If Seagate aligns Mozaic ramp, customer agreements and disciplined supply, that combination could remain the main operational catalyst. Any misstep, whether in HAMR yields or delivery timing, would feed directly into the risk side of the thesis.
Seagate Technology Holdings' current analyst narrative points to forecast revenue of $30.5b and earnings of $16.3b by 2029. That profile assumes revenue expands at about 35.8% a year and earnings rise by about $13.1b, increasing from $3.2b today to reach the 2029 consensus figure.
Uncover why Seagate Technology Holdings' fair value indicates a 30% potential upside to its current price before the discount window narrows.
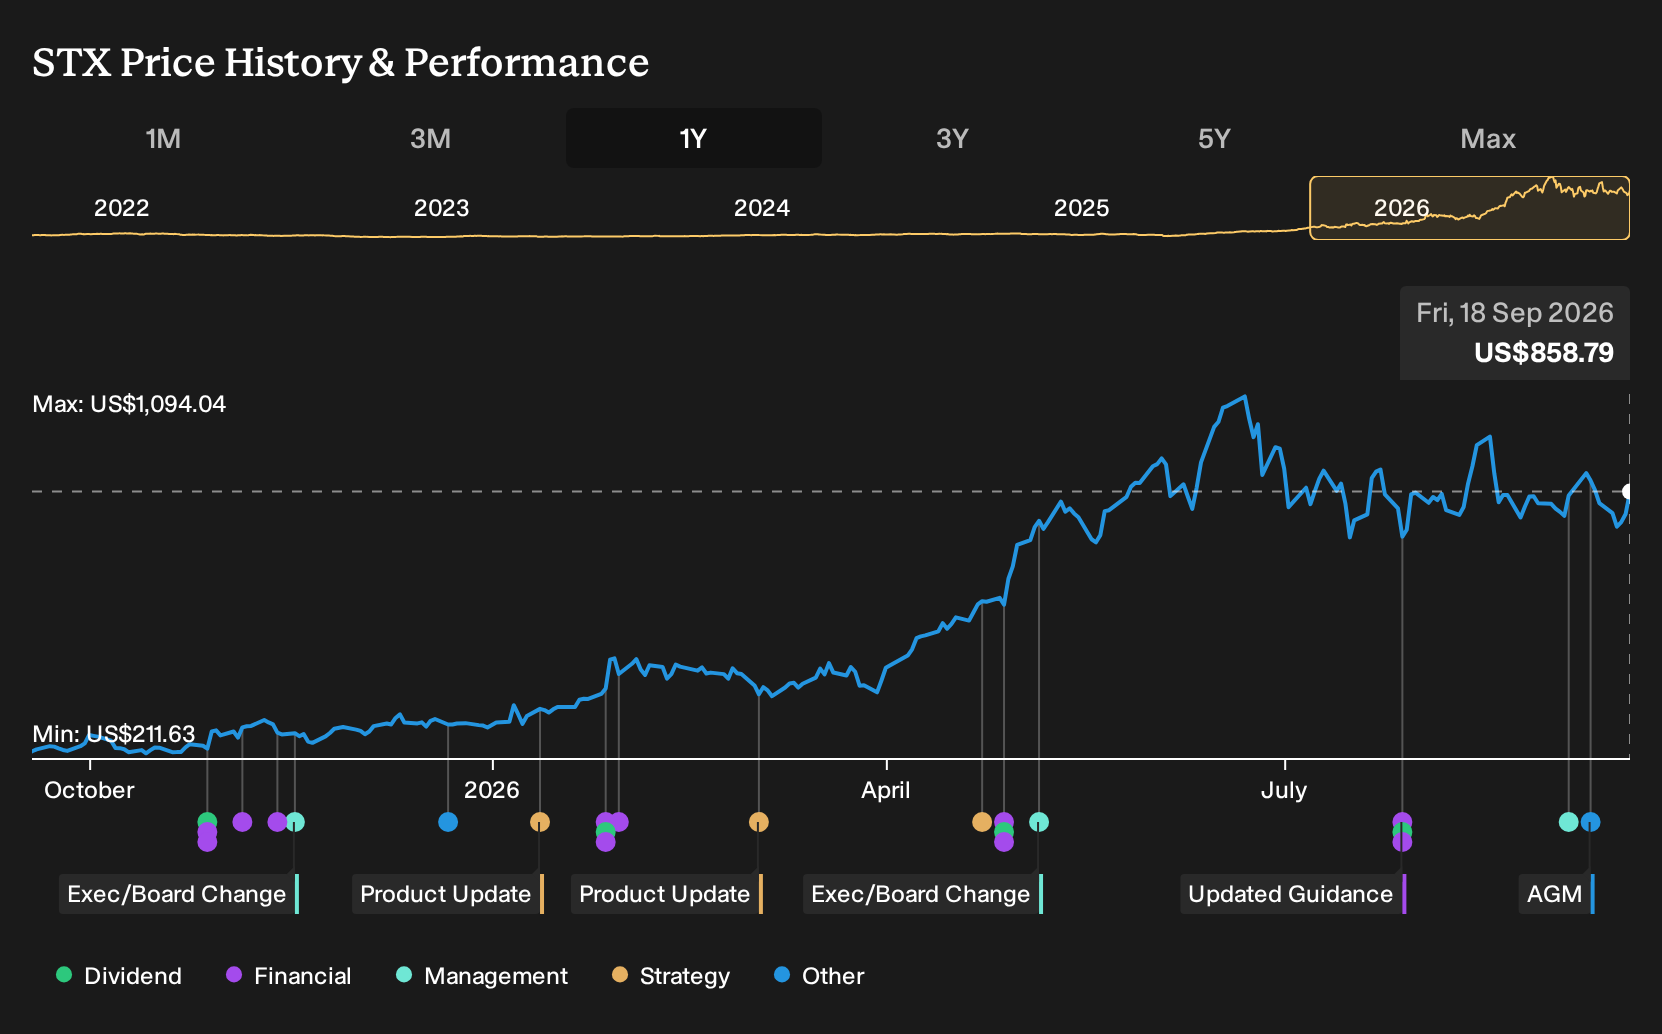
Exploring Other Perspectives
One contrasting angle from the bullish analysts is the belief that Seagate Technology Holdings could lean on accelerated AI data growth as a major upside catalyst. Before this margin news, some were already pencilling in revenue of about $35.8b and earnings of $18.4b by 2029. That is far more optimistic than the $30.5b and $16.3b consensus view. These projections were set before the latest pricing update, so you may want to compare both narratives and decide which assumptions feel closer to how you think the story could evolve.
Explore 4 other Seagate Technology Holdings fair value estimates, including one that suggests up to 80% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A useful starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easier to evaluate Seagate Technology Holdings' overall financial health at a glance.
Looking for more Seagate Technology Holdings style investment ideas?
If the pricing story around Seagate Technology Holdings has you thinking about portfolio upgrades, it can help to widen the lens and scan for other businesses with traits you value, whether that is resilience, income, or mispriced quality.
- For investors who want potential mispricing combined with quality fundamentals, review our 33 high quality undervalued stocks that may align with a similar margin and pricing focus.
- If capital preservation and steadier profiles appeal more than aggressive growth, consider starting with a 30 resilient stocks with low risk scores that could complement a position in a more cyclical hardware supplier.
- When you are hunting for future compounders before they appear on everyone’s radar, scan through a 16 high quality undiscovered gems that may share some of the structural advantages you see in Seagate Technology Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com