


Recent attention on Select Water Solutions (WTTR) stems from its growing backlog of long term, acreage dedicated water infrastructure contracts in the Northern Delaware Basin, which reflects expectations for improved visibility on future revenue and cash flow.
For context, Select Water Solutions now trades at US$20.78, with a 90 day share price return of 17.40% and an 87.38% year to date share price gain. The 1 year total shareholder return of 112.32% signals strong momentum, backed by a 3 year total shareholder return of 178.77% and a 5 year total shareholder return of 328.61% that many investors are weighing against perceived execution and efficiency risks.
Compare Select Water Solutions' contract driven momentum with other water and energy infrastructure players by scanning our hand picked 38 power grid technology and infrastructure stocks for your next research candidates.
For Select Water Solutions, this surge can look like a clean read on its contract driven business or like sentiment stretching ahead of fundamentals. The valuation work starts with separating those two stories.
Most Popular Narrative: 13% Undervalued
On the most followed view, Select Water Solutions screens below an estimated fair value of $24, compared with the recent $20.78 close, which puts contract visibility and capital spending plans under the microscope.
The company has secured a substantial and growing backlog of long term, acreage dedicated water infrastructure contracts in the Northern Delaware Basin, providing high predictability on revenue and cash flows over multiple years, with further upside as undedicated and ROFR acreage is converted. This positions Select to pursue Water Infrastructure revenue above a $400 million annual exit run rate in 2026, which may support sustainable top line growth and improved earnings visibility.
See why 13 investors see Select Water Solutions as 13% undervalued.
Result: Fair Value of $24 (UNDERVALUED)
Still, the story for Select Water Solutions could change quickly if large E&P customers scale back activity or if heavy capital spending fails to translate into solid returns.
Find out about the key risks to this Select Water Solutions narrative.
Another View on Select Water Solutions Valuation
The analyst fair value narrative frames Select Water Solutions as 13% undervalued at $24, but the earnings multiple tells a tougher story. WTTR trades on a P/E of 83.8x, compared with a fair ratio of 27.5x, the US Energy Services average of 24.6x and a 61x peer average. That gap points to valuation risk if sentiment cools.
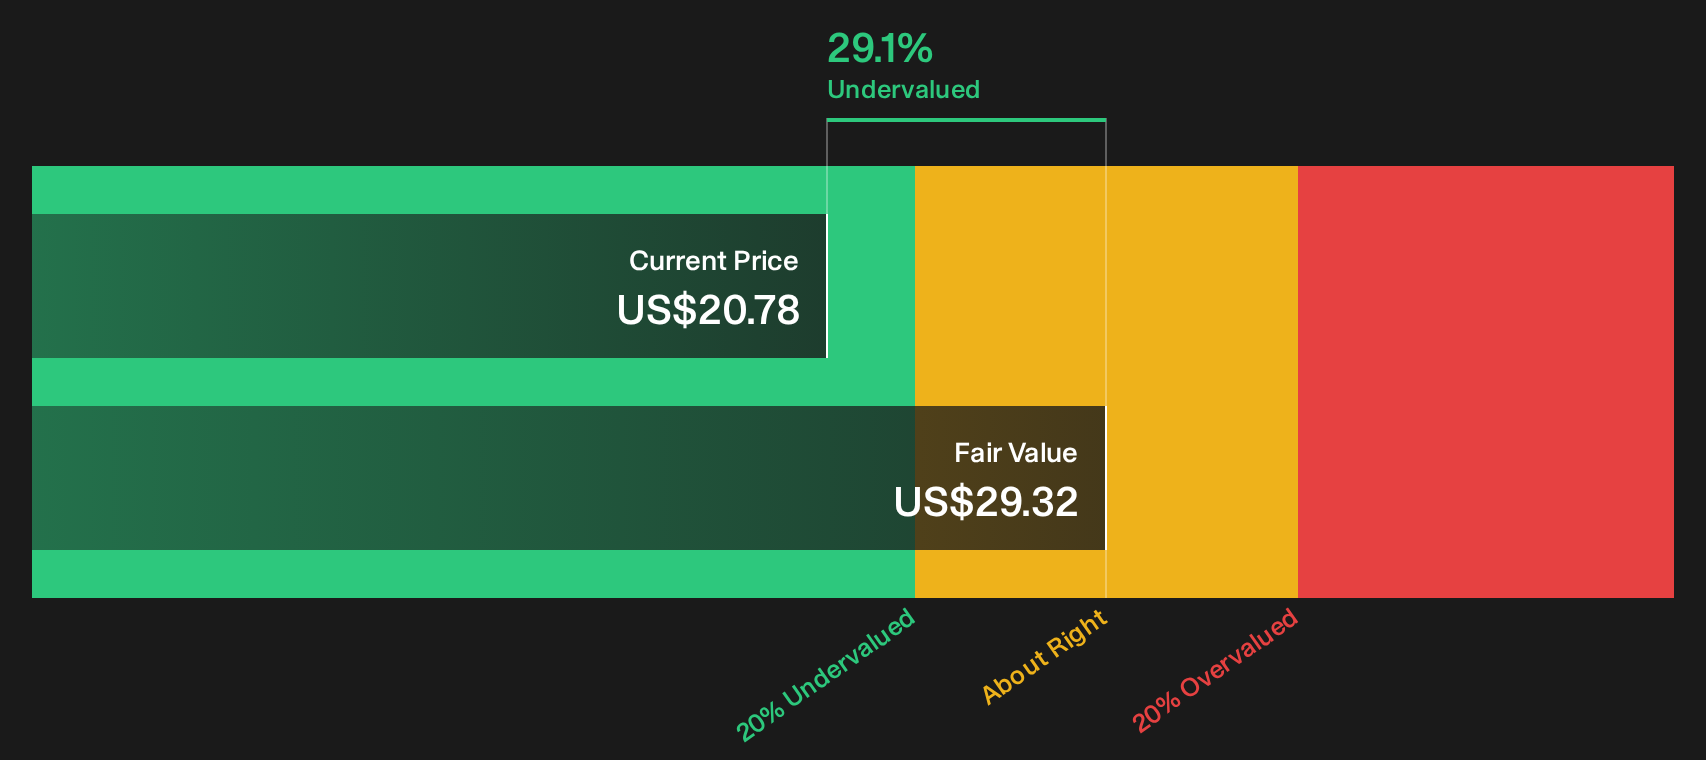
Our DCF model still indicates upside, with WTTR at $20.78 compared with an estimated future cash flow value of $29.32. This raises a practical question: do you lean more on cash flow math or on how much you are willing to pay for each dollar of earnings?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Select Water Solutions is clearly split between enthusiasm for contract visibility and concern about what the valuation implies for future execution. If you want to move fast and test the bullish and cautious angles against the underlying data, start with the 2 key rewards and 1 important warning sign.
Want more ideas beyond Select Water Solutions?
If you like the contract driven story at Select Water Solutions but do not want all your bets in one place, broaden your hunting ground using targeted screeners that surface very different types of opportunities.
- Target potential mispricing by reviewing a curated set of companies that screen as strong value candidates through the 33 high quality undervalued stocks.
- Prioritize resilience by scanning for businesses with robust finances and clean balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Hunt for early stage opportunities by tracking a focused group of market minnows with stronger fundamentals through the 8 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com