


- Tsakos Energy Navigation reported second quarter 2026 net income of US$139.3 million and basic earnings per share of US$4.40, compared with US$26.83 million and US$0.67 a year earlier.
- Over the first half of 2026, Tsakos Energy Navigation recorded net income of US$228.14 million and basic EPS of US$7.12, which highlights how current freight conditions and fleet deployment choices are feeding directly into profitability.
- Investors may now reassess how Tsakos Energy Navigation's sharp jump in quarterly earnings per share could influence the existing investment narrative.
Tsakos Energy Navigation Investment Narrative Recap
To own Tsakos Energy Navigation, you need to be comfortable with a tanker operator that is tightly linked to oil flows, freight cycles and the pace of fleet renewal. The recent jump in quarterly net income and EPS confirms that current freight conditions and contract mix are feeding straight into profits. The key short term swing factor remains how long these favorable shipping conditions last and how effectively management keeps utilization near current levels.
The biggest immediate risk still sits on the balance sheet and cash flow side. Heavy investment in modern, eco focused vessels and high net debt leave Tsakos Energy Navigation exposed if freight rates soften or spot opportunities dry up. The latest earnings strength helps, but it does not remove the concern that weaker operating cash generation could pressure refinancing costs and limit flexibility.
The most relevant announcement is the second quarter and first half 2026 earnings release itself. Net income of US$139.3 million for the quarter and US$228.14 million for the half, with basic EPS of US$4.40 and US$7.12 respectively, shows how tight supply and Tsakos Energy Navigation's contract choices feed into the income statement. It gives you fresh data to judge how sustainable current profit levels look against sector cycles.
For catalysts, this set of results plugs directly into the existing narrative around modern tonnage, time charter coverage and profit sharing contracts. Strong recent earnings partly offset concerns about debt not being well covered by operating cash flow, but they also sharpen the question of how results might look if freight conditions cool while capex and interest costs stay heavy. Your call now is how this earnings print fits with your view on tanker demand and Tsakos Energy Navigation's ability to keep renewing its fleet without stretching the balance sheet.
Tsakos Energy Navigation's current analyst narrative points to revenues of US$679.5 million and earnings of US$73.0 million by 2029, based on a forecast yearly revenue decline of 5.2% and a move from earnings today of US$132.3 million to that 2029 consensus level, which implies an earnings decrease of about US$59 million.
Uncover why Tsakos Energy Navigation's fair value indicates a 12% potential downside to its current price, suggesting that this premium may not hold.
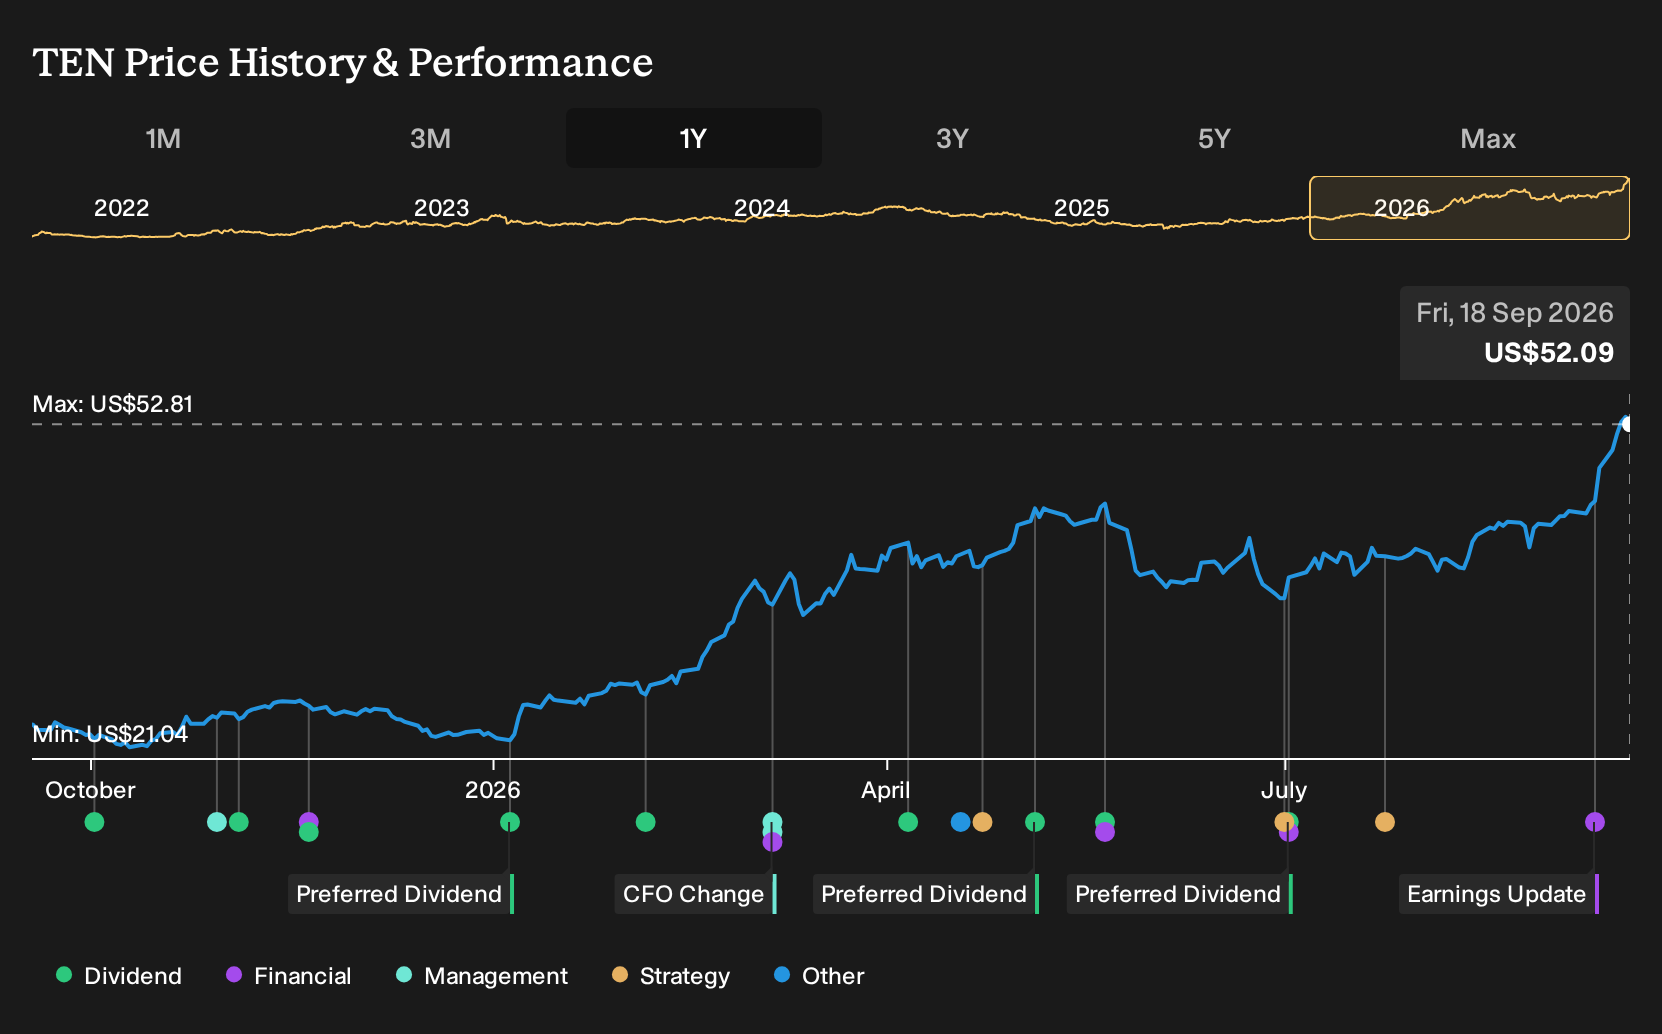
Exploring Other Perspectives
One alternate view zooms in on long term decarbonization risk. The most pessimistic analysts were modeling Tsakos Energy Navigation’s revenue shrinking about 15% a year and earnings sliding from roughly US$183.2 million to just US$10.1 million by 2029. That is a very different story. Treat this earnings release as a fresh prompt to compare those scenarios yourself.
Explore 3 other Tsakos Energy Navigation fair value estimates, including one that suggests as much as 72% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Tsakos Energy Navigation research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tsakos Energy Navigation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tsakos Energy Navigation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tsakos Energy Navigation?
If this Tsakos Energy Navigation update has sharpened your thinking, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener. It is a quick way to line up potential candidates that match the income profile, balance sheet strength or valuation style you want to focus on next.
- For investors who want robust businesses with headroom on the balance sheet, start by reviewing a curated list of solid balance sheet and fundamentals (23 results) that already screens for financial resilience.
- If capital preservation and smoother returns matter more than headline growth, consider scanning a focused 30 resilient stocks with low risk scores that tilts toward companies with fewer red flags and steadier fundamentals.
- When the goal is to uncover less crowded stories with strong fundamentals, broaden your watchlist with a hand picked 16 high quality undiscovered gems that might complement or contrast with a position in Tsakos Energy Navigation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com