


- Qiagen has introduced QIAsymphony Connect, an automated clinical nucleic acid extraction platform with regulatory clearances in the US and Europe, alongside second quarter results that exceeded its own guidance, with Sample technologies and QIAcuity highlighted as key growth drivers.
- The combination of a new automation platform aimed at liquid biopsy, oncology, and infectious disease labs and a cautious full year outlook with 1 to 2% constant currency sales growth guidance puts Qiagen’s balance between investment in new systems and measured demand expectations in sharp focus for investors.
- We will examine how Qiagen’s investment narrative is influenced by QIAsymphony Connect’s launch as management keeps full year growth expectations unchanged.
Scan how Qiagen’s cautious outlook compares with peers facing similar demand questions by reviewing the hand picked 30 resilient stocks with low risk scores in the same defensive quality camp.
Qiagen Investment Narrative Recap
To own Qiagen, you need to believe this is a diagnostics and tools platform that can keep shifting more of its mix toward consumables, automation and software, even while end markets like research funding and China stay uneven. The reaffirmed 1% to 2% constant currency sales outlook signals that management sees demand as steady rather than accelerating, so the near term story hinges on execution rather than a macro tailwind.
The key near term catalyst is adoption of newer systems such as QIAstat Dx, QIAcuity and now QIAsymphony Connect, which can support recurring kit usage if placements hold up. The biggest risk remains softer high ticket instrument orders or delayed lab budgets, which would matter more than the recent guidance update. The latest news does not materially change that balance.
The leadership transition around Thierry Bernard stepping down from the Managing Board and the planned vote on new CEO Jonathan Pratt is the headline development that ties all this together. Investors are essentially judging whether the existing playbook in automation, molecular diagnostics and bioinformatics continues with the same discipline on costs and product focus.
Board and management teams at Qiagen already have relatively long tenure, which can help continuity as Pratt takes over operationally. For catalysts like QIAsymphony Connect and QIAstat Dx to matter, execution on pricing, service and menu expansion has to stay tight. The risk is any disruption to that rhythm during the handover, especially while competition in digital PCR and syndromic testing remains intense.
Qiagen's analyst narrative points to revenues of US$2.6b and earnings of US$606.0m by 2029, based on an assumed 6.9% yearly revenue growth rate and an earnings increase of about US$196.7m from current earnings of US$409.3m.
Uncover why Qiagen's fair value indicates a 5% potential upside to its current price that could narrow quickly.
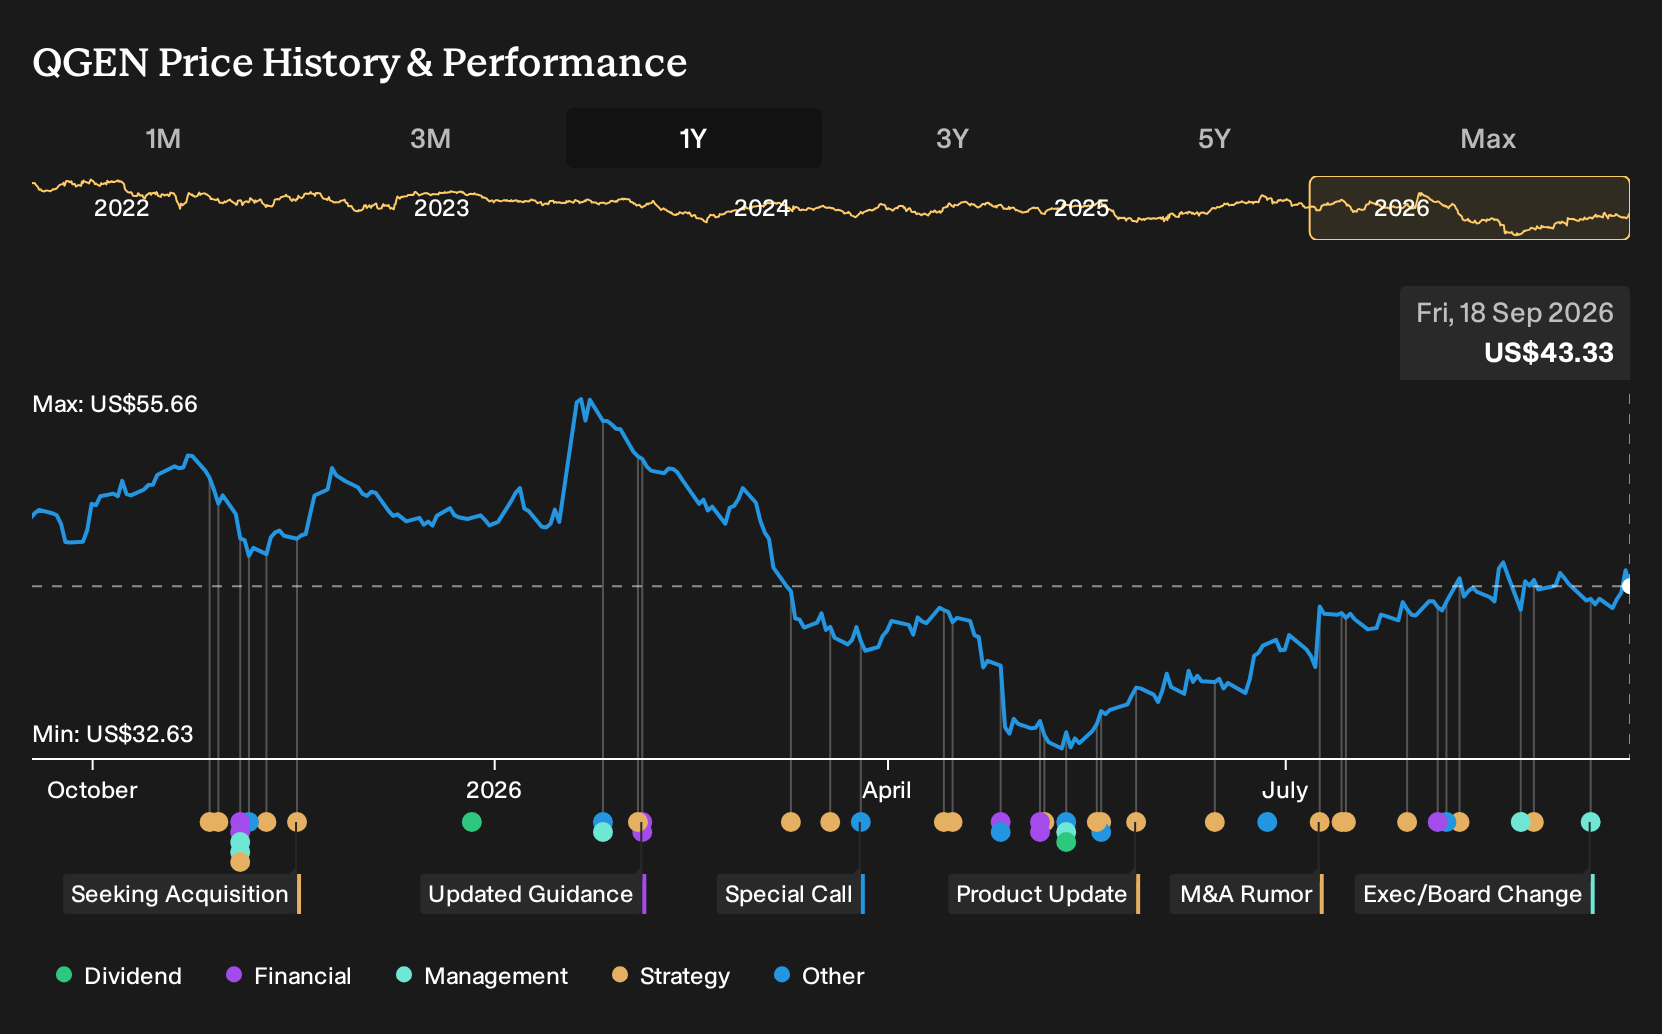
Exploring Other Perspectives
One alternative narrative focuses on QuantiFERON as the weak link for Qiagen rather than automation. The most cautious analysts were already working with about US$2.4b of 2029 revenue and US$581.1m of earnings before this CEO change and QIAsymphony Connect launch. That group sees greater policy and immigration risk, so you can compare multiple viewpoints and decide which feels more realistic for you.
Explore 4 other Qiagen fair value estimates, including one that suggests there may be as much as 7% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen's overall financial health at a glance.
Looking for more Qiagen sized investment ideas?
If this Qiagen story has sharpened your thinking about risk, returns and product cycles, it can help to line it up against other businesses that fit different profiles on value, income and balance sheet strength.
- For investors hunting for mispriced quality, scan the 33 high quality undervalued stocks that pair solid fundamentals with what may be more modest expectations baked into prices.
- If dependable income is your priority, review the 6 dividend fortresses that focus on higher yields supported by underlying cash generation.
- For a focus on resilience first, filter the market using the list of solid balance sheet and fundamentals (23 results) to see which companies carry less financial strain on their books.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com