


- Albemarle is preparing to report earnings and revenue that analysts expect to be significantly higher than a year ago, while the firm continues to push lithium conversion capacity projects and operational efficiencies in a period of choppy lithium pricing.
- The downward revision of Albemarle’s fair value estimate, tied to lithium market volatility and regulatory risk, highlights how cost discipline, long term contracts and productivity gains are being weighed against a more cautious sector backdrop.
- We will look at how Albemarle's investment narrative is shaped by lithium pricing pressure that has fed into revised fair value assumptions.
Albemarle Investment Narrative Recap
To own Albemarle, you need to believe its lithium resource base and conversion projects can translate into resilient cash generation even when pricing is choppy. The near term swing factor is execution on cost savings and productivity, because that is what can support earnings when spot markets stay weak. The recent share pullback and fair value cut mainly reflect sentiment around pricing rather than a sudden change in Albemarle's operating plan.
The biggest risk right now is that low lithium prices and industry oversupply drag on longer than expected, which could keep margins and returns under pressure even as capacity ramps. EV demand uncertainty and regulatory shifts sit in the background as secondary threats. The latest earnings expectations, while higher than last year, do not materially change that risk reward balance on their own.
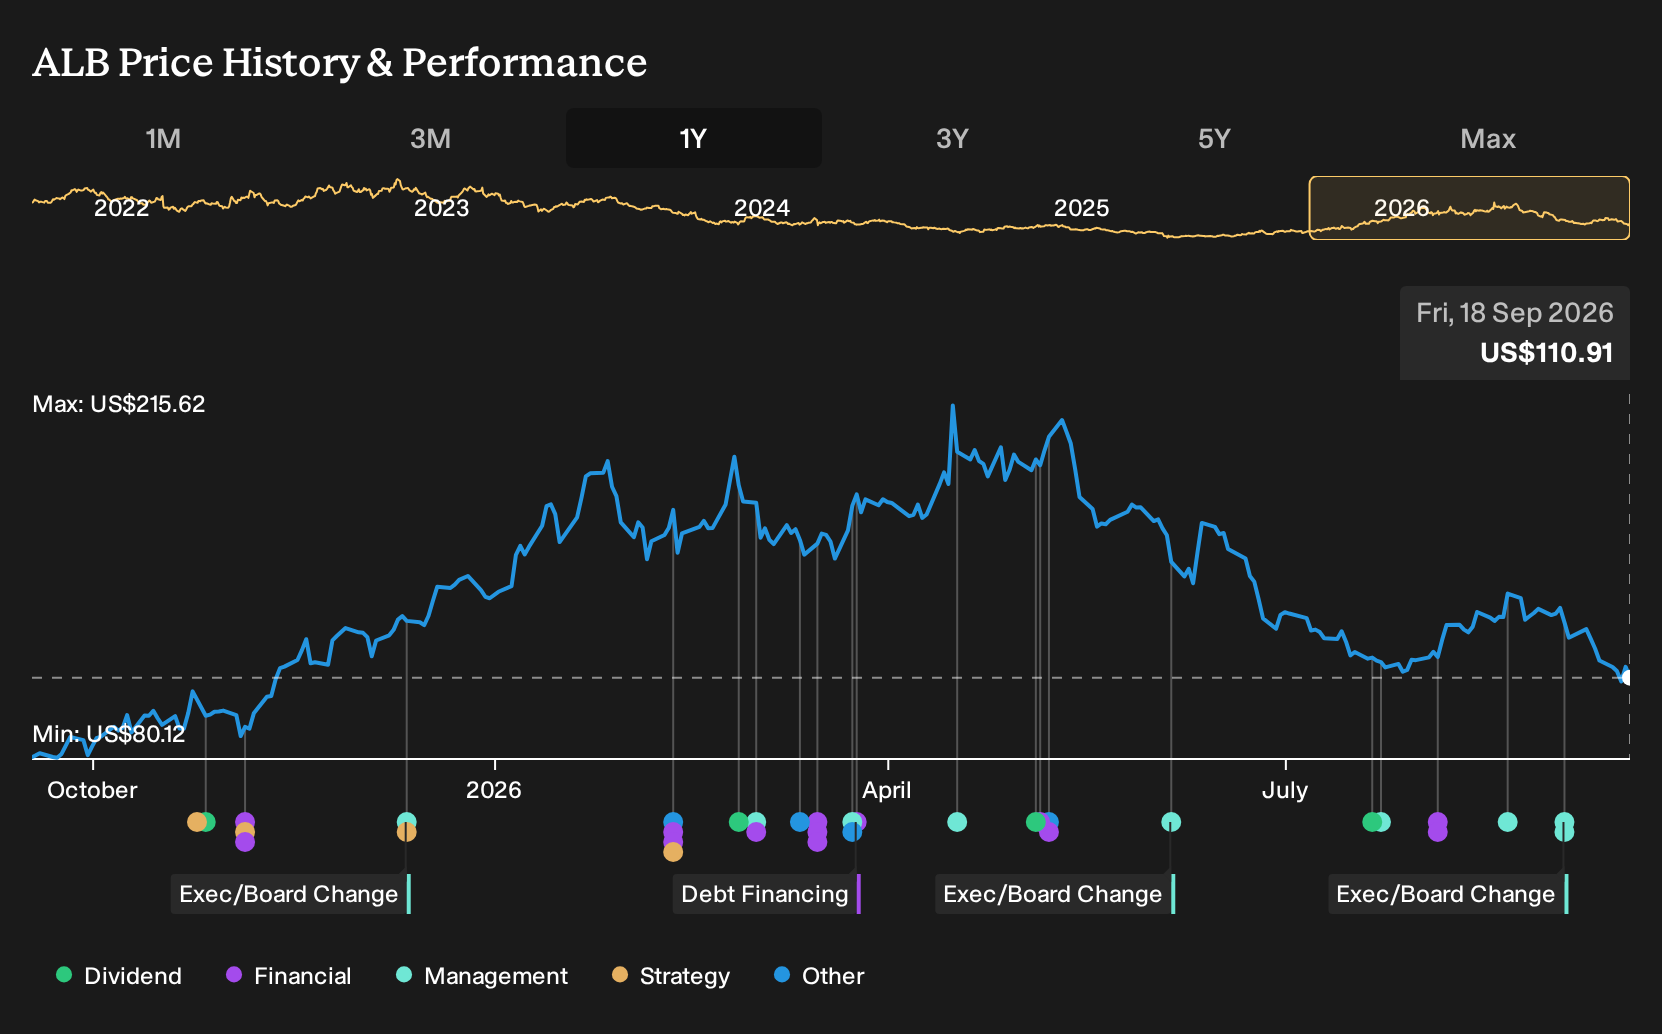
The most relevant piece of recent news for you is that Albemarle is expected to post much stronger earnings and revenue than a year ago, even after a 3.6% share price drop in the latest session. That combination indicates the story is less about what the company is reporting today and more about what investors think future lithium pricing and utilization will look like.
If Albemarle can pair those expected earnings gains with continued cost cuts, disciplined capital spending and progress on long term contracts, that supports the key catalyst, which is the market gaining more confidence in its ability to earn through the cycle. The Zacks Rank of #3 (Hold) and a forward P/E below the industry average sit around the edges of the story. The core question for you is whether execution on projects and efficiencies can offset the lithium price and regulatory risks that drove the fair value revision lower.
Albemarle Earnings and Revenue Assumptions
Albemarle's narrative projects US$6.9b revenue and US$2.5b earnings by 2029. That profile is built on analysts using a 5.2% yearly revenue growth rate and an earnings increase of roughly US$2.4b from current earnings of US$57.4m to the forecast consensus level.
Uncover why Albemarle's fair value indicates a 56% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Albemarle’s volume potential rather than lithium prices. The most optimistic analysts were modeling revenue of about US$8.3b and earnings of US$2.9b by 2029, above the consensus US$6.9b and US$2.5b. Those projections came before the latest earnings setup, so opinions may change over time.
Explore 3 other Albemarle fair value estimates, including one that suggests potential upside of as much as 135% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Albemarle research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Albemarle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albemarle's overall financial health at a glance.
Looking for more Albemarle sized investment ideas?
Once you have a view on Albemarle, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. That way you are comparing this stock with a wider field of businesses that match the kind of risk, balance sheet strength or income profile you are actually looking for.
- If capital preservation is your priority, start with a 30 resilient stocks with low risk scores that aims to keep drawdowns in check while still offering equity upside.
- For investors focused on value and fundamentals, review a curated 33 high quality undervalued stocks that couples compressed valuations with healthy cash generation.
- If income matters most, scan a 6 dividend fortresses built around higher yielding payouts that aim to be supported by underlying business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com