


Howmet Aerospace (HWM) raised its 2026 revenue and adjusted EBITDA guidance after stronger defense aerospace activity, including higher defense revenues in 2025 and 2026 and new work tied to drones and collaborative combat aircraft programs.
That raised guidance comes after a choppy few months for Howmet Aerospace, with the share price down about 19% over the past 30 days and 17% over the last quarter, even as the stock shows an 8.5% year to date share price return and a 1 year total shareholder return of about 21%, alongside a very large 3 year and 5 year total shareholder return that signals long-running momentum. Recent demand strength in defense, including drone and collaborative combat aircraft work, helps explain why some investors may now view the latest pullback from the US$229.67 share price as a reassessment of risk rather than a change in the underlying story.
Compare Howmet Aerospace with other defense exposed manufacturers by scanning a curated group of 38 power grid technology and infrastructure stocks that could also benefit from long-cycle infrastructure and aerospace spending themes.
The sharp pullback in Howmet Aerospace after years of strong compounded returns now puts you at a fork. Do you treat this drop as an early entry or wait for the valuation to reset further before stepping in?
Most Popular Narrative: 39% Undervalued
On the most followed narrative, Howmet Aerospace screens as undervalued, with a fair value of $375 against the recent $229.67 close. This view places significant emphasis on long term engine and turbine demand.
The backlog of new commercial aircraft orders is at record highs globally, especially for Airbus, Boeing, and COMAC, fueled by rising demand for air travel in fast-growing middle-class populations and by urbanization trends in major regions. As aircraft underbuild reverses, suppliers like Howmet are poised for multi-year revenue growth as OEM production ramps up to meet this sustained demand.
Find out how 5 investors see Howmet Aerospace as 39% undervalued.
Result: Fair Value of $375 (UNDERVALUED)
Still, the bullish Howmet Aerospace narrative leans on key assumptions around Boeing and Airbus production and on margin forecasts that could prove too optimistic if regulations, competition or technology shifts bite harder than expected.
Find out about the key risks to this Howmet Aerospace narrative.
Another View: Howmet Aerospace Looks Expensive On P/E
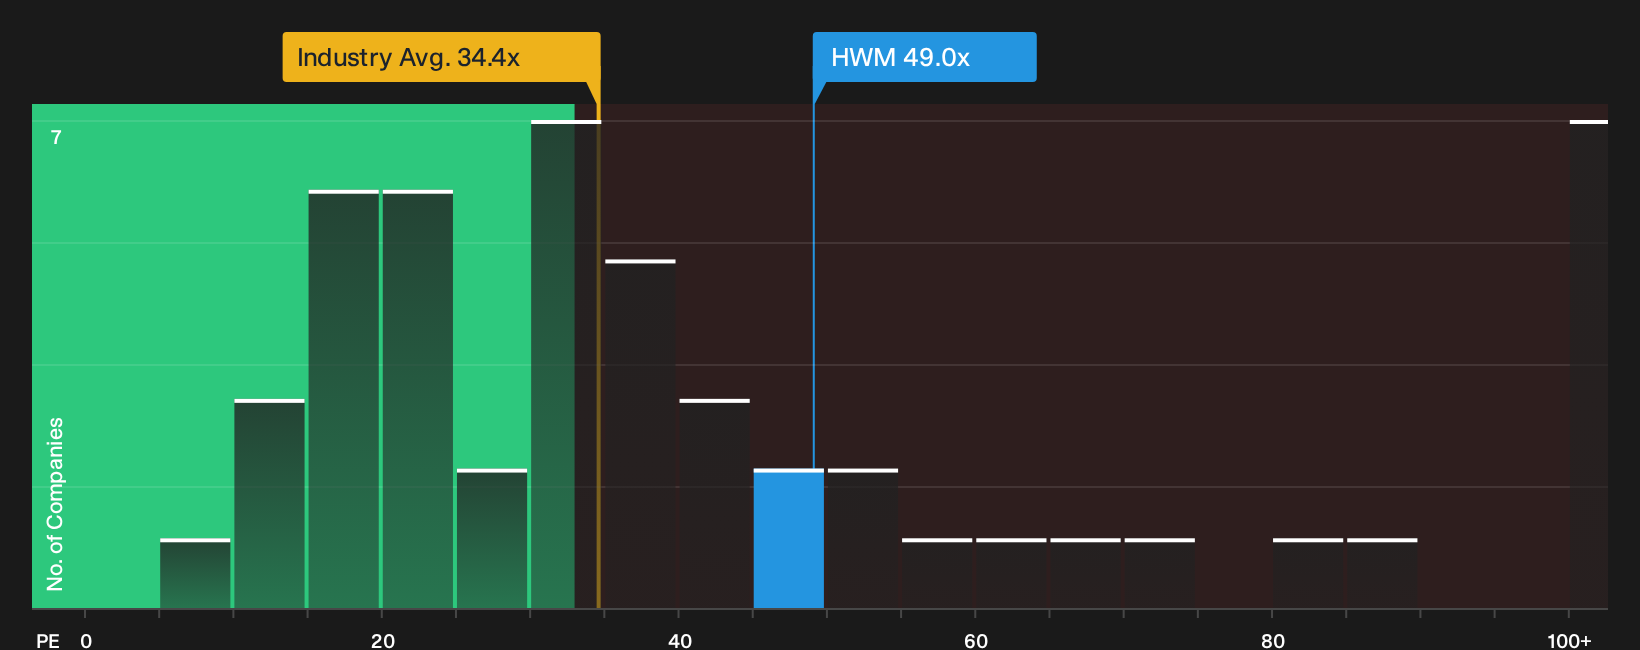
There is a different read on Howmet Aerospace when the focus shifts from bullish narratives to simple P/E math. The stock trades on about 49x earnings, compared with 34.4x for the US Aerospace & Defense industry and 22.2x for its peer group, while the fair ratio is estimated at 33.5x.
That spread implies investors today are paying a much richer price than both peers and the fair ratio suggest, which raises a straightforward question for you. Is the current premium multiple a risk worth accepting if growth or margins end up closer to average than the most optimistic scenarios?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Howmet Aerospace can be confusing, so move quickly to check the data for yourself and weigh both the upside and the downside in one place with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Howmet Aerospace?
If Howmet Aerospace has sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist now so you are not reacting after the next move.
- Target potential upside in quality businesses that trade below their estimated worth by scanning our curated set of 33 high quality undervalued stocks.
- Strengthen your focus on financial resilience by checking companies with sturdy finances in the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known opportunities with robust fundamentals through a hand picked pool of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com