


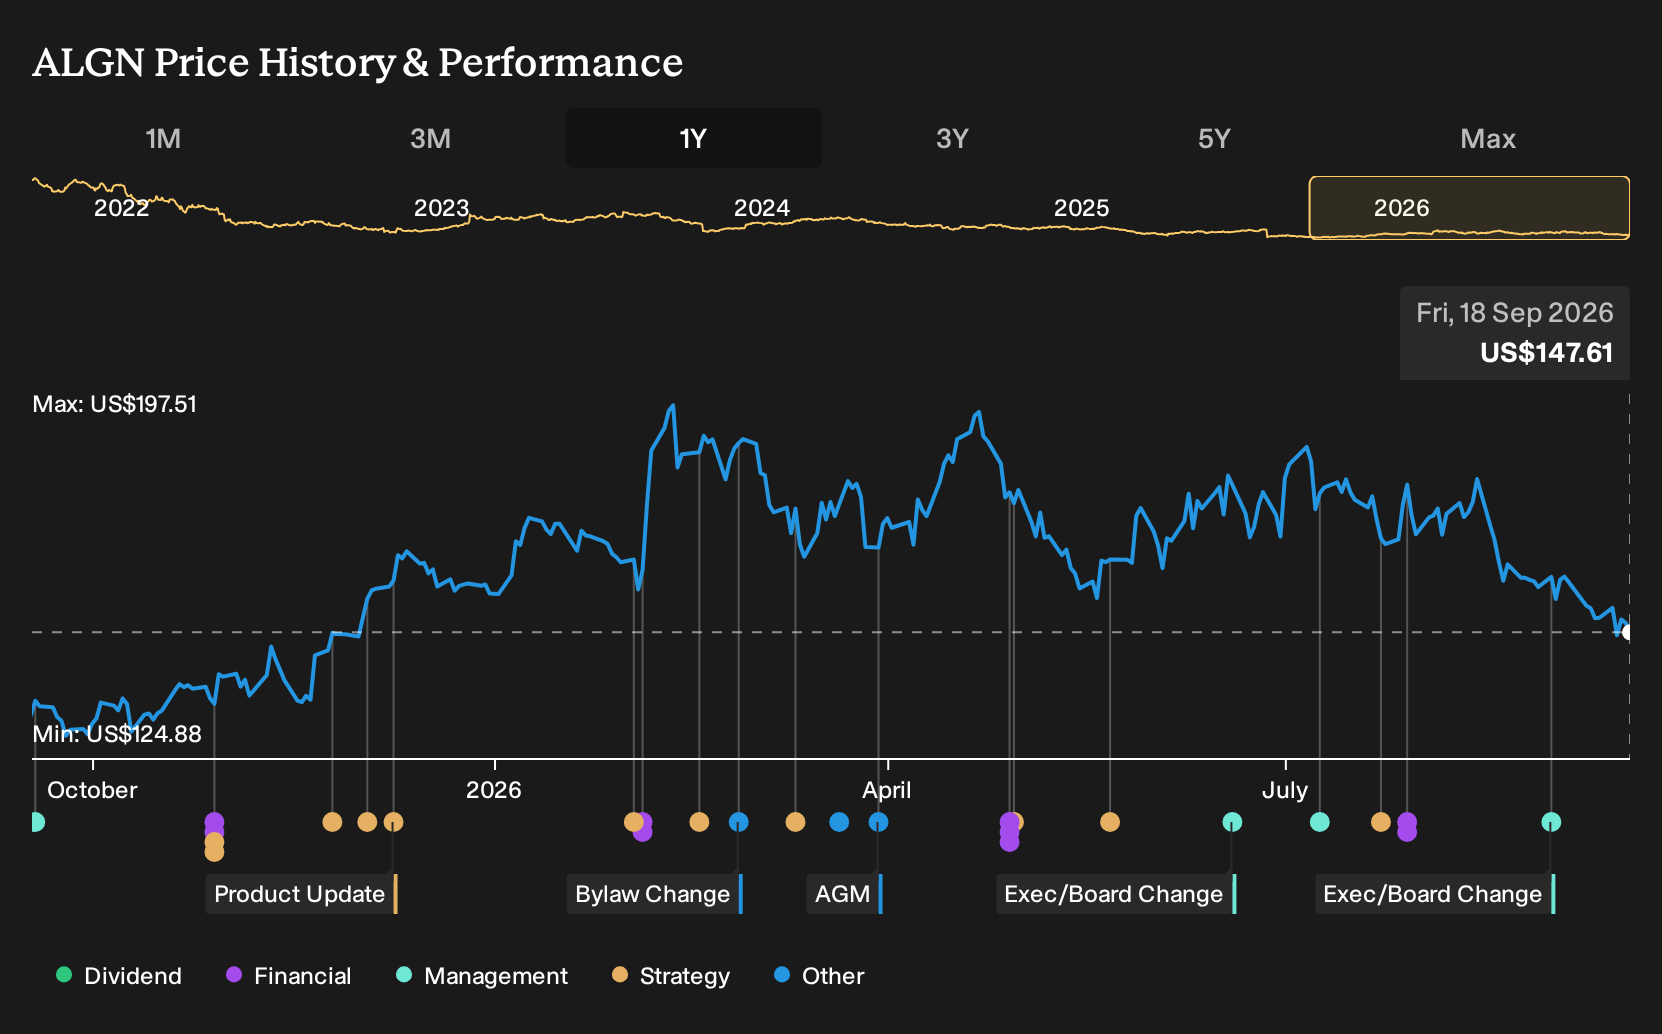
- Align Technology recently presented at the 2026 Global Healthcare Conference in New York, with CFO John F. Morici and IR lead Madelyn Valente outlining the company’s position after reporting quarterly earnings that exceeded expectations but came with lowered Q3 revenue guidance.
- The combination of better reported results and a more cautious revenue outlook highlights how inflation and postponed elective dental treatments remain a real drag on near term demand for Align’s clear aligners and scanners.
- Next, the focus shifts to how Align Technology’s cautious revenue guidance and softer elective dental demand could reshape the existing investment narrative.
Balance short term caution around Align Technology with a broader view on oral care by scanning a curated list of solid balance sheet and fundamentals (23 results) that might better handle the same elective demand pressures.
Align Technology Investment Narrative Recap
To own Align Technology, you need to be comfortable with a story that leans on clear aligners, iTero scanners, and a broad digital dentistry platform while accepting choppy demand for elective procedures. The lowered Q3 revenue guidance reinforces that, in the near term, the main upside trigger is a cleaner turn in patient traffic and case starts, which has yet to fully materialize.
The biggest operational risk right now is that inflation-sensitive patients keep delaying treatment, keeping orthodontic volume soft and scanner purchases subdued. The recent conference appearance does not change that core tension. It mainly underlines that management still sees macro and mix headwinds as real constraints on near-term execution.
The 2026 Global Healthcare Conference appearance matters because it puts Align Technology’s operating message in front of institutional investors shortly after guidance came down. Management has a chance to walk through how Invisalign, iTero, and software fit together, and how cost controls, automation, and regional production might protect profitability if demand stays uneven.
For a shareholder, this kind of event is useful as a check on risk and catalyst timing. You get more color on how the firm is thinking about weaker orthodontic case starts, lower-priced products, and competition, and how those pressures line up against potential demand recovery, new clinical indications, and continued adoption by general dentists.
Align Technology's analyst narrative points to forecast revenues of US$4.7b and earnings of US$721.2m by 2029, built on revenue growth assumptions of 4.9% per year and an earnings increase of about US$291.3m from current earnings of US$429.9m.
Uncover why Align Technology's fair value points to a 42% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate view on Align Technology focuses heavily on competition risk. Before this conference, the most cautious analysts were modeling revenue of about US$4.6b and earnings of roughly US$696.1m by 2029, and pairing that with a lower assumed P/E of 20.7x. That is a distinctly more pessimistic story. Treat this presentation as a fresh data point and compare several narratives before you decide what makes sense for you.
Explore 5 other Align Technology fair value estimates, including one that suggests it could be worth just $154.62.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis.
- A great starting point for your Align Technology research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Align Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Align Technology's overall financial health at a glance.
Looking For More Ideas Beyond Align Technology?
If Align Technology is only one piece of your watchlist, it can help to contrast it with other businesses that have different balance sheet strength, risk profiles, and income characteristics. The Simply Wall St Screener is a useful way to quickly surface stocks that fit the kind of portfolio you want to build.
- For investors who care most about resilience, you could scan a 30 resilient stocks with low risk scores that may hold up better when conditions turn choppy.
- If value is your priority, compare Align Technology against a 33 high quality undervalued stocks that filters for companies with solid fundamentals trading at what may be attractive prices.
- For those looking to add income alongside growth stories like Align Technology, consider a 6 dividend fortresses to spot higher yielding opportunities that still pass basic quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com