


Opendoor Technologies has seen its share price fall sharply in recent years, which puts a spotlight on whether the current US$2.56 level really lines up with the sales it is generating. For anyone looking at the stock today, the core issue is how that revenue base stacks up against a market value that has already absorbed a long stretch of declines.
- Over the past 5 years, Opendoor Technologies has delivered a share price decline of 87.4%, which raises clear questions about what the market now assumes about the value of its underlying sales.
- The business model leans heavily on turning over housing inventory and managing tight margins, so the way those sales convert into sustainable revenue and potential cash flow can heavily influence what investors are willing to pay for each dollar of top line.
- Your read on Opendoor Technologies is one view; the desks covering it have another. See what analysts think Opendoor Technologies's shares could be worth.
The issue now is whether Opendoor Technologies' current share price can be justified by the sales the company is producing today and is expected to generate over time.
If you are weighing whether Opendoor Technologies' US$2.56 share price lines up with its sales, it can help to compare that question across 33 high quality undervalued stocks
Is Opendoor Technologies Getting Expensive on Sales?
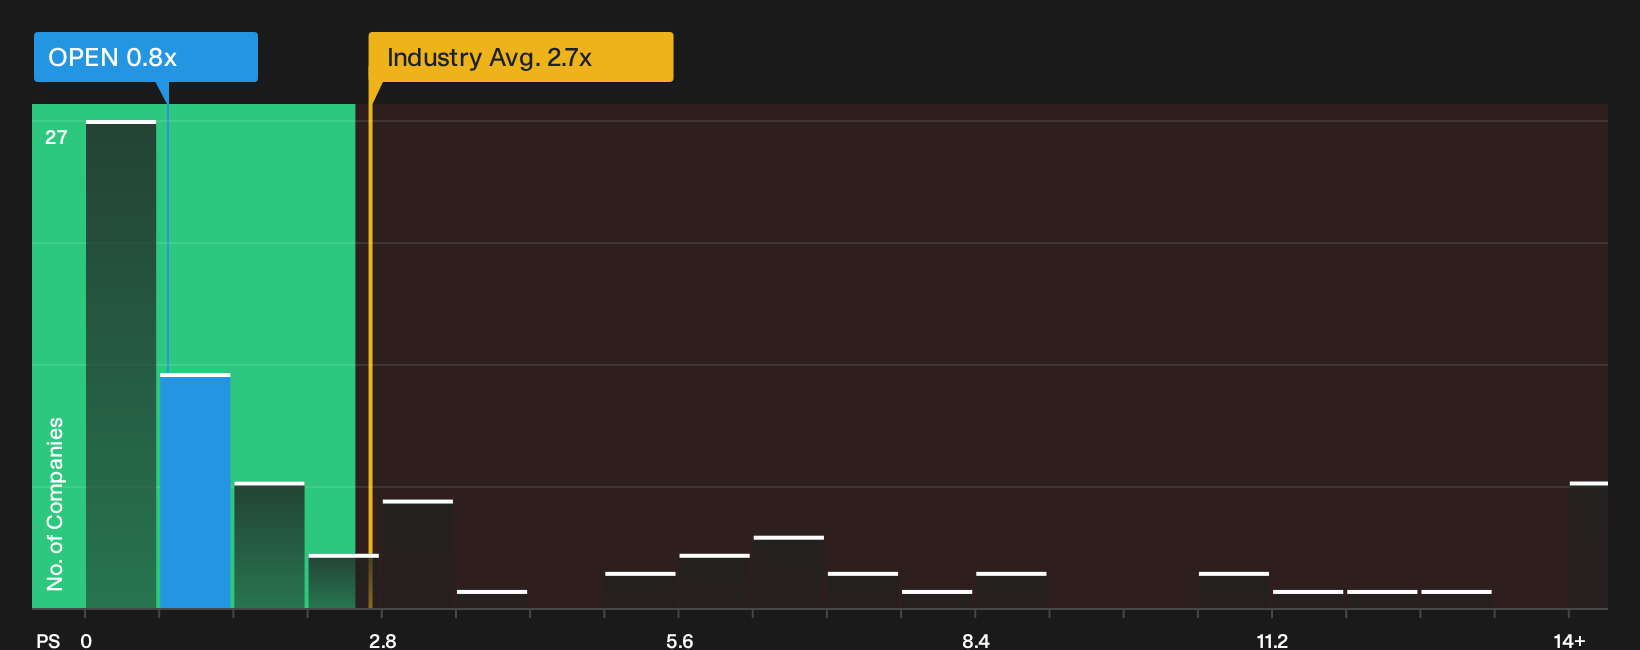
P/S works reasonably well for Opendoor Technologies because the business turns over high ticket housing inventory, so revenue gives a clearer yardstick than earnings that swing with the property cycle and financing costs. On this measure, the stock trades on a P/S of 0.8x, compared with a Real Estate industry average of about 2.7x and a peer group closer to 1.2x. That means investors today are paying less per dollar of Opendoor Technologies' sales than both the wider sector and the more focused peer set.
The internal fair multiple estimate suggests a higher P/S would usually be expected for Opendoor Technologies once its growth profile, margins, size and risk markers are blended together. As a result, the current 0.8x sits below that model benchmark. For anyone weighing the shares, the key question is whether the revenue quality and business risks justify this discount, or whether the market is pricing in too much caution relative to the sales base already in place. Explore the numbers behind Opendoor Technologies's P/S valuation.
The Opendoor Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Opendoor Technologies valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the shares to be worth materially more or less than today. Each one treats Opendoor Technologies' fair value as a specific thesis about the business that you can watch play out over time, and they sit on Simply Wall St's Community page for you to track and challenge.
Community views on Opendoor Technologies split sharply between those who see a recovery set up and those who think expectations have already run too far.
Bull case: 46% undervalued
"Expanding product offerings such as List with Opendoor and the Marketplace, alongside better targeting sellers outside of their buy box, could unlock new revenue streams..."
Discover why this Narrative puts Opendoor Technologies at 46% undervalued.
Bear case: 156% overvalued
"Rising global interest rates and persistently tight credit markets are making mortgages less affordable and actively depressing home buyer demand, which is expected to drive down Opendoor's transaction volumes..."
Explore why this Narrative puts Opendoor Technologies at 156% overvalued.
Opendoor Technologies' price is only one piece of the picture
Before leaning too heavily on the P/S story for Opendoor Technologies, it helps to know that Simply Wall St's broader checks have raised specific risk flags that deserve attention beside the valuation work already done. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com