


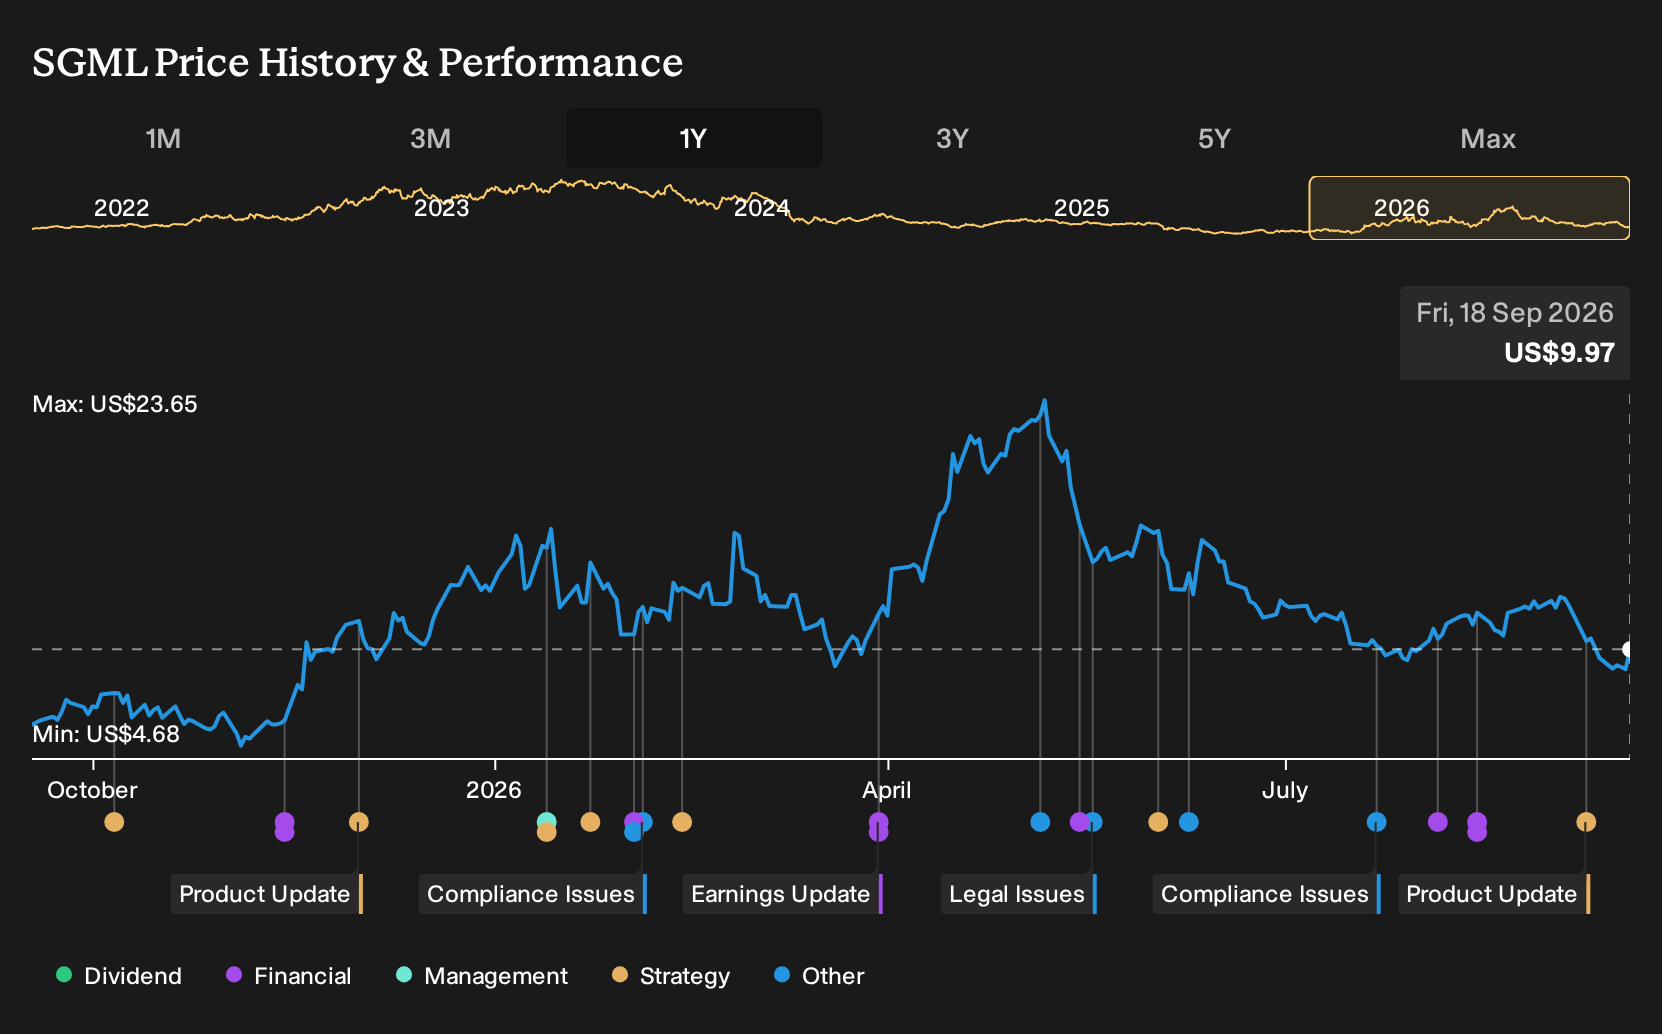
- Sigma Lithium reported that mining and industrial activities continue, while it contests a preliminary judicial ruling on environmental licenses that it believes is unwarranted and inconsistent with Brazilian due process.
- The producer reiterated its TAC Agreement with Minas Gerais authorities, its long operating history in Vale do Jequitinhonha, and its extensive ESG track record as it works to protect 19,000 jobs and its expansion plans.
- We will now look at how Sigma Lithium's investment narrative is shaped by this clarification that its Brazilian operations remain ongoing.
Sigma Lithium Investment Narrative Recap
To own Sigma Lithium, you need to believe the Brazilian operation can keep running while expansion plans move ahead within its legal and regulatory framework. The company says mining and industrial activities are ongoing and it expects to deliver 240,000 tonnes of lithium oxide concentrate within 12 months and 330,000 tonnes in fiscal 2027. That production path is a key near term catalyst.
The biggest operational risk right now sits around regulatory and legal friction in a single jurisdiction. Management is contesting a preliminary ruling on environmental licenses and insists due process has not been followed. Based on the company’s explanation, this headline looks more like a process overhang than a change to day to day operations.
The most relevant update is Sigma Lithium’s clarification that the preliminary judicial ruling does not stop its mining or processing activities. The business highlights that fines or other penalties in the ruling would only apply if a full legal process ended with an adverse final decision. It also points to prior agreements with Minas Gerais authorities through the TAC Agreement.
For you as a shareholder, the key question is whether this legal dispute disrupts production volumes that underpin expansion and cash generation over the next few years. The company’s message is that operations continue, expansion targets remain in place and no payments under the ruling are currently due. That keeps operational execution and lithium pricing as the primary swing factors for the story.
What The Current Sigma Lithium Forecasts Assume
Sigma Lithium's narrative projects US$600.1 million in revenue and US$57.4 million in earnings by 2028. That path assumes revenue growth of 64.6% per year and an earnings change of roughly US$105 million, from a loss of US$47.7 million today to the consensus earnings figure.
Discover why Sigma Lithium's fair value points to a 72% potential upside to its current price, an opportunity that could diminish quickly.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, Sigma Lithium sits in a wide band from US$4.96 to US$17.83. That is a big gap for the same stock. Those views do not yet reflect the recent licensing headlines or expansion plans, so treat them as starting points and explore multiple angles before deciding how this fits in your portfolio.
Explore 2 other Sigma Lithium fair value estimates, including one that suggests as much as 79% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sigma Lithium research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sigma Lithium. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sigma Lithium's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sigma Lithium?
If this Sigma Lithium update has you rethinking your exposure to materials, it can be useful to balance the picture with a few different types of opportunities pulled from the wider market using the Simply Wall St Screener.
- For investors prepared to take on higher risk in search of outsized gains, the 8 elite penny stocks with strong financials can highlight smaller companies with the financial profiles to warrant a closer look.
- If capital preservation and a smoother ride matter more to you right now, the 30 resilient stocks with low risk scores can surface businesses with more resilient risk scores to anchor your portfolio.
- When you want to aim beyond the usual large caps and find less crowded ideas, the 16 high quality undiscovered gems can point you toward under-followed companies with stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com