


Recent trading in West Japan Railway (TSE:9021) has drawn attention after the share price closed at ¥3,036 on 18 September 2026. Investors are weighing that level against mixed return figures across different time horizons.
For context, that latest share price sits after a 90 day share price return of 17.06%, even though the year to date share price return is down 2.10% and the 1 year total shareholder return has declined 7.06%. This suggests momentum has picked up more recently, while longer term holders have had a tougher run.
See how West Japan Railway's recent momentum compares with other companies showing resilient fundamentals in our hand-picked list of solid balance sheet and fundamentals (21 results)
West Japan Railway now trades only slightly below the average analyst price target after that sharp 90 day rebound. Is the remaining discount compensation for real risks, or is the caution starting to look overstated?
Price-to-Earnings of 11.7x: Is it justified?
Valuation on West Japan Railway hinges on an earnings multiple that looks modest next to peers, with a P/E of 11.7x at a ¥3,036 share price that has lagged both the JP market and the wider transportation sector over the past year.
The P/E ratio compares what you pay for each ¥1 of earnings today with what investors are willing to pay for other companies. For a rail and transport operator that already generates profits, earnings based measures often carry more weight than sales based metrics, because they reflect both demand and cost control.
On that yardstick, West Japan Railway trades at a discount. Management is tagged as having high quality earnings and the stock is described as good value versus peers and the broader JP market. At the same time, forecasts point to only modest revenue growth of 2.7% a year and almost flat earnings growth of 0.03% a year. The combination suggests the market is pricing in slower profit expansion and the drag from a high debt load, rather than assigning a low multiple without reason.
The gap versus the JP Transportation industry and the wider market is clear. West Japan Railway sits at 11.7x earnings compared with 12.1x for its industry and 14.1x across the JP market, and the estimated fair P/E of 15.8x implies a level the valuation could move towards if sentiment on growth, leverage and returns improves.
Explore the SWS fair ratio for West Japan Railway.
Result: Price-to-Earnings of 11.7x (UNDERVALUED)
Still, West Japan Railway carries a sizeable debt load and relies heavily on domestic passenger demand. As a result, any setback in travel or funding conditions could quickly challenge the current valuation story.
Find out about the key risks to this West Japan Railway narrative.
Another View on West Japan Railway’s value
A second lens tells a very different story. Our DCF model points to a future cash flow value of ¥1,771.3 per share, which is well below West Japan Railway’s current ¥3,036 price. On that basis the stock screens as overvalued. So which signal should you trust more: earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
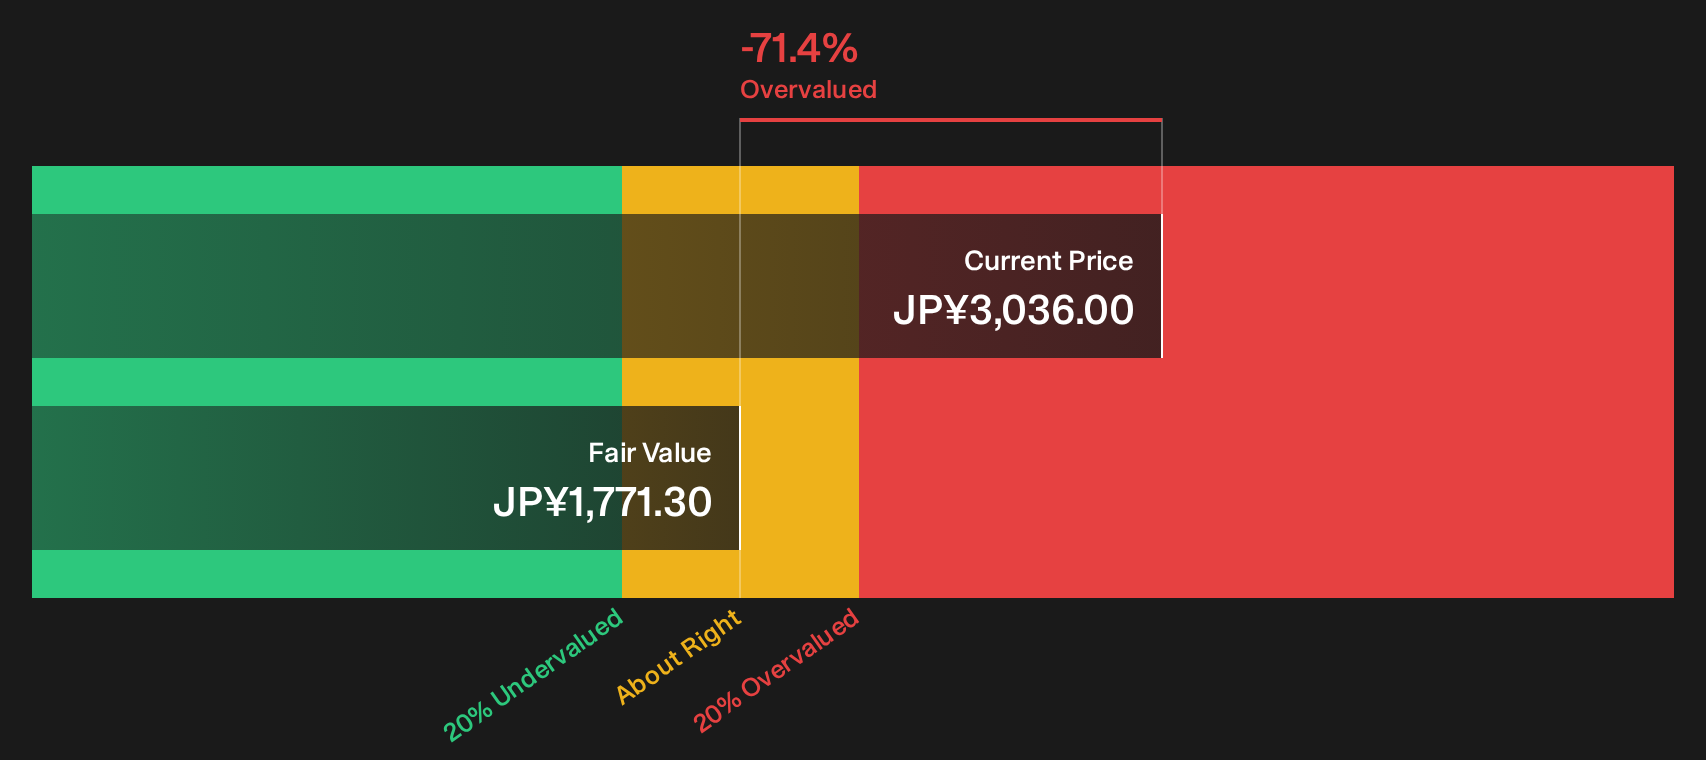
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out West Japan Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Confused by the mixed signals around West Japan Railway and what they really mean for risk and reward today? Act quickly, review the underlying data yourself, and then weigh the 2 key rewards and 2 important warning signs.
Looking for more West Japan Railway style ideas?
Do not stop with West Japan Railway. Use the Simply Wall Street Screener to hunt for other opportunities that fit your risk, income, and value preferences.
- Target potential mispricings by scanning companies that match your value checklist with the 17 high quality undervalued stocks
- Build a steadier income stream by focusing on businesses with strong yields and resilient payouts using the 14 dividend fortresses
- Cut portfolio stress by concentrating on businesses with stronger financial resilience through the 21 resilient stocks with low risk scores
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com