


Motorola Solutions (MSI) just secured a US$139 million, 10‑year contract with Louisiana, integrating its body cameras, in‑car video and command center software directly into the state’s public safety and radio network plans.
Set against that new Louisiana contract, Motorola Solutions’ share price is trading at US$458.67 after easing 4.5% over the past month but gaining 16.9% across 90 days, while total shareholder return over five years is 102%, which points to momentum that has been building over a longer horizon.
Scan how Motorola Solutions fits into the broader public safety and AI rollout story by lining it up against a curated group of 88 AI infrastructure stocks.
Bulls point to Motorola Solutions’ US$12.2b revenue base, its AI-led public safety focus, and its fresh Louisiana win. Bears highlight the recent pullback and a stretched value score. Which case does the current valuation actually support?
Most Popular Narrative: 12% Undervalued
On the most followed view of Motorola Solutions, a fair value of $521.82 sits above the recent $458.67 close. This frames the current pullback as a potential discount rather than a warning sign.
The accelerating focus on public safety and security fueled by heightened geopolitical instability, border security needs, and new government funding programs like the "One Big Beautiful Bill" is driving strong, sustained customer demand for advanced, integrated communication solutions. This expanding long-term tailwind is visible in Motorola's record Q2 orders, growing backlog, and consistent multi-year contract wins, supporting above-trend revenue growth and durability.
See why 31 investors see Motorola Solutions as 12% undervalued.
Result: Fair Value of $521.82 (UNDERVALUED)
Still, the bullish narrative around Motorola Solutions leans heavily on government budgets and successful software adoption, and a slowdown in either area could quickly challenge that 12% undervalued view.
Find out about the key risks to this Motorola Solutions narrative.
Another View: Multiples Paint Motorola Solutions As Expensive
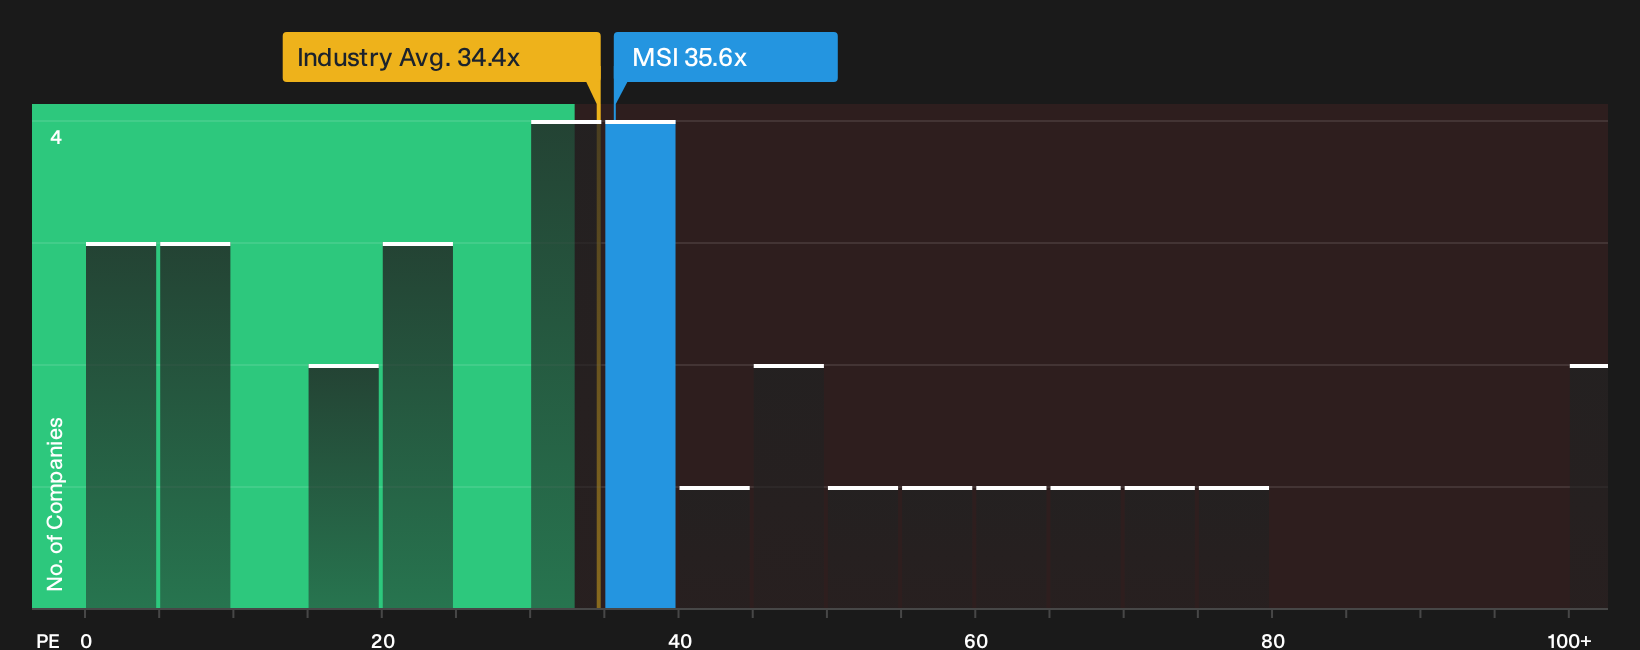
That 12% undervalued fair value story meets a different message when you look at Motorola Solutions through its P/E. The stock trades on 35.6x earnings, compared with an estimated fair ratio of 27.4x and a US Communications industry average of 34.4x, while peers sit much higher at 52.1x. If the market drifts toward the fair ratio instead of the analyst target, are you comfortable with the valuation risk that implies?
For a closer look at how that earnings multiple stacks up against broader comparables and what the fair ratio implies for future pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Motorola Solutions valuation and sentiment. If you want to move fast rather than just watch, consider both sides and review the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Motorola Solutions?
If Motorola Solutions has you thinking harder about valuation and contract-driven growth, do not stop here. Broader idea hunting can sharpen your next move.
- Target potential mispricing by scanning a focused set of companies that score well on valuation and fundamentals through the 35 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on businesses that feature resilient cash flows and robust payouts using the 7 dividend fortresses.
- Stack your watchlist with financially healthier prospects by running a list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com