


- Tesla has set October 1 as the launch date for its second generation Roadster with SpaceX linked technology, while also expanding into areas such as Terafab chip manufacturing, Project Crystal Sun solar capacity and European electric trucks.
- These moves deepen Tesla's push beyond cars into autonomy, energy, chips and robotics, while its Cybercab faces closer U.S. safety scrutiny and its core vehicle margins remain under pressure.
- We will now look at how Tesla's investment narrative could be affected by the firm deadline for its next generation Roadster reveal.
Compare Tesla's high multiple, AI heavy story with other potential breakouts by scanning a hand picked pool of 88 AI infrastructure stocks that sit at the crossroads of chips, power and data.
Tesla Investment Narrative Recap
Tesla asks you to believe that today’s pressure on automotive margins eventually gives way to higher quality earnings from autonomy, energy and AI heavy hardware like Terafab. The near term story still hinges on stabilising vehicle demand and protecting profitability while funding large projects in chips, solar and robotics that are not yet fully proven at scale.
The most important short term catalyst remains execution on deliveries and margins over the coming quarters, given recent share price weakness around delivery days. The biggest current risk is that capital intensive bets in Cybercab, Optimus and Terafab extend the period of thin margins and soft free cash flow without clear payback.
The clearest announcement that ties back to this catalyst and risk mix is the planned Terafab AI chip complex in Texas, now wrapped in a trademark dispute with TERA print. A US$16.8b chip project linked to Tesla and SpaceX speaks directly to the ambition to own key AI infrastructure rather than rely on external suppliers.
For you as a shareholder, that raises the stakes on execution. Success could support FSD, Optimus and data center workloads in house, tightening the link between software revenue and hardware capability. Missteps could add to already heavy R&D and capex, particularly at a time when deliveries, pricing pressure and regulatory questions around Cybercab remain in focus.
Tesla's narrative projects US$161.0b revenue and US$13.9b earnings by 2029. That path assumes 15.8% yearly revenue growth and an earnings increase of about US$10.1b from US$3.8b today.
Uncover why Tesla's fair value indicates a 7% potential upside to its current price before the market closes that gap.
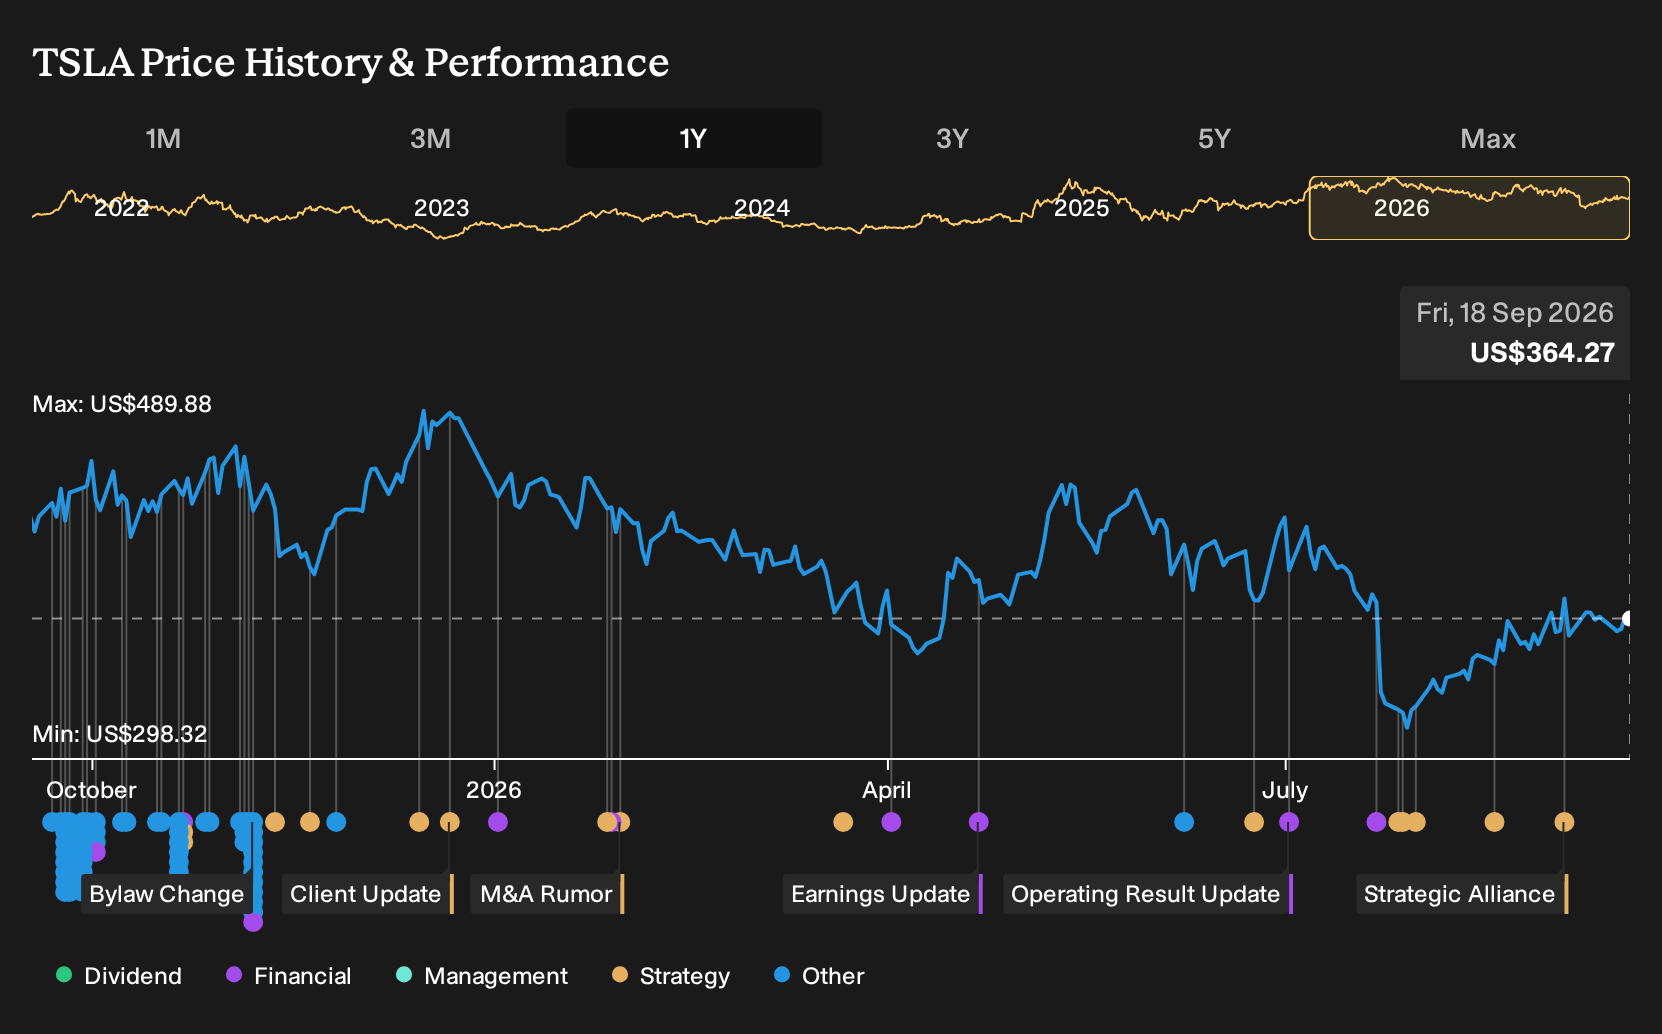
Exploring Other Perspectives
Some of the most optimistic analysts frame Tesla’s robotaxi rollout as the real swing factor, not the Roadster reveal. You can see it in their numbers. They were pencilling in revenue of US$214.1b and earnings of US$17.5b by 2029, compared with the US$161.0b and US$13.9b that consensus used before this news, so views may shift as new information becomes available.
Explore 39 other Tesla fair value estimates, including one that suggests there could be as much as 83% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tesla research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tesla. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tesla's overall financial health at a glance.
Looking For More Ideas Beyond Tesla?
If Tesla has sharpened your appetite for opportunity but you want a broader watchlist, the Simply Wall St Screener can help you spot other stocks that fit your style, whether you care more about value, resilience, or future potential.
- If you want potential value upside with quality fundamentals on your side, start by scanning a focused pool of 35 high quality undervalued stocks that already clear key balance sheet and cash flow checks.
- If sleep at night risk control matters just as much as returns, narrow your search to a curated set of 30 resilient stocks with low risk scores that score well on volatility and financial health factors.
- If you are hunting for stories that are not yet crowded, use the screener to track 16 high quality undiscovered gems that pair strong fundamentals with relatively low attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com